

Snowflake looks like one of the cleaner AI infrastructure stories in enterprise software. Revenue growth reaccelerated to +33.5% YoY, RPO and cRPO both grew +37.5%, net dollar retention improved to 126%, and net new ARR reached a record level, up +101% YoY. CoCo is moving from product demo to real consumption driver, while Snowflake Intelligence, Natoma, Cortex AI, and the expanded AWS and OpenAI partnerships strengthen the company’s position in the agentic enterprise.
The moat is widening. Data sharing now accounts for 44% of platform usage, Marketplace listings hit a record Q1 level, and large enterprise additions reached a first-quarter record. But, one question remains important: can Snowflake keep compounding growth while bringing SBC and dilution down fast enough?
Full analysis below.
Table of Contents:
1. Company Overview – A brief summary of the company, including its mission, sector, competitive advantage, and total addressable market (TAM).
2. Valuation – Analysis of changes in Forward EV/Sales and Forward P/E multiples, along with comparisons to peers within the same sector.
3. Economic Moat – Evaluation of the company’s moat across five key types: Economies of Scale, Network Effect, Brand, Intellectual Property, and Switching Costs.
4. Revenue Growth – Review of revenue growth dynamics over the past two years.
5. Segments and Main Products – Overview of the company’s business segments, latest quarterly performance by segment, product innovation.
6. Market Leadership – Assessment of the company’s leadership status in its segment, as recognized by reputable rating agencies like Gartner, The Forrester Wave, etc.
7. Customers – Analysis of customer growth trends, customer success stories, and major customer wins.
8. Key Performance Indicators (KPIs) – Review of Retention, net new ARR, CAC payback period, RDI score, Data sharing, Marketplace listings, profitability, operating expenses, balance sheet strength, and shareholder dilution.
9. Conclusion – Final thoughts and summary based on the above analysis.
1. Company overview
About Snowflake
Snowflake Inc. is an American cloud-based data storage company headquartered in Bozeman, Montana. Founded in July 2012 by Benoît Dageville, Thierry Cruanes, and Marcin Żukowski, the company operates a platform enabling data analysis and simultaneous access of data sets with minimal latency. Snowflake runs across Amazon Web Services, Microsoft Azure, and Google Cloud Platform.
Company Mission
Snowflake's stated mission is "to help every organization be data-driven" and its vision is "to help every enterprise achieve its potential with data and AI". Management operationalizes this through a single, unified platform that eliminates data silos across cloud providers, business units, and partner ecosystems. The company specifically engineers around two principles: frictionless data access and secure collaboration, enabling organizations to extract enterprise intelligence without data movement costs.
Sector and Services
Snowflake operates as a data cloud company providing comprehensive data platform services. The platform supports multiple workloads including data warehousing, data lakes, data engineering, artificial intelligence, machine learning, and applications. Key sectors served include advertising, media and entertainment, financial services, healthcare and life sciences, manufacturing, public sector, retail and consumer goods, technology and telecom. The company employs between 5,001-10,000 employees and maintains a public company status.
Competitive Advantage
Snowflake's competitive edge stems from four core technological features. Serverless technology allows all computing resources to be managed and provided on demand by Snowflake. Micro-partitions enable high-performance levels by storing data vertically per column with metadata for accelerated queries. The platform features separation of storage and compute, enabling independent scaling of resources. Multi-cloud functionality provides seamless operation across major cloud platforms. Cortex AI and the Arctic LLM embed AI workloads natively into governed enterprise data, reducing the need for third-party AI infrastructure and extending the platform's competitive perimeter.
Total addressable market (TAM)
Snowflake’s January 2025 investor update values its total addressable market (TAM) at ~$170B today and projects it will exceed $340B within three years. Analyst forecasts are consistent, estimating the TAM will more than double from $170B in 2024 to $355B by 2029, reflecting a 16% CAGR.
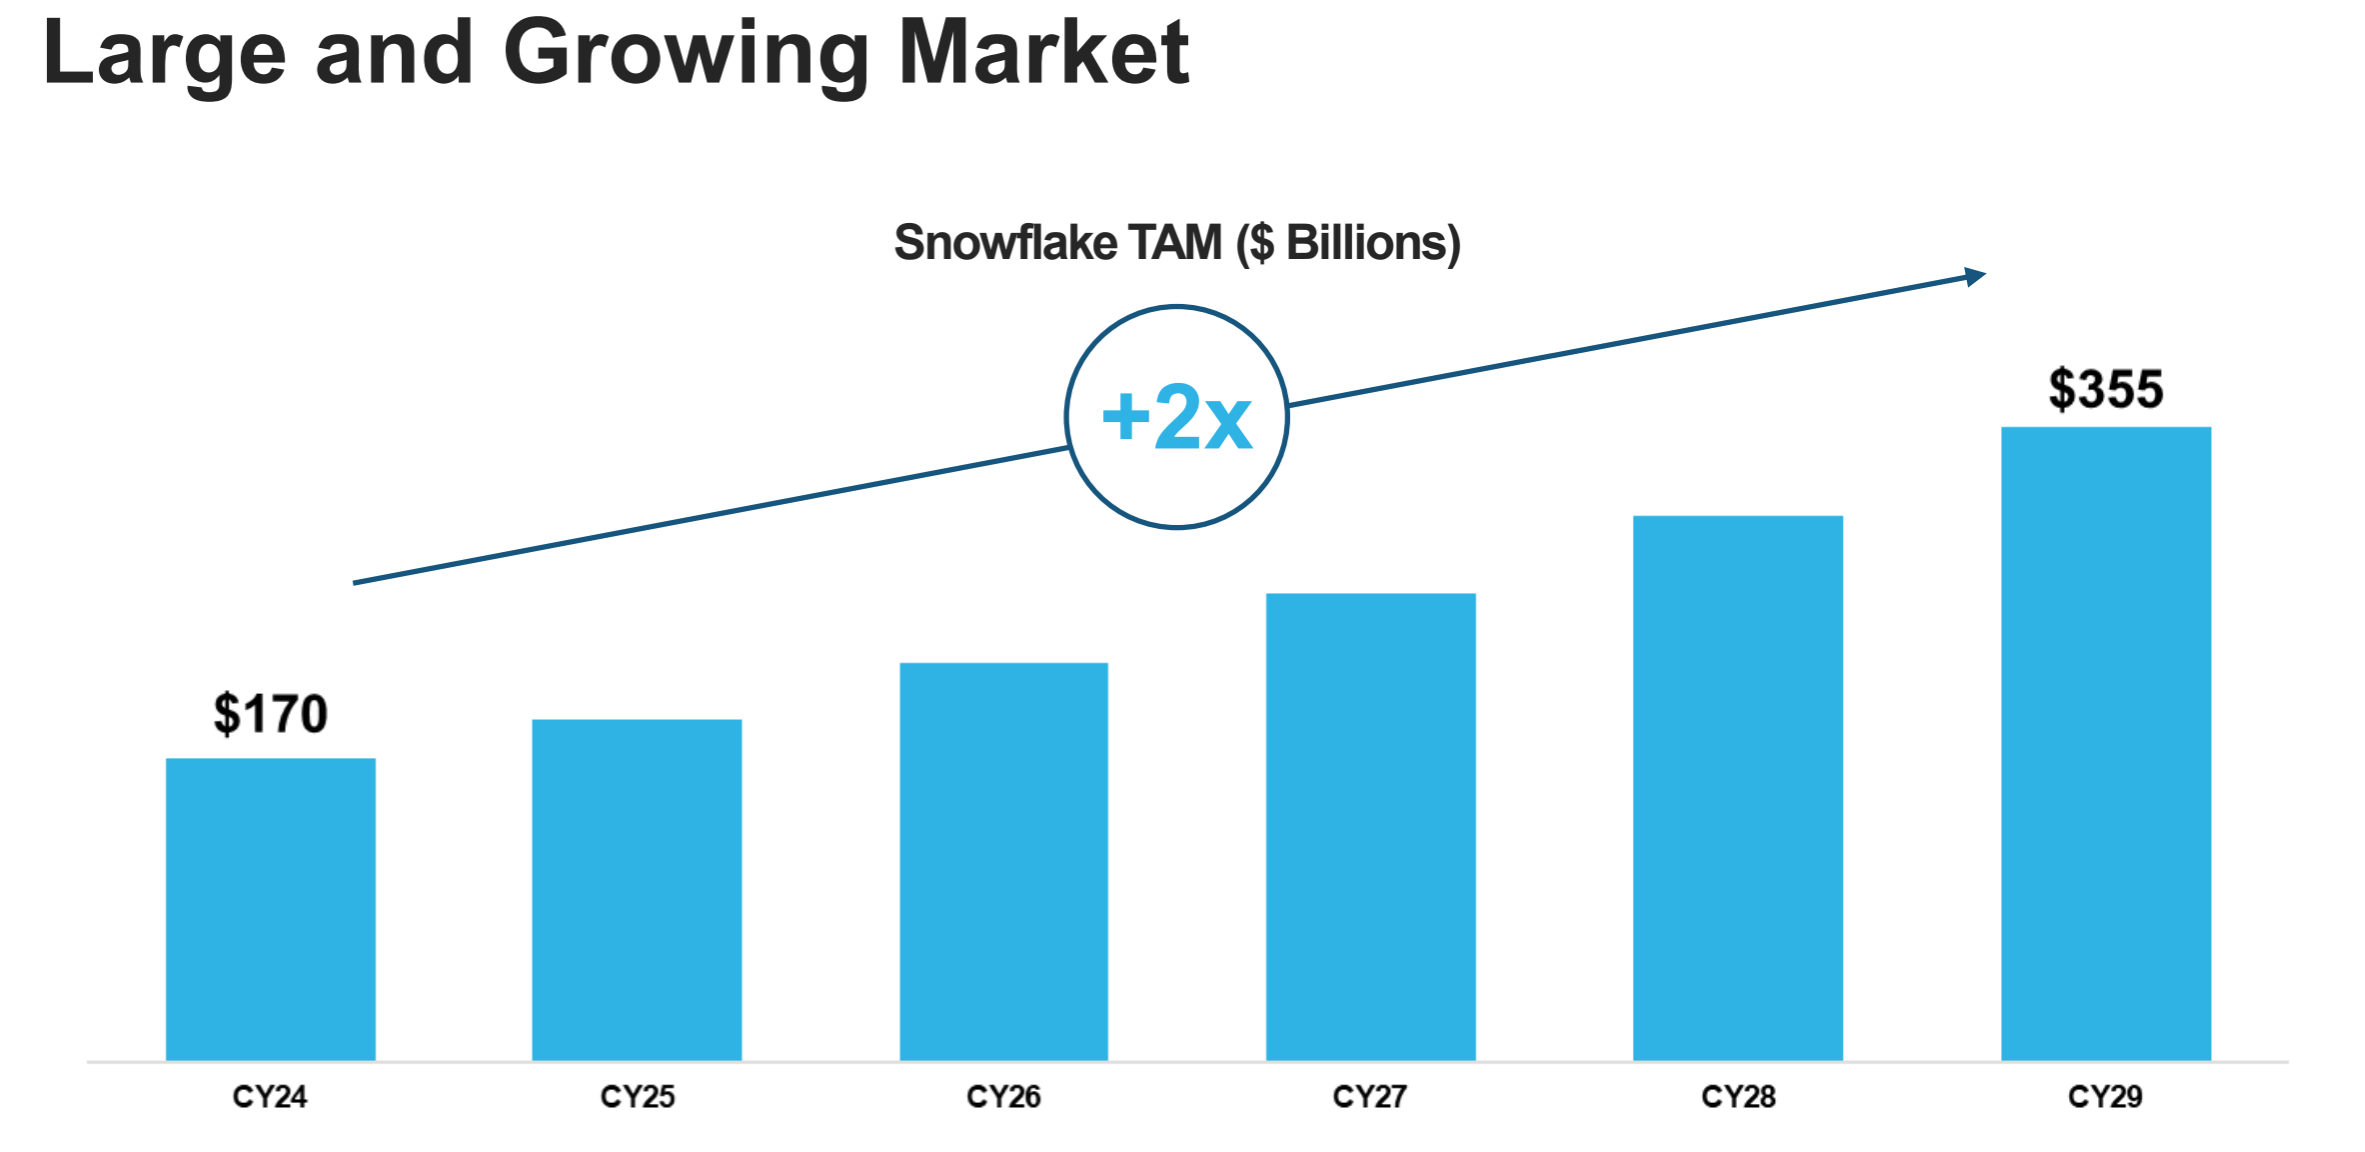
The opportunity spans several high-growth segments. The cloud data warehouse market is expanding from $28.5B in 2023 to $42.4B by 2025 with a 22.3% CAGR. The data analytics platform market is set to grow from $65.2B to $94.7B over the same period, a 20.5% CAGR. Data sharing solutions are accelerating from $13.8B to $24.3B, marking a 32.7% CAGR. The fastest growth is in AI/ML data infrastructure, projected to surge from $19.6B to $41.2B, achieving a 45.1% CAGR.
2. Valuation
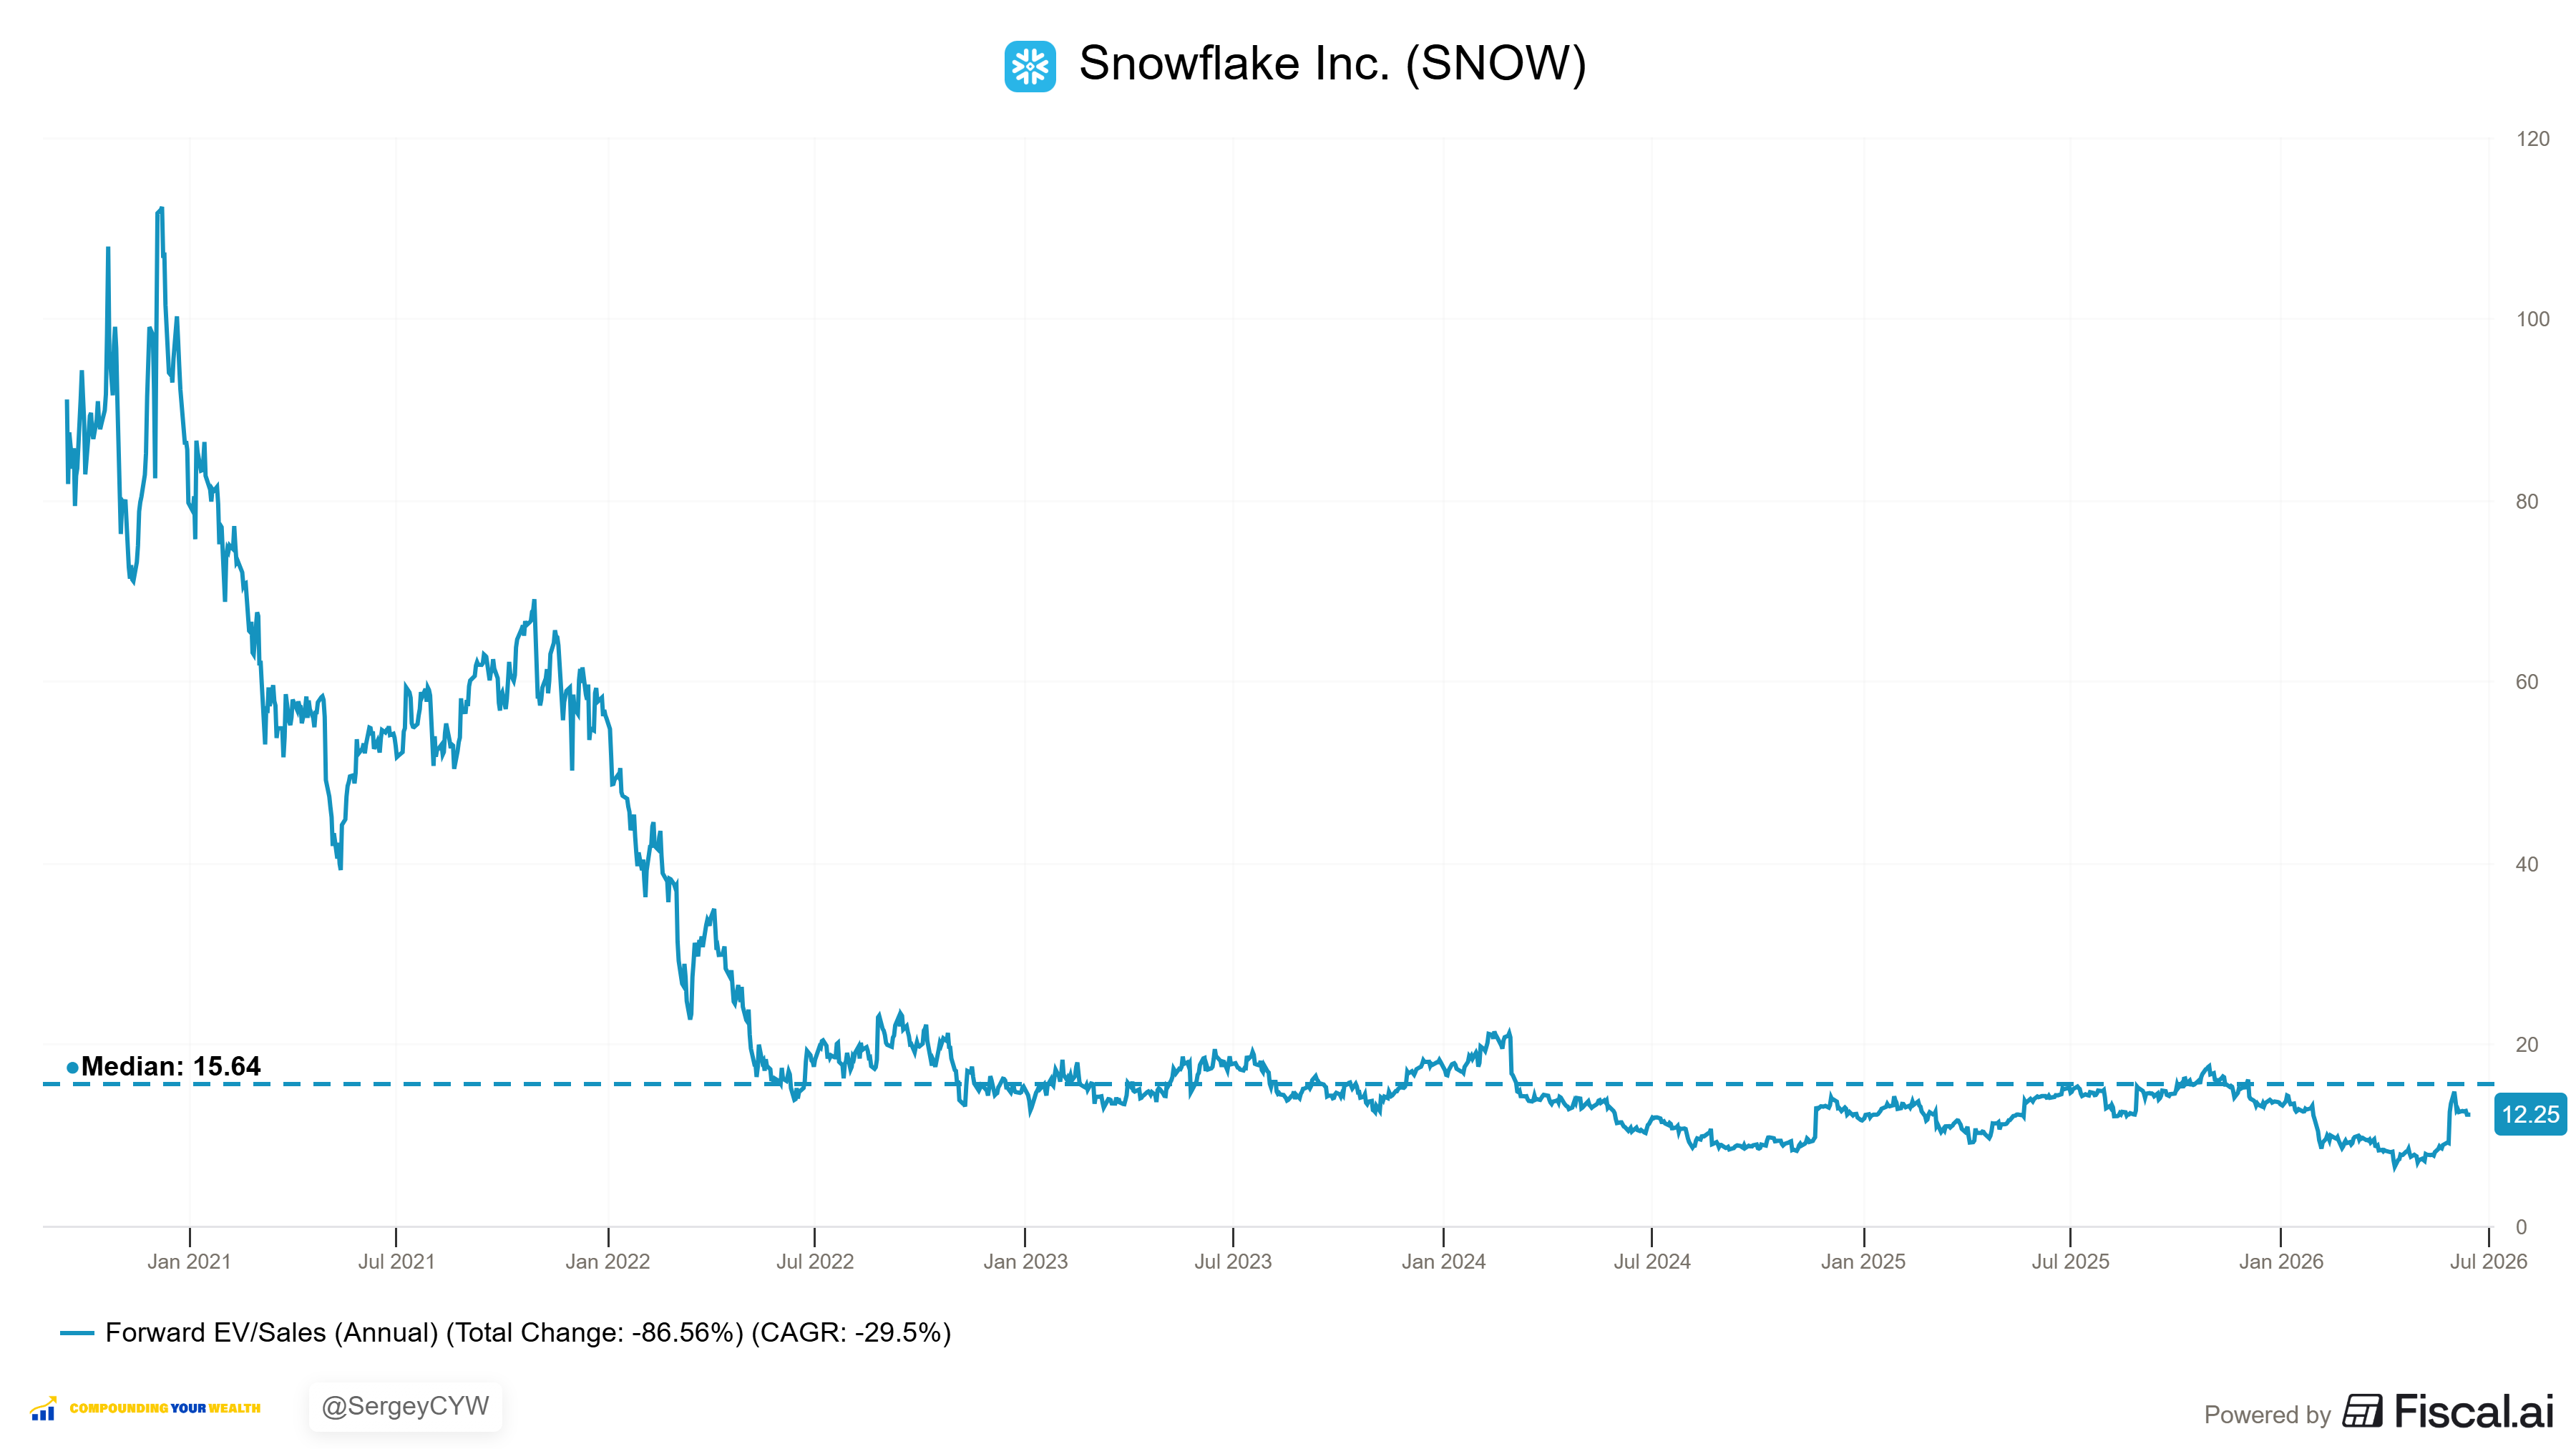
After a significant decline from more than 100x EV/Sales following its IPO, SNOW’s valuation fell to a historical low of 6.5x on April 10, 2026. Since then, the multiple has recovered, and the company is now trading at a Forward EV/Sales multiple of 12.3x.
However, this remains below the lows seen during 2022–2023 and below the median multiple of 15.6x.
Powered by Fiscal.ai — get 15% off with affiliate link for Compounding Your Wealth readers.
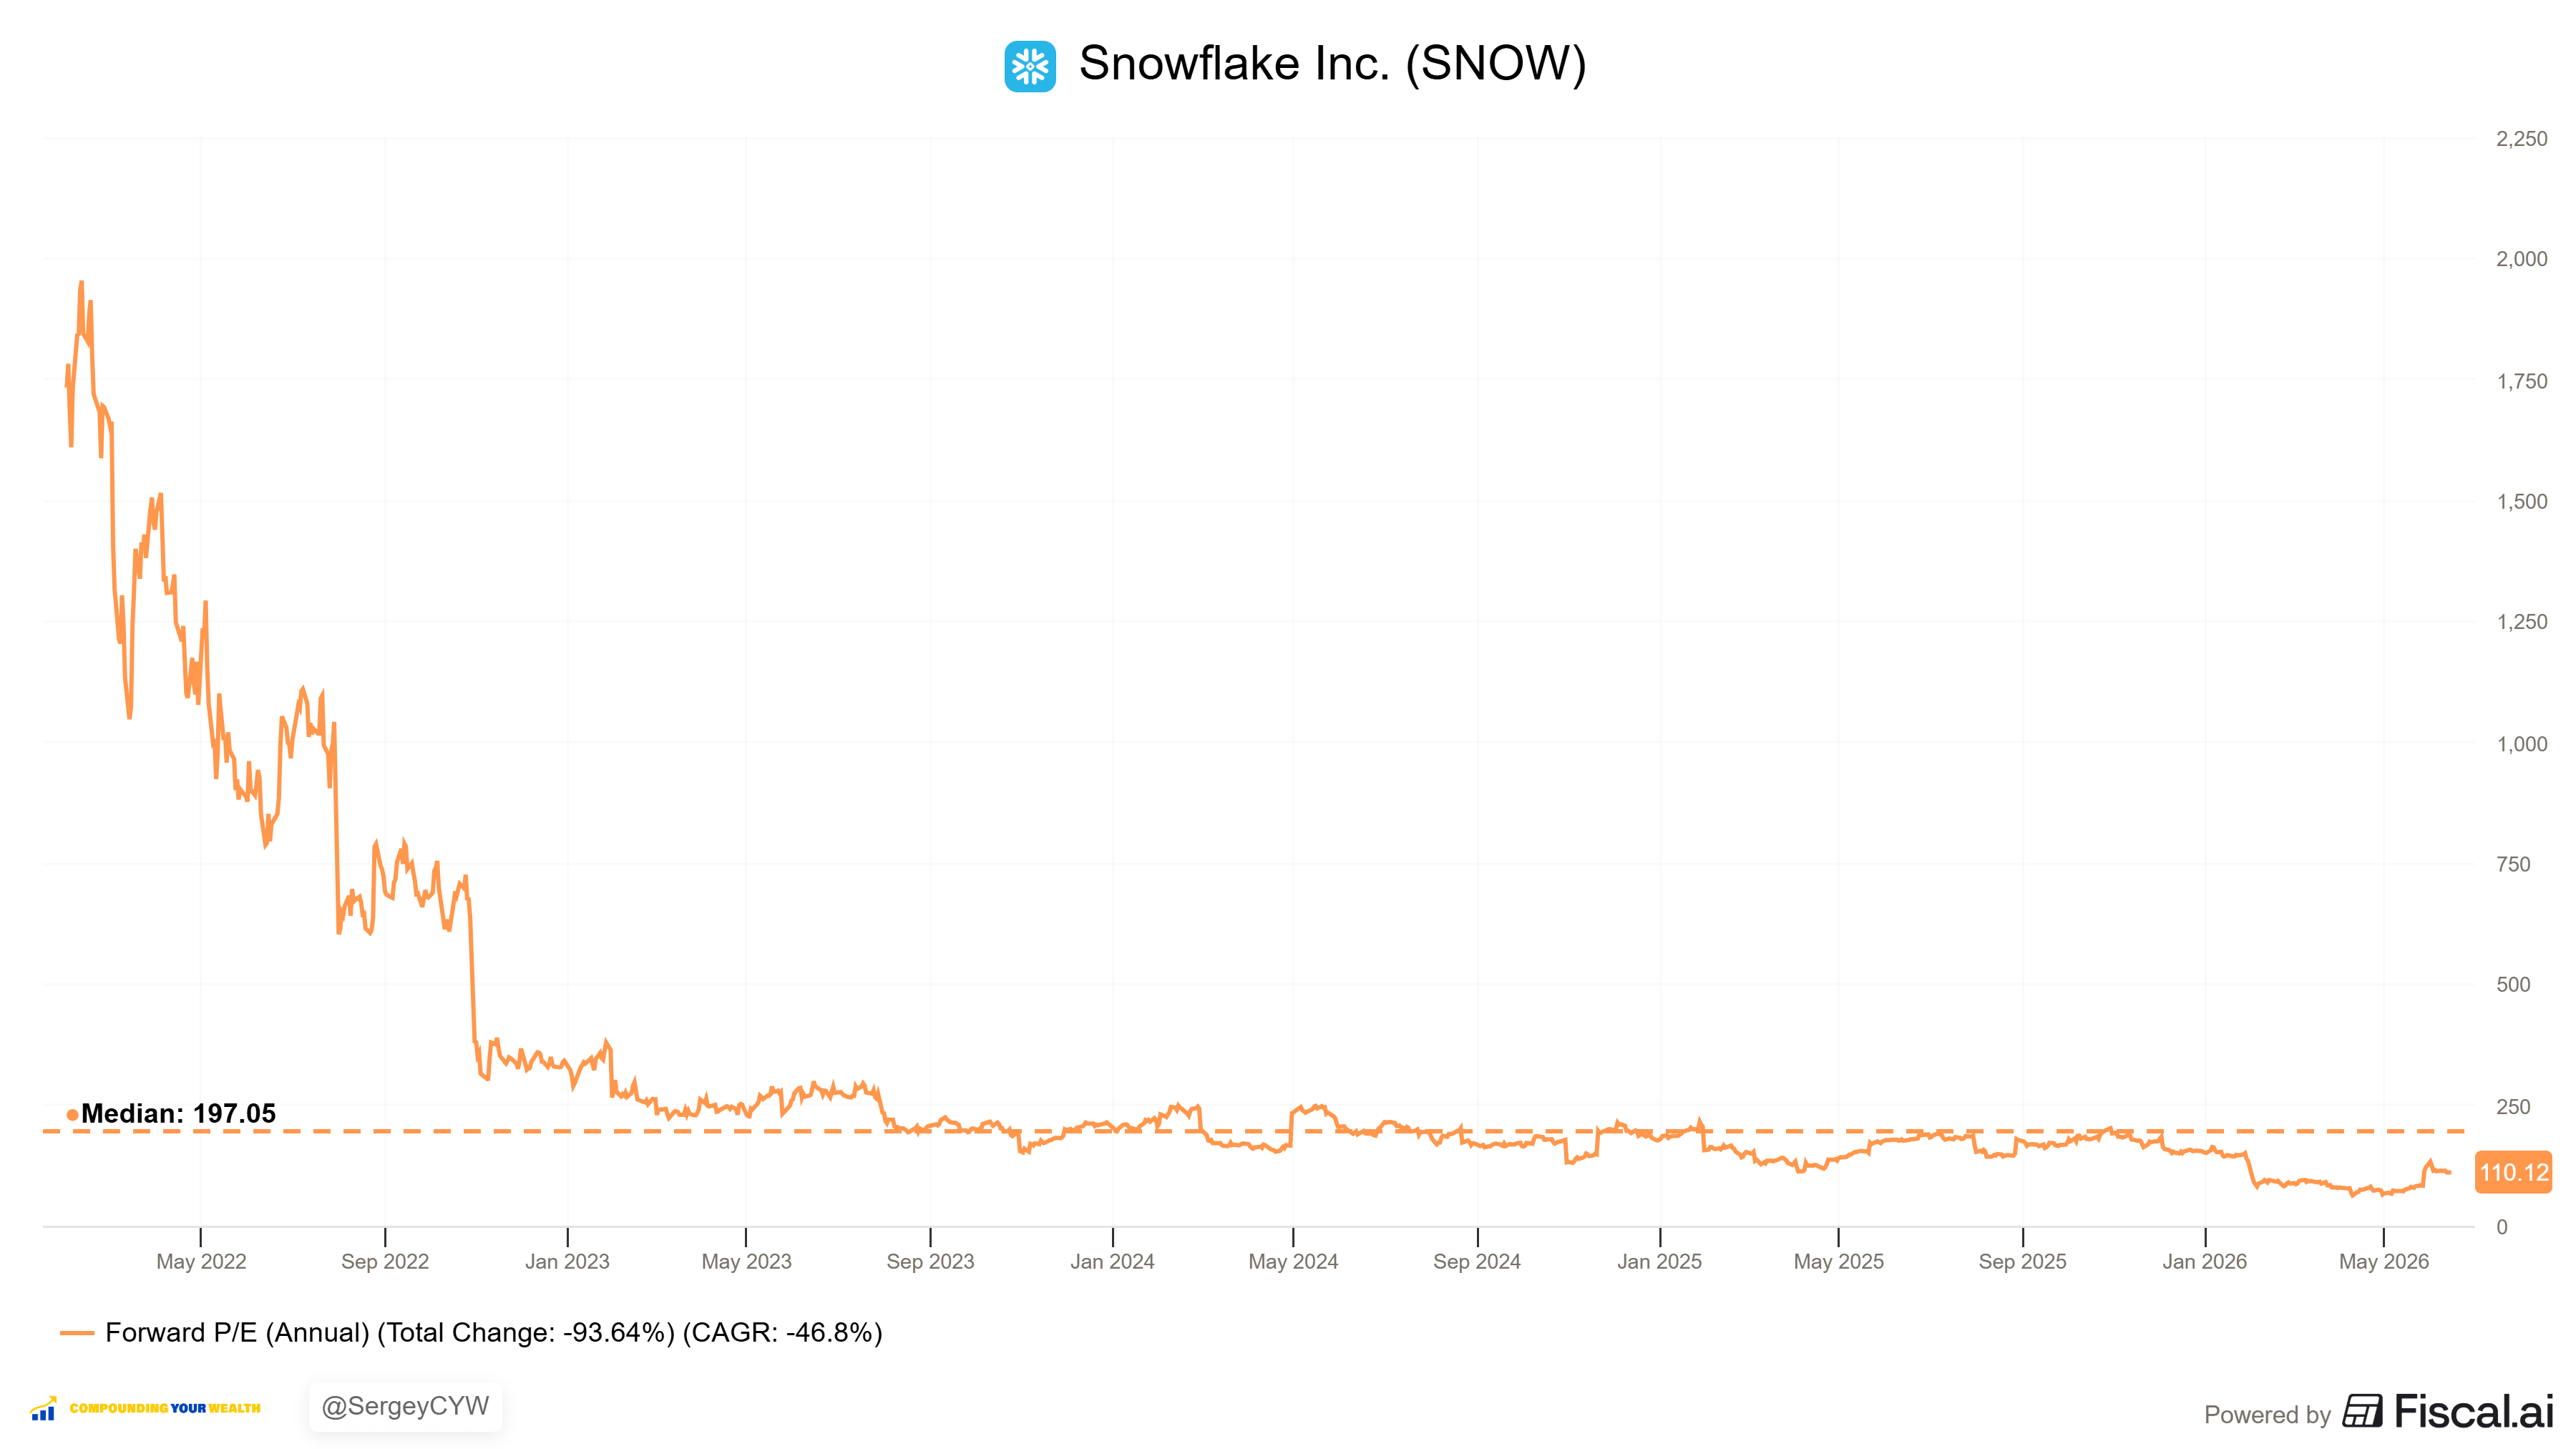
SNOW trades at a Forward P/E of 110.1x, significantly below the median of 197.1x. In 2024, under new CEO Sridhar Ramaswamy, the company significantly increased operating expenses, particularly in R&D, effectively returning to an earlier stage of growth investment.
The EPS growth forecast for 2026 is 55%, implying a 2026 P/E of 134x and a 2026 PEG ratio of 2.4.
Powered by Fiscal.ai — get 15% off with affiliate link for Compounding Your Wealth readers.
The PEG (Price/Earnings to Growth) ratio is a key tool for evaluating growth stocks, introduced by Peter Lynch.
PEG < 1: Undervalued – A ratio below 1 suggests the stock is undervalued. For example, if the P/E is 15 and earnings are expected to grow by 20%, the PEG would be 0.75, indicating a good buying opportunity.
PEG = 1: Fair Value – A PEG of 1 means the stock price matches its growth expectations, representing fair value.
PEG > 1: Overvalued – A PEG above 1 indicates the stock may be overvalued, as its price is higher than its projected growth rate, making it riskier.
Valuation comparison
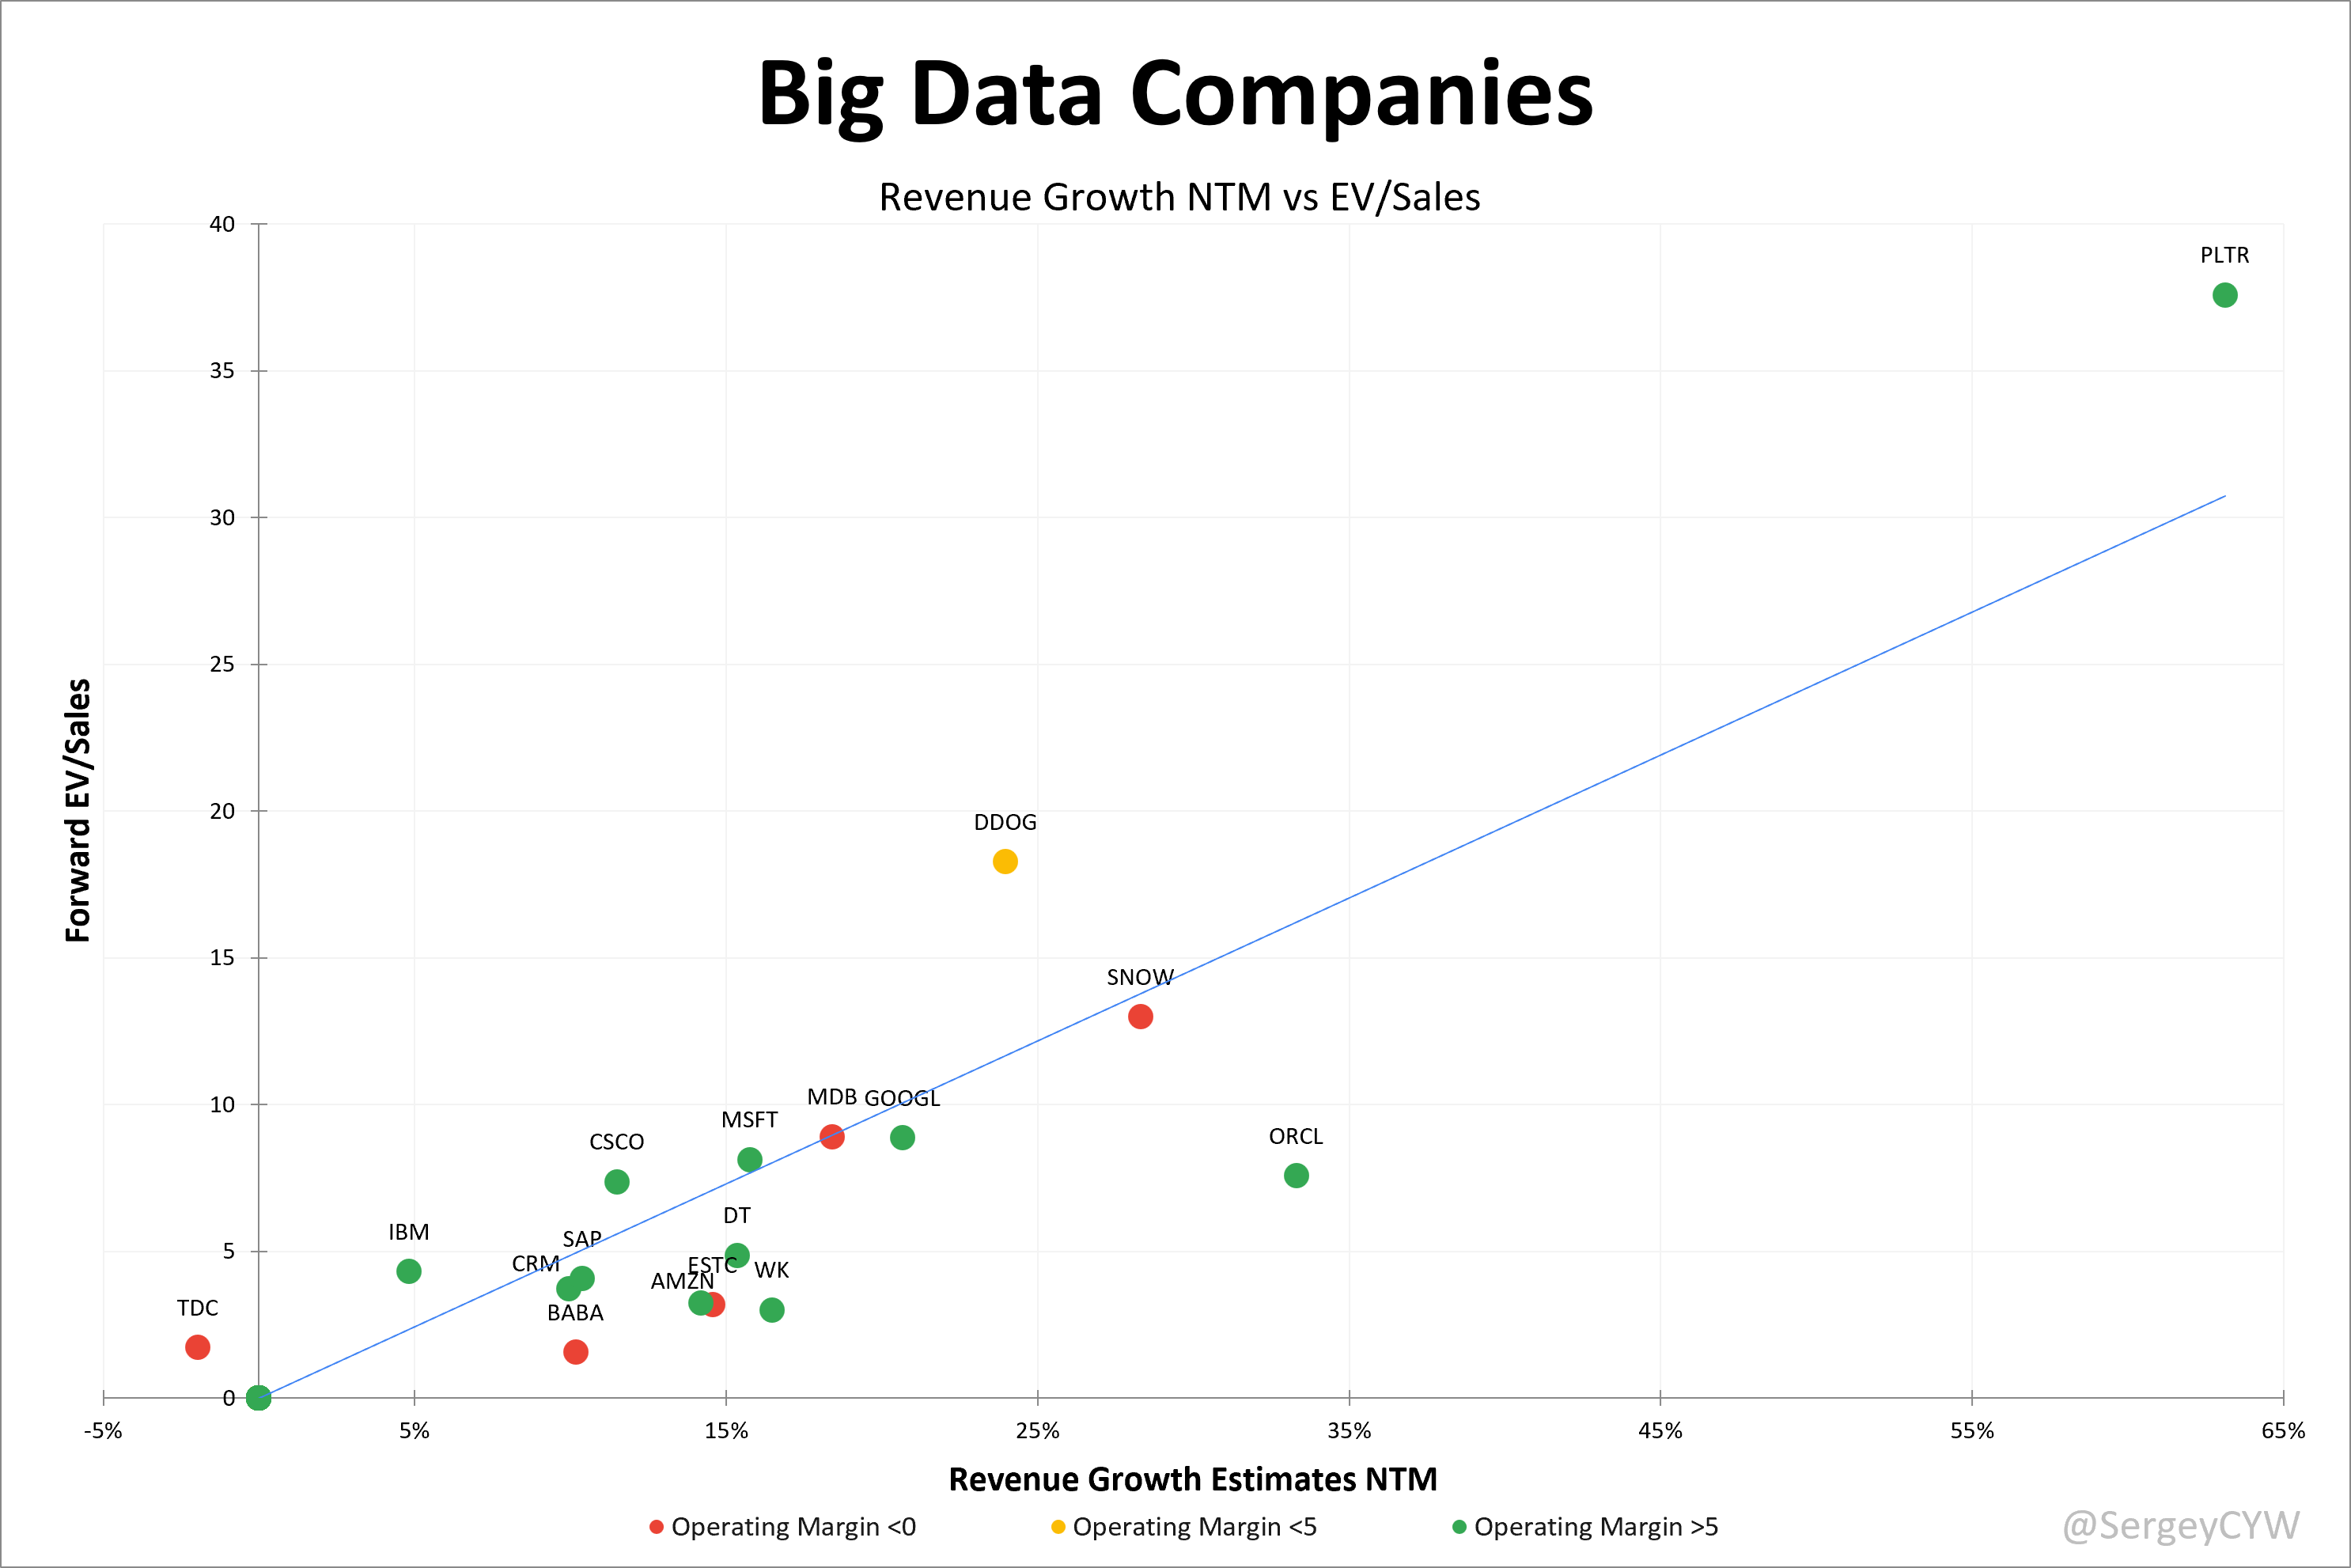
Analysts forecast SNOW’s NTM revenue growth at +28.3%, one of the highest growth rates among companies in the Big Data space.
Considering this expected NTM revenue growth, Snowflake’s valuation based on the EV/Sales multiple trades below the median relative to its projected revenue growth when compared to its peers in the Big Data sector.
Analysts expect strong revenue growth, so let's examine the key metrics to determine whether these expectations are justified.
We'll evaluate the company's economic moat, which supports long-term revenue growth, analyze revenue trends and the forecast for next quarter, and identify key factors that could help the company exceed expectations and sustain future growth.
We'll assess the performance of key segments, the launch of new products and updates, customer acquisition growth, key financial metrics, financial stability, and margin trends.
Additionally, we'll review the SBC/Revenue ratio, shareholder dilution, and finally, draw conclusions on the company's outlook.
3. Economic Moat
Snowflake has built a strong economic moat in cloud-based data warehousing and analytics, securing its competitive position and driving long-term revenue growth.
Economies of Scale
Snowflake's multi-cloud architecture and vast customer network allow it to realize significant economies of scale. As the platform scales, infrastructure and development costs spread across a larger base, improving unit economics. While revenue grew to $1.39 billion (+33.5% YoY), remaining performance obligations hit $9.210 billion, a 37% YoY increase, providing strong forward visibility to sustain these scale advantages. Management does not position Snowflake as a low-cost leader, but its scale allows for competitive pay-as-you-go pricing.
Network Effects
Snowflake's Data Marketplace functions as a two-sided platform—more data providers attract more consumers, which in turn draws additional independent software vendors. In Q1 CY2026, Snowflake added record 293 new Marketplace Listings, with listing growth accelerating to 28% YoY. Data sharing now accounts for 39% of platform usage, up from just 21% in Q4 2025. As more organizations join the ecosystem, the data-sharing capabilities become increasingly valuable, making the platform more attractive to new enterprise clients.
Brand Strength
Snowflake has earned recognition as the enterprise standard for cloud data warehousing, counting 751 of the Forbes Global 2000 among its customer base. Securing two contracts exceeding $100 million in a single quarter - both in financial services - validates institutional brand confidence. Yet against hyperscalers like AWS Redshift, Azure Synapse, and Google BigQuery, Snowflake's brand alone offers limited pricing power. Brand operates as a supporting layer, not a standalone moat.
Intellectual Property
Snowflake's proprietary decoupled compute-storage architecture remains a key technical differentiator. Its ability to operate identically across AWS, Azure, and Google Cloud — without data movement costs — is a structural advantage competitors cannot easily replicate. The platform's Cortex AI and Arctic LLM represent newer intellectual property layers embedded directly into the data platform, expanding beyond traditional warehousing. Still, Databricks has closed the technical gap meaningfully. By 2026, analysts observe that both platforms offer nearly identical capabilities, with Snowflake winning on ease of use and Databricks on open-source flexibility.
Switching Costs
Snowflake creates very high switching costs that lock in customers through operational complexity and risk. Migrating petabytes of mission-critical enterprise data, rebuilding analytics pipelines, retraining internal teams, and reconfiguring BI layers is a multi-year, high-risk undertaking — the operational deterrent is structural rather than financial. The 126% net revenue retention rate demonstrates how effectively these switching costs work in practice, as customers not only stay but expand their usage. The consumption-based pricing model and deep data integrations create substantial exit barriers for enterprise customers. Switching costs are the primary driver of durable revenue visibility and Snowflake’s strongest individual moat element.
Snowflake's economic moat is primarily built on very strong switching costs and network effects and strong economies of scale. While brand strength and intellectual property provide additional protection, the most formidable barriers come from the operational complexity of switching providers and the self-reinforcing value of its data-sharing ecosystem.
4. Revenue growth
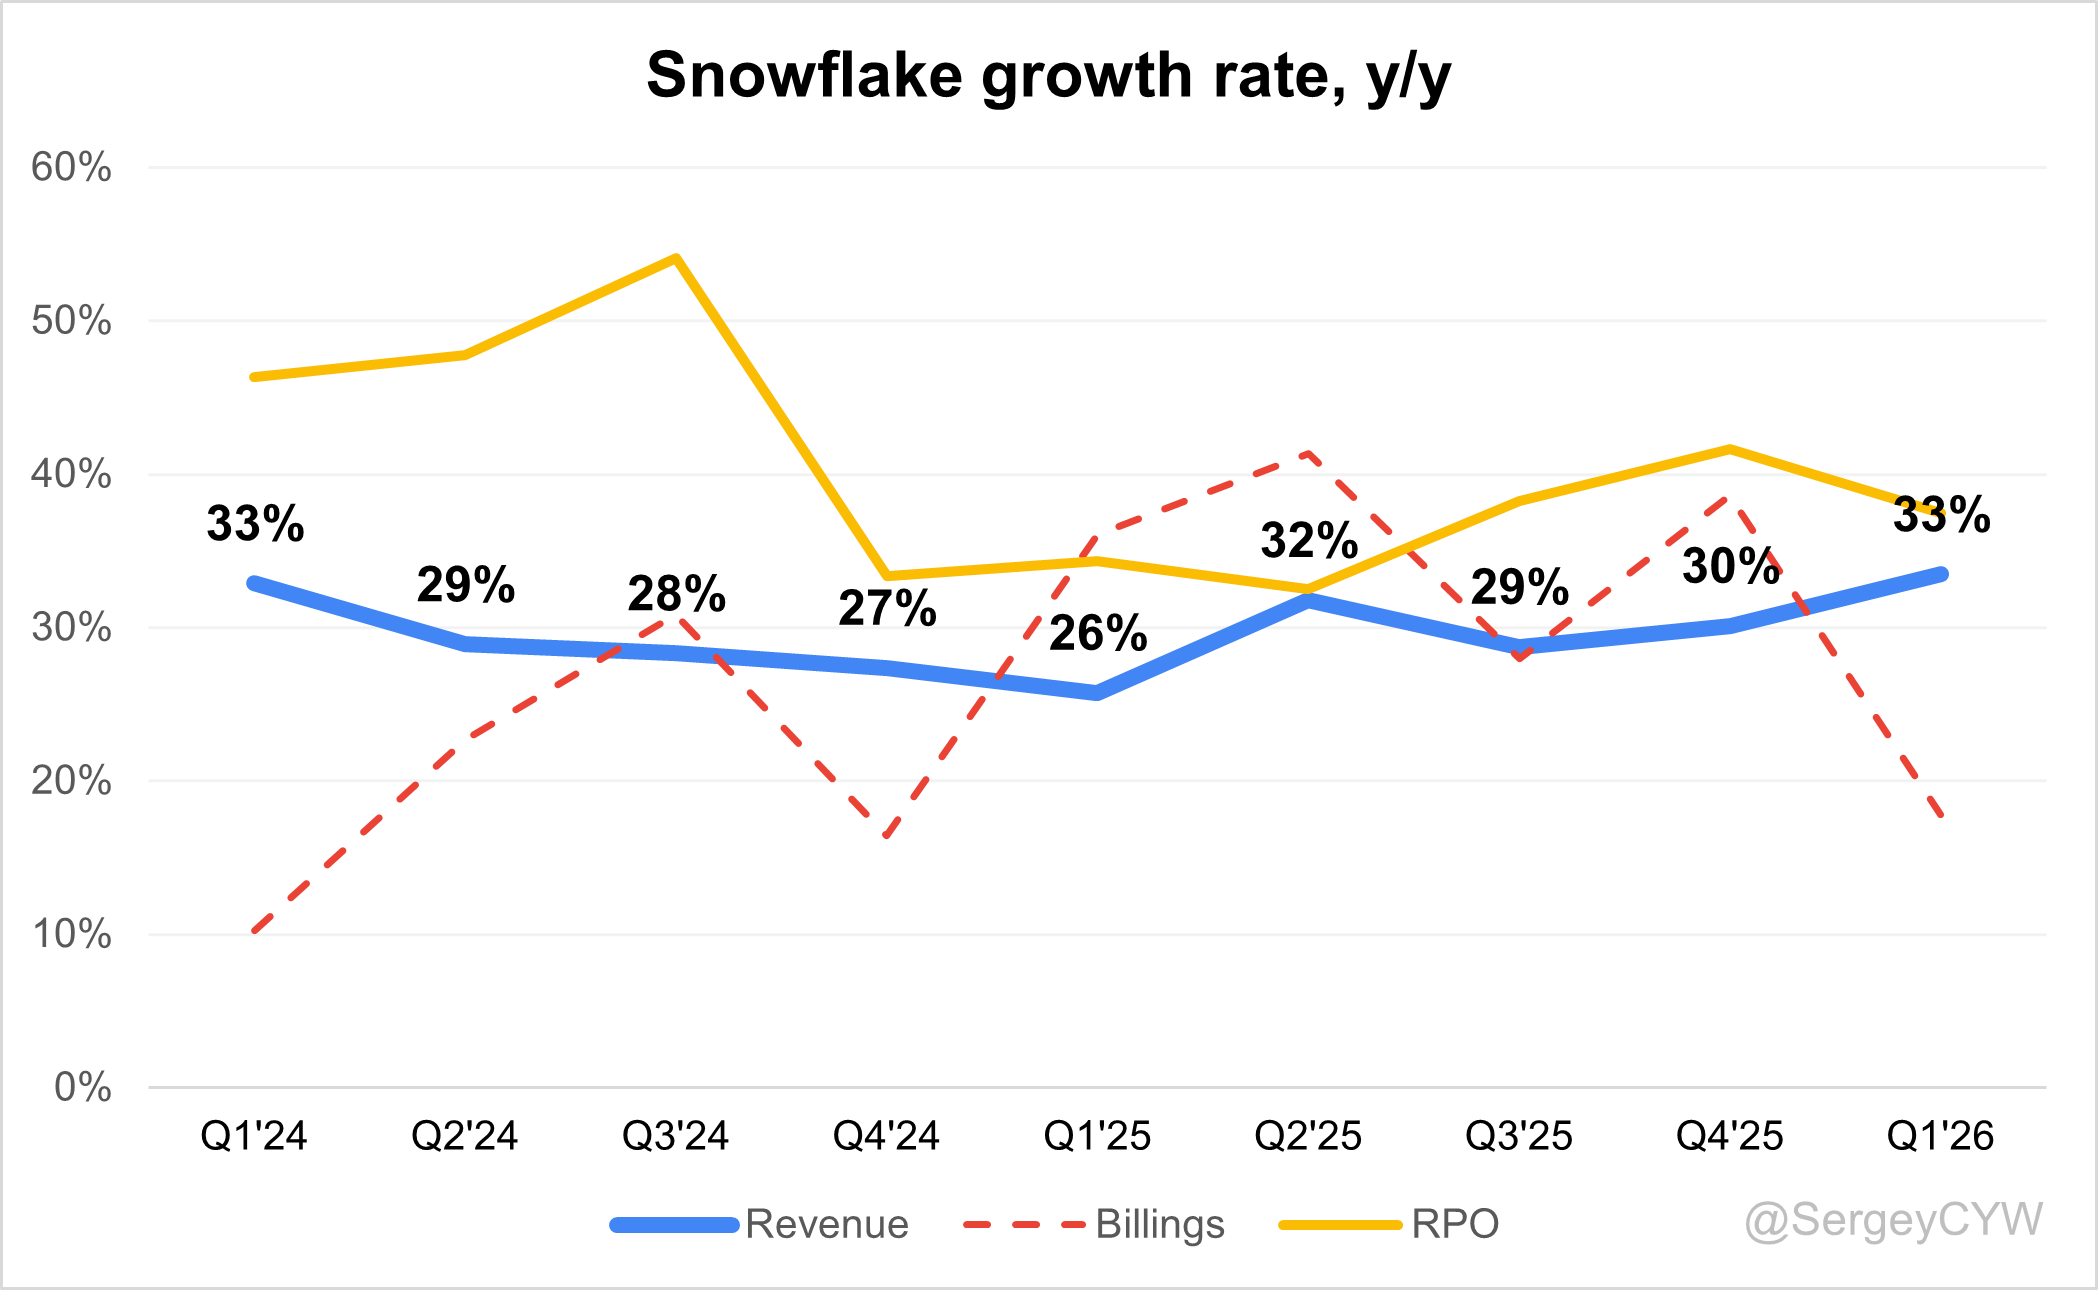
SNOW’s revenue growth accelerated noticeably from +30.1% YoY in Q4 2025 to +33.5% YoY in Q1 CY2026.
RPO growth slowed slightly to +37.5% YoY (from +41.6% YoY in Q4 2025), but it still outpaced revenue growth. Since Snowflake operates on a usage-based pricing model rather than subscriptions, cRPO is the key metric to monitor. Encouragingly, cRPO growth accelerated to +37.5% YoY, remaining above the company’s revenue growth rate.
Billings growth slowed to +17.8% YoY, growing at a slower pace than revenue. However, for a usage-based pricing model, billings tend to be a more volatile metric and are often less indicative of underlying business momentum.
Looking ahead, if the company beats its own guidance by 5.3%, matching the level of outperformance delivered this quarter, Q2 revenue growth would reach 36.2% YoY, signaling continued acceleration.
5. Segments and Main Products.
Snowflake's revenue primarily consists of two segments: Product and Professional Services.
Product segment generates the majority of revenue (95,2%), driven by Snowflake's core offerings like data warehousing, data lakes, data engineering, data science, and secure data sharing capabilities.
Professional Services and Other contribute a smaller portion of revenue at around 4-5%, involving consulting, training, and implementation support to help customers maximize their use of Snowflake's platform.
Key products include Snowpipe for seamless real-time data ingestion from external cloud storage like Amazon S3 or Azure Blob.
Snowflake Marketplace allows verified data sharing and collaboration among organizations, offering datasets and services that meet quality and security standards.
The company's AI initiatives are integrated into its Cortex platform, hosting leading AI models from OpenAI and Anthropic, enabling advanced analytics and AI-driven insights.
Snowflake also offers Native Apps through its Marketplace, enabling customers to deploy third-party solutions directly into their Snowflake instances for enhanced functionality.
The core platform provides integrated cloud services for data warehousing, data lakes, data engineering, analytics, and secure data sharing across scalable cloud infrastructure.
Main Products Performance in the Last Quarter
Cortex AI
Cortex AI is moving from experimentation into workflow automation. Snowflake introduced Cortex Sense, designed to improve CoCo and CoWork quality by adding runtime context about users and data. Management framed it as early, but strategically important, because customers want answers live “as soon as possible.” The main challenge remains reliability across different customer scenarios, while the opportunity is better answer quality at lower cost.
Cortex Code / CoCo
CoCo is becoming the core AI adoption driver. CoCo gives developers a natural-language interface to build applications, data pipelines, agents, workflows, migrations, Dynamic Tables, and Snowflake-native projects faster.
CoCo reached general availability on February 5 and became the largest driver of Snowflake’s higher full-year forecast. More than 7,100 accounts were already using CoCo, making it one of the fastest-adopted products in Snowflake’s history. CoCo creates both direct AI revenue and higher core platform consumption. Faster building leads to more workloads, more data movement, more pipelines, and higher Snowflake usage. Customer examples showed strong productivity gains.
The main challenge is cost and margin. AI products have lower gross margins than Snowflake’s core platform, and token-based usage can scale quickly. Snowflake is building cost controls at the account, agent, and user level. Full-year non-GAAP product gross margin guidance remained at 75%, supported by infrastructure efficiencies and the AWS agreement.
Snowflake Intelligence / CoWork
Snowflake Intelligence is built for business users. It allows teams to ask questions, understand enterprise data, and trigger actions through a natural-language interface inside a governed Snowflake environment. Accounts using Snowflake Intelligence more than doubled quarter over quarter. Adoption moved from early interest toward broader enterprise use. A large wealth management firm built a Cortex-powered agent called Ask Your Data and deployed it to the executive leadership team.
Snowflake Intelligence evolved into CoWork, shifting from analytics-only use cases toward a personal work agent connected to Gmail, Drive, Salesforce and other enterprise apps. Customer examples include WHOOP, United Rentals, Domino’s Australia, and one large bank building personalized executive workflows. Management sees CoWork as an expansion product, but admitted large deployments are still early and need proof at scale.
Apache Iceberg
Iceberg is positioned as a major interoperability layer. Snowflake said it has the broadest implementation of the Iceberg V3 spec, is helping steer V4, and integrated REST catalog APIs into Horizon. Snowflake can read and write data across external environments, including Databricks, Glue and other engines. The biggest update is Snowflake-managed storage for Iceberg, now generally available, which should reduce customer friction while keeping interoperability.
Snowpark
Snowpark is benefiting from AI-assisted migrations. Management highlighted renewed momentum in Spark migrations because CoCo reduces the pain of code conversion. One customer converted from Spark to Snowpark and achieved performance and cost improvement of roughly 5x. Challenge remains compatibility for legacy Spark APIs, but AI lowers the switching cost and supports faster migration cycles.
Product Innovations and Updates
Snowflake’s product roadmap is centered on making the platform easier, more connected, and more trusted. New updates include CoCo Desktop GA, Excel and VS Code form factors, Cloud Code marketplace plugin, Artifact Repository for live governed dashboards, Cortex Sense, Natoma integration with 100+ business systems, Datastream for low-latency data capture, Snowflake-managed Iceberg storage, Data Clean Room enhancements, Horizon Context, Adaptive Compute, and interactive analytics.
Natoma Acquisition
Snowflake announced the intended acquisition of Natoma, adding 20 employees. Natoma extends Snowflake’s agentic control plane into everyday business applications. Natoma would let users send emails, summarize Slack conversations, check calendars, and open Jira tickets from Snowflake Intelligence or CoCo. Management emphasized control over convenience. Actions would run inside a governed environment with security, permissions, observability, and policy enforcement. The acquisition supports Snowflake’s view of enterprise AI agents as action systems, not only question-answering tools.
6. Market Leadership
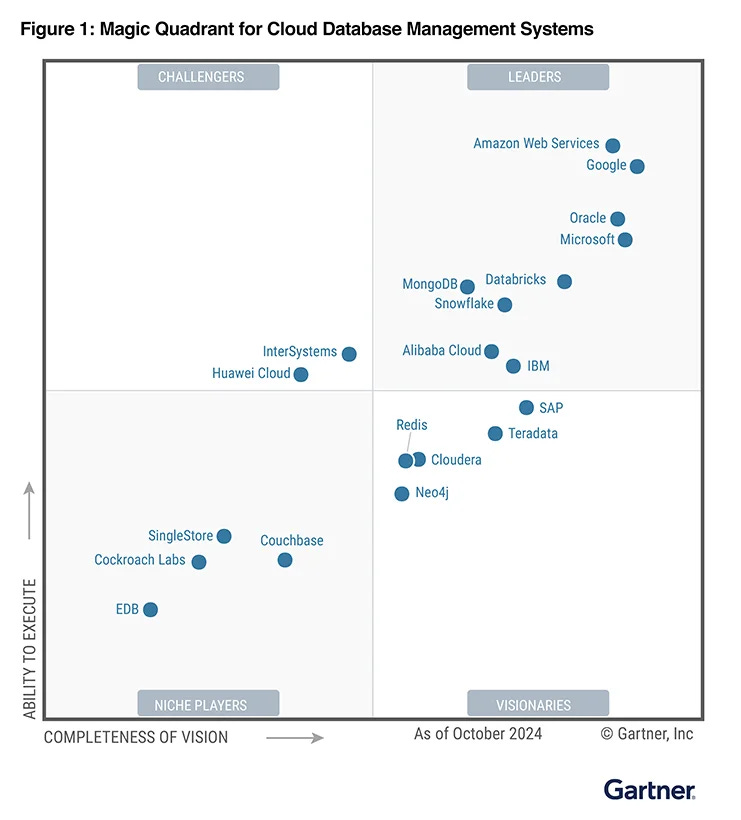
Gartner ranks Snowflake as a leading provider in the cloud database management systems (DBMS) market. Its Data Cloud is recognized as a unified, cloud-native platform supporting data warehousing, data lakes, analytics, and AI workloads. The company is strong in managing structured and semi-structured data, with multi-cloud support, auto-scaling, and robust data sharing capabilities that differentiate its offering.
Forrester analysis from Snowflake Summit 2025 acknowledges the platform's evolution beyond traditional data warehousing into comprehensive AI capabilities. The research firm recognizes Cortex AISQL as expanding Snowflake's reach into multimodal data analysis, enabling users to query text, images, and audio directly with SQL. Forrester notes Snowflake's approach to multimodal SQL stands out for comprehensive coverage and practical implementation compared to competitors.
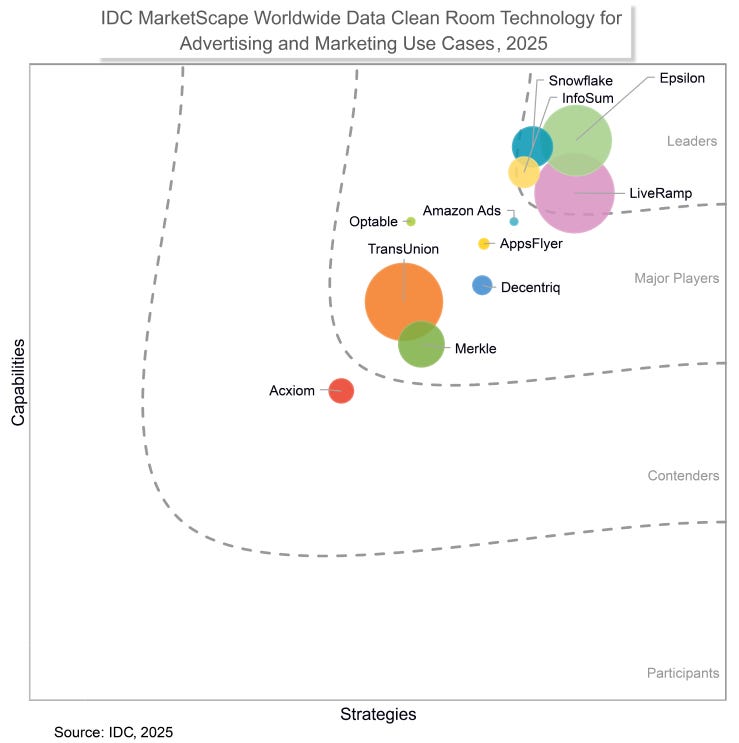
IDC named Snowflake a Leader in the MarketScape for Data Clean Room Technology for Advertising and Marketing Use Cases 2025. The research firm calls Snowflake Data Clean Rooms "an ideal solution for advertisers and marketers seeking secure collaboration tools to optimize campaigns in a privacy-first era". IDC specifically recognizes two core strengths: access controls from heritage of data sharing providing granular role-based access control at table and column level, and neutral and agnostic platform allowing customers to use identity partners of their choice.
7. Customers
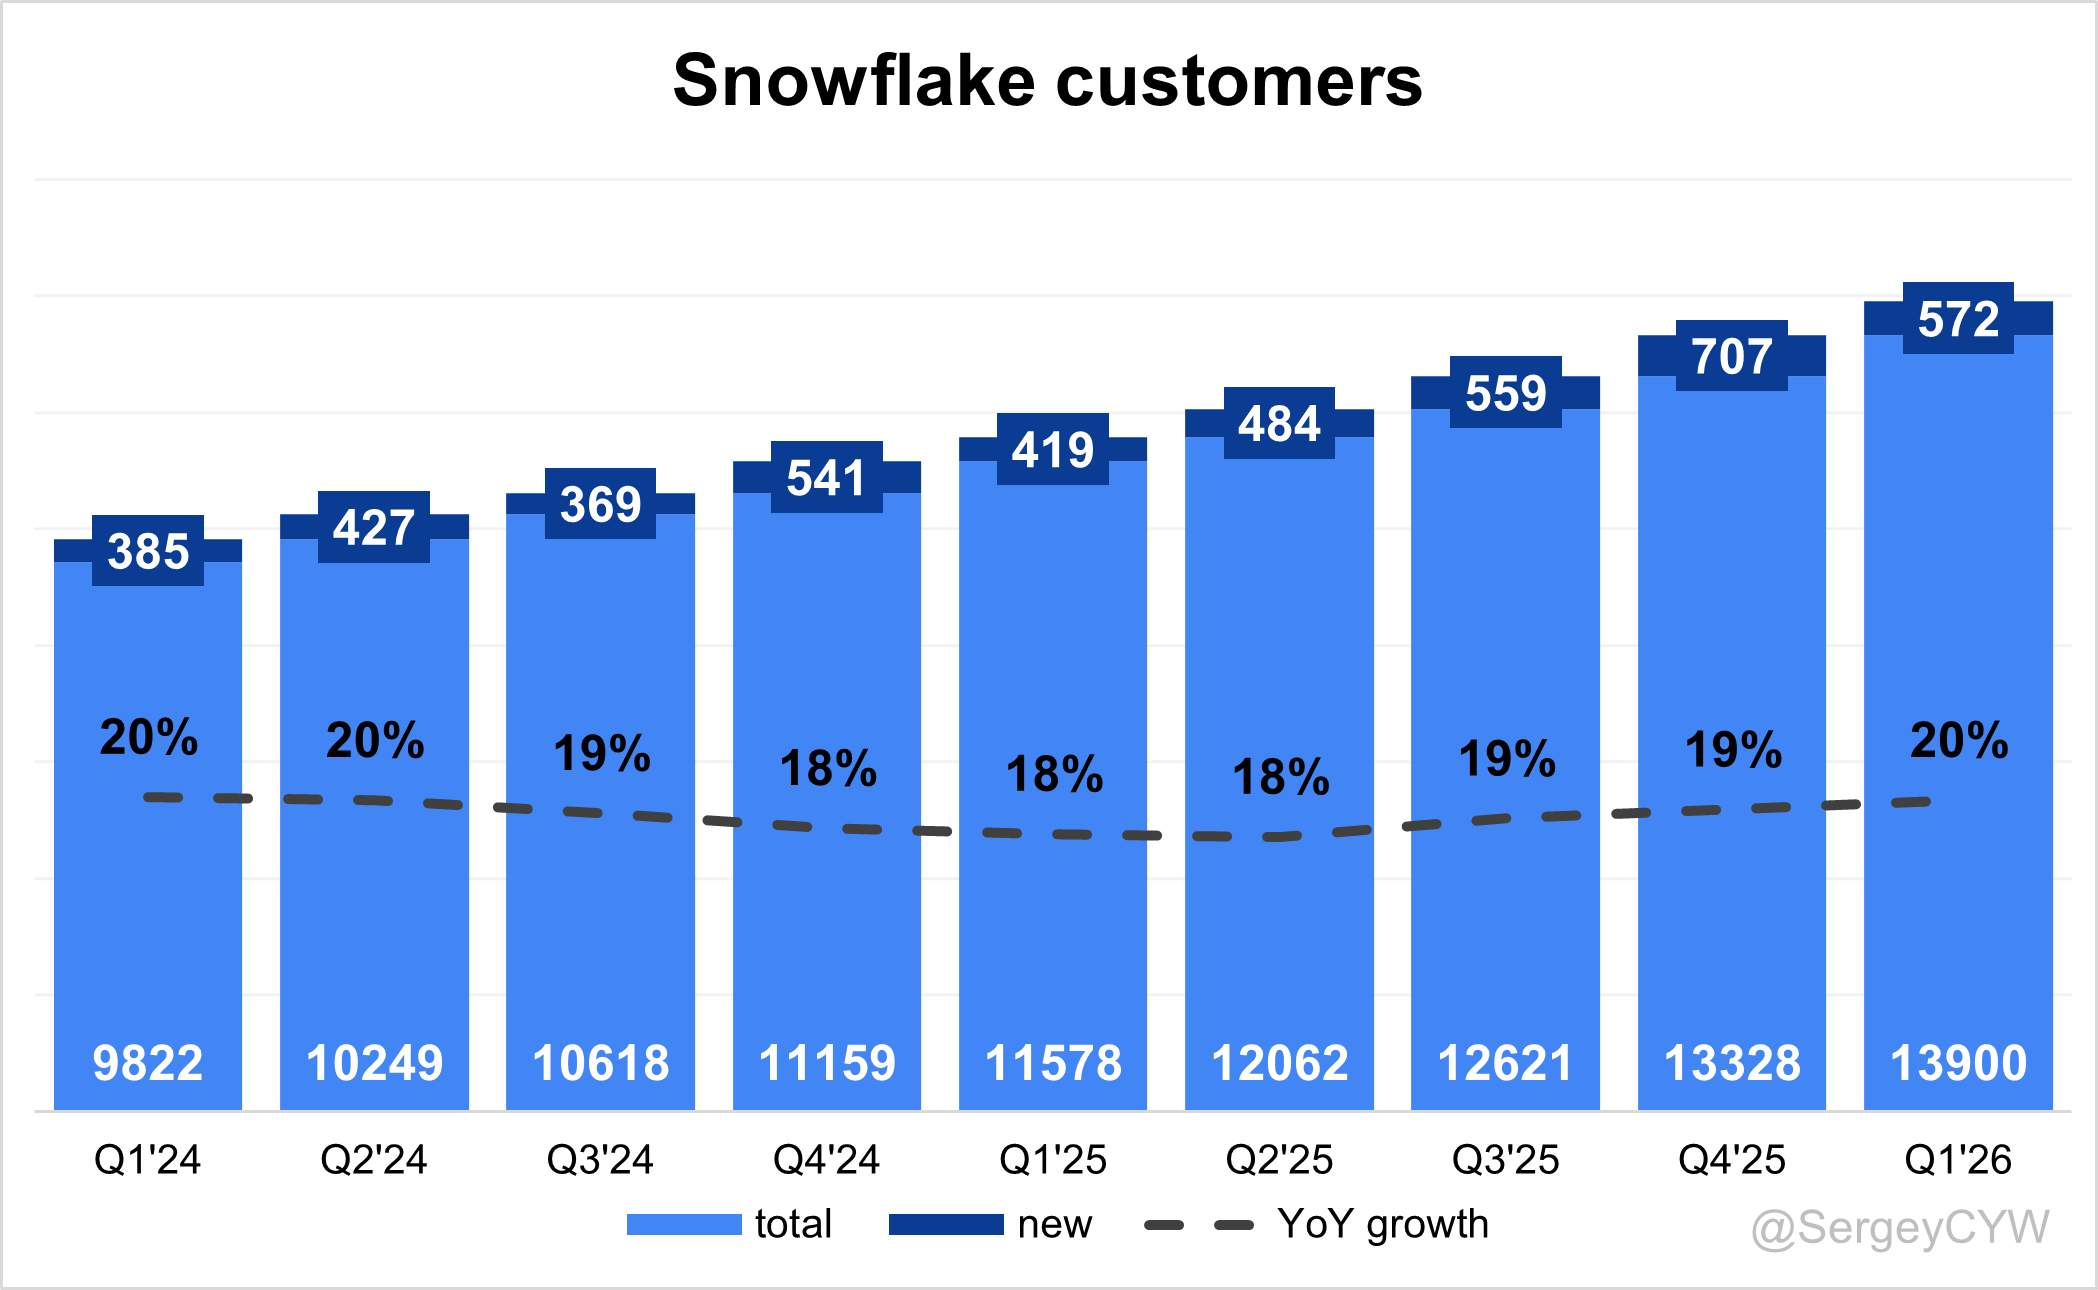
SNOW added 572 total customers, representing +18% YoY growth, a record level of new customer additions for a first quarter.
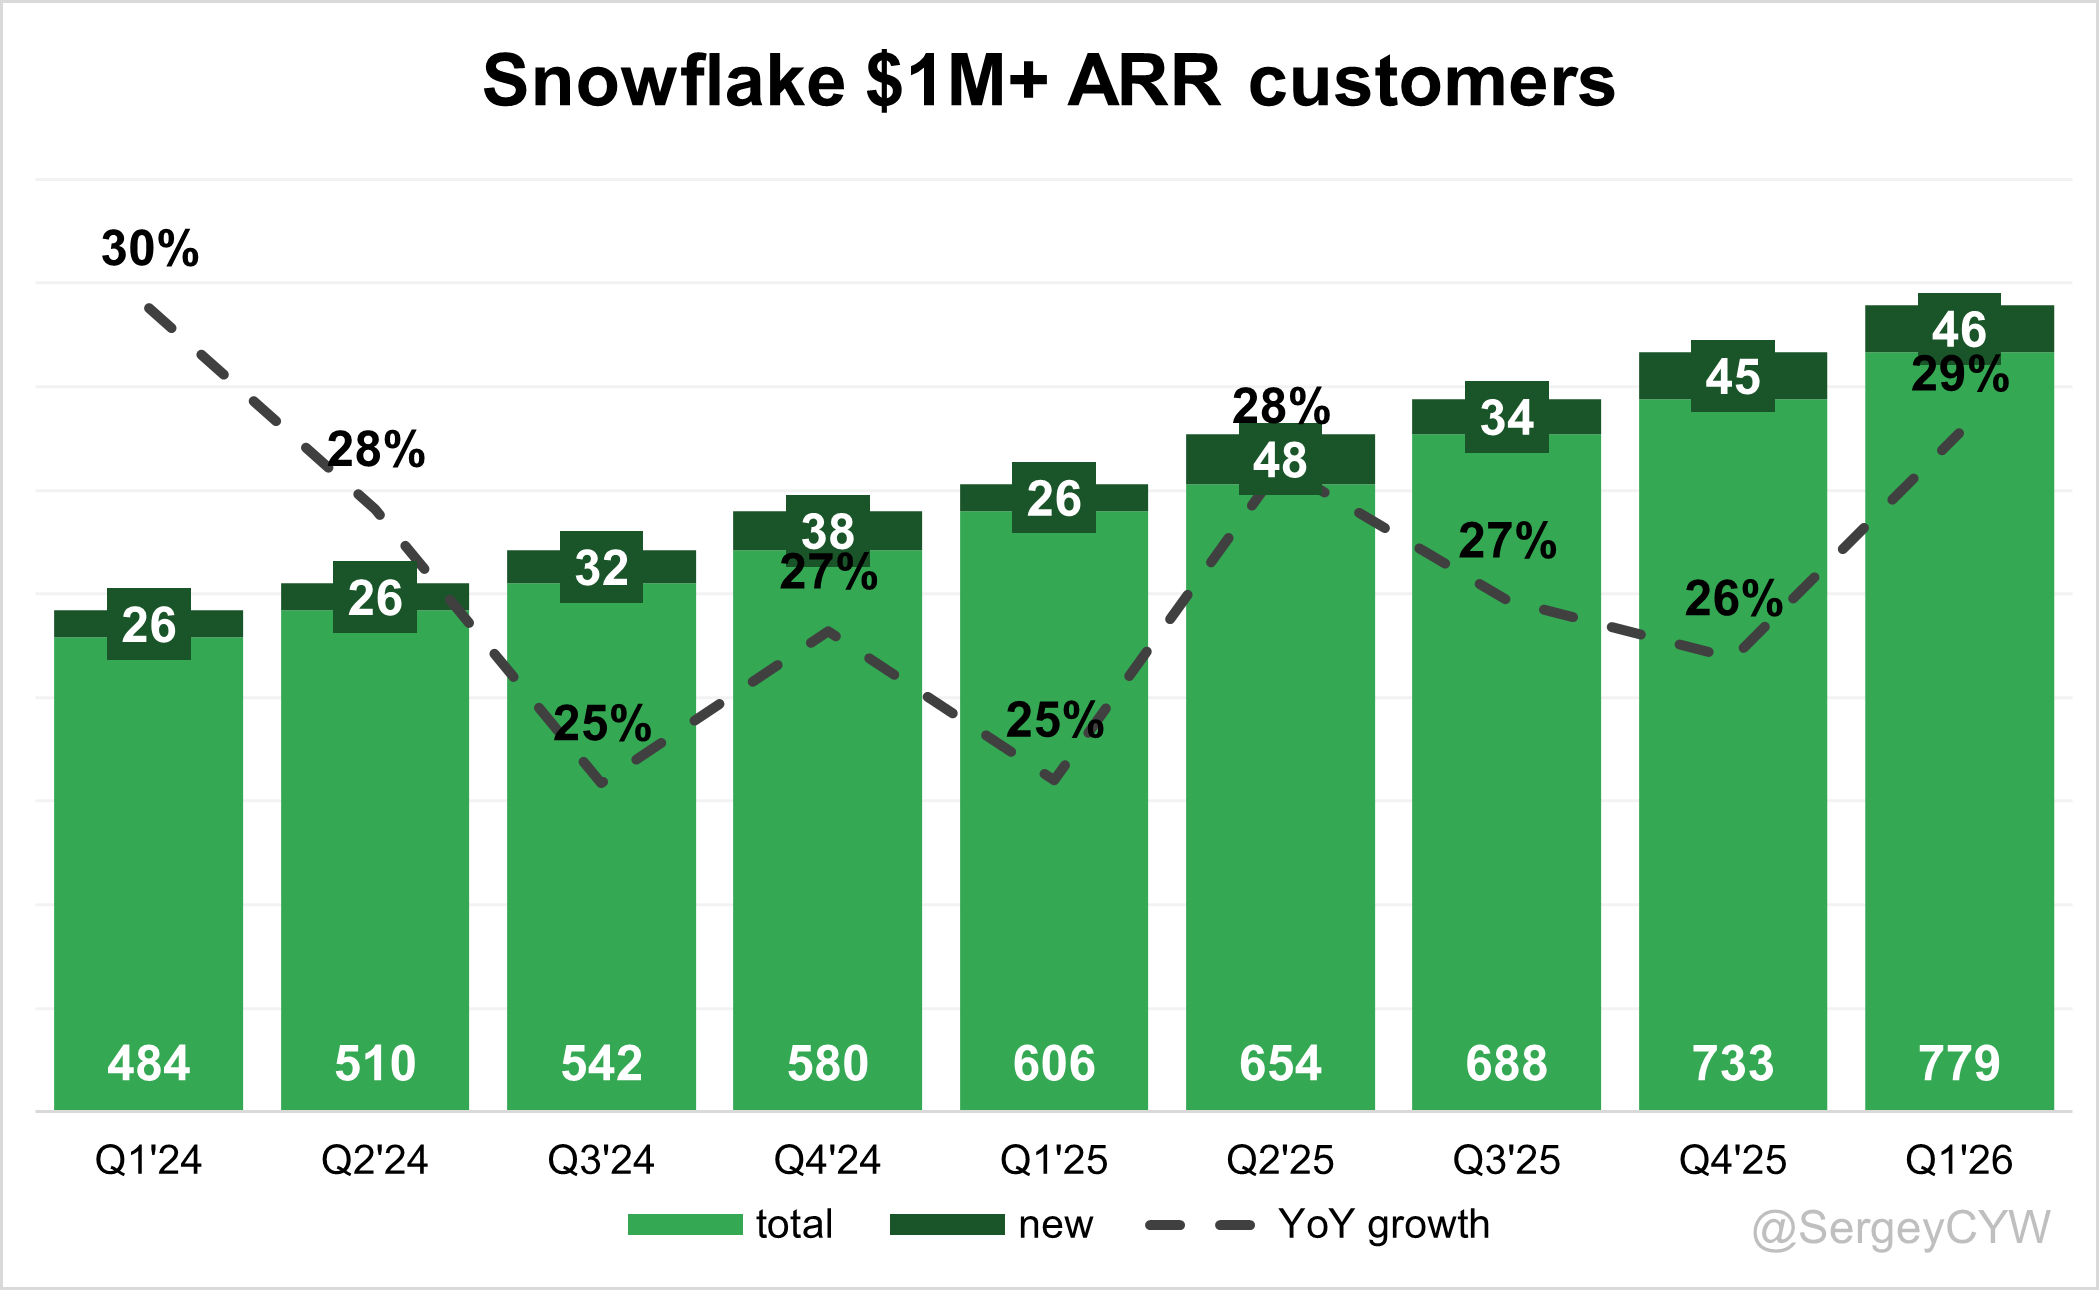
Snowflake also added 46 large customers with $1 million+ ARR, with growth in that segment accelerating to +29% YoY. This was also a record level of large customer additions for a first quarter.
Customer Success Stories
Snowflake’s AI products are moving from demos into measurable business impact. A Global 2000 hospitality customer completed a Spark migration 60%+ faster using CoCo with Snowflake services. A financial services firm saved 500+ hours through CoCo-driven automation.
A semiconductor customer first deployed CoCo to optimize queries and lower costs. Adoption then expanded into supply chain, where teams used CoCo to reduce manual inventory-ordering work. Management said the result was faster execution, better accuracy, and lower cost.
Named CoWork adoption included WHOOP, United Rentals, Domino’s Australia, and one of the largest banks. WHOOP is using CoCo and CoWork to reshape team operations. United Rentals and Domino’s Australia are cited as large analytics customers where CoWork has already delivered value.
Snowflake also uses itself as customer zero. CoCo is deployed across support, solution engineering, and services delivery. Support engineers are handling almost 25% more cases and resolving cases 25% faster. Inside the CFO organization, Snowflake has 139+ CoCo use cases, with work previously taking weeks now completed in minutes.
A large wealth management firm deployed the Cortex-powered Ask Your Data agent to its executive leadership team. More than 60% of business inquiries previously handled by analysts are now answered instantly.
Providence uses Snowflake Cortex to surface insights from clinical notes and patient records in seconds. CoCo helps build workflows directly inside Snowflake while maintaining privacy standards.
Thomson Reuters uses Cortex and CoCo for AI-driven legal and compliance workflows. The goal is to turn complex regulatory data into actionable insights in seconds while maintaining governance and reliability.
Infinite Lambda used CoCo to build a customer 360 application in five hours, showing how CoCo can improve partner productivity and shorten sales cycles.
Large Customer Wins
Large-customer monetization remains a major expansion lever. Eight customers surpassed $10M in trailing twelve-month revenue, bringing total customers above $10M to 64.
Snowflake’s top 25 customers now spend an average of $34M per year, up from $22M over the past two years. Fortune 2000 customers spend only $2.4M on average in FY2026, leaving a meaningful expansion gap.
Holiday Inn Club Vacations selected Snowflake for data and AI modernization, citing simplicity, built-in AI and machine-learning capabilities, and partnership strength. Houzz selected Snowflake to support its next growth phase, aiming for better data processing performance, lower pipeline maintenance, and more engineering capacity for new products.
Houzz also plans to invest in natural-language query processing and self-serve analytics. A large U.S. bank completed one of the most complex data warehouse migrations in financial services, moving from Teradata to Snowflake after nearly two years.
The bank now plans more legacy migrations and is building AI-powered regulatory intelligence, natural-language analytics, and data discovery on Snowflake.
Nestlé is expanding Snowflake across enterprise digital transformation. The company operates more than 2,000 brands in 185 countries and is building data products used by more than 50,000 users across 150 global capabilities.
Global Payments, DTCC, and Blue Yonder expanded Snowflake usage to support larger workloads, AI-powered insights, and customer value.
New customer momentum improved materially. Management called the latest quarter “remarkable,” with both new logos and ACV from new logos increasing significantly year over year.
Customer ramp is improving. New customers are moving to consumption faster, with time to consume reduced from 10 months to 7 months. Overall migrations improved by 40%, migrations grew 1.9x from FY2025 to FY2026, and use cases grew 1.7x.
AI is changing the buyer profile. Snowflake is increasingly selling to CFOs, not only chief data officers. Brian Robins met with 20+ CFOs in London and highlighted large renewal discussions where a CFO at a $10B company became the lead buyer.
Customer executive center meetings now often include full management teams, boards, and partner groups. Buying urgency is rising as enterprises move from AI strategy to deployment.
8. KPI
Retention
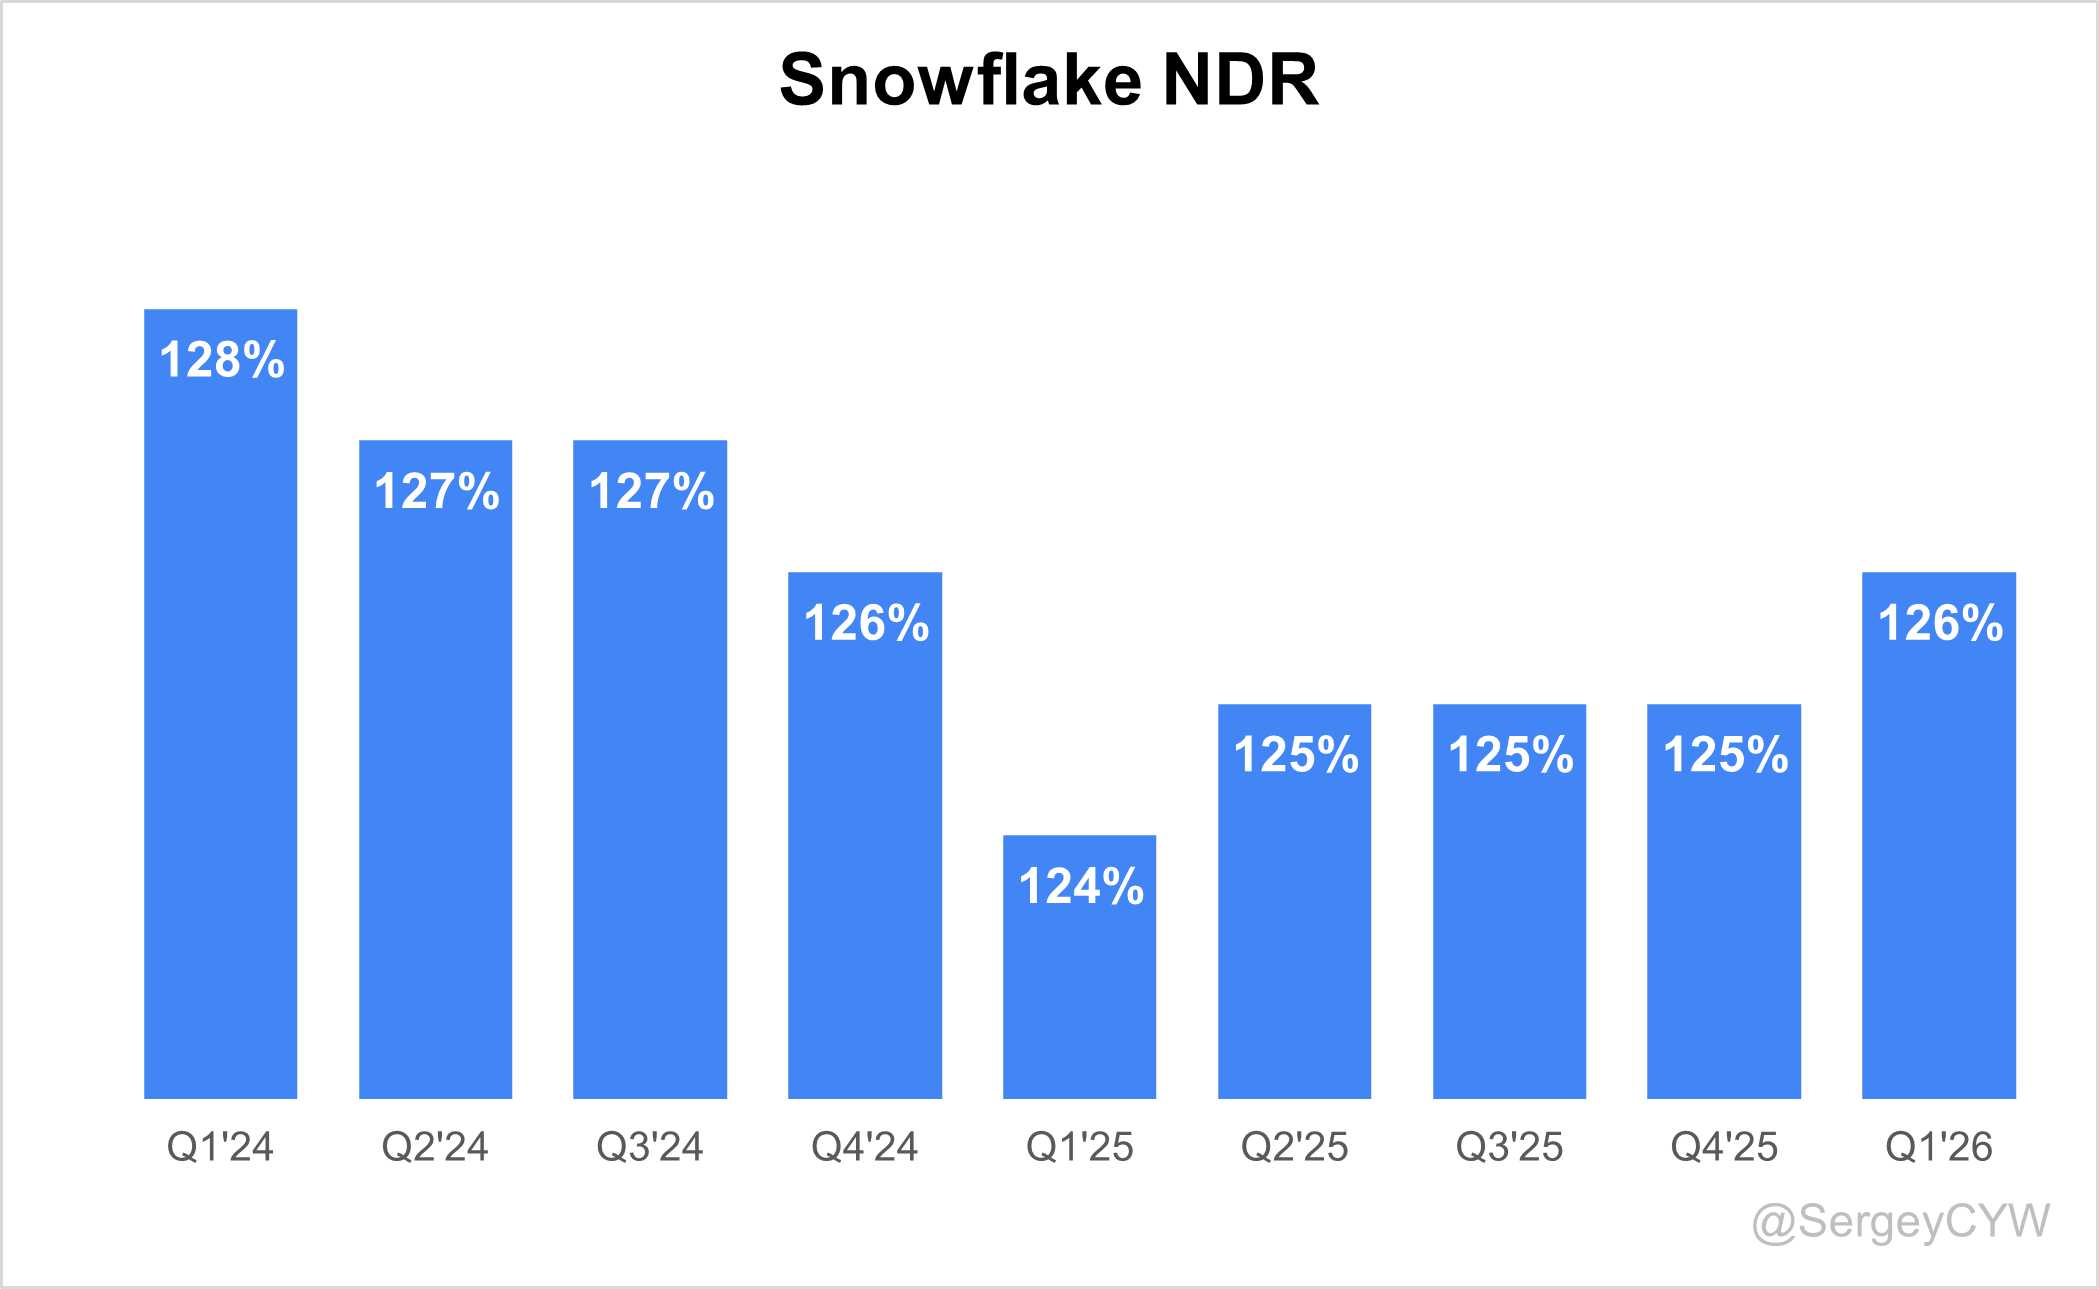
SNOW’s retention rate remains one of the highest in its class and increased to 126% in Q1 2026, up 1 percentage point QoQ and well above the 118% median DBNRR for the SaaS companies I track.
It is also worth noting that Snowflake calculates this metric using data from the past two years, which makes it a relatively lagging indicator for the company compared to many other SaaS businesses.
Net new ARR
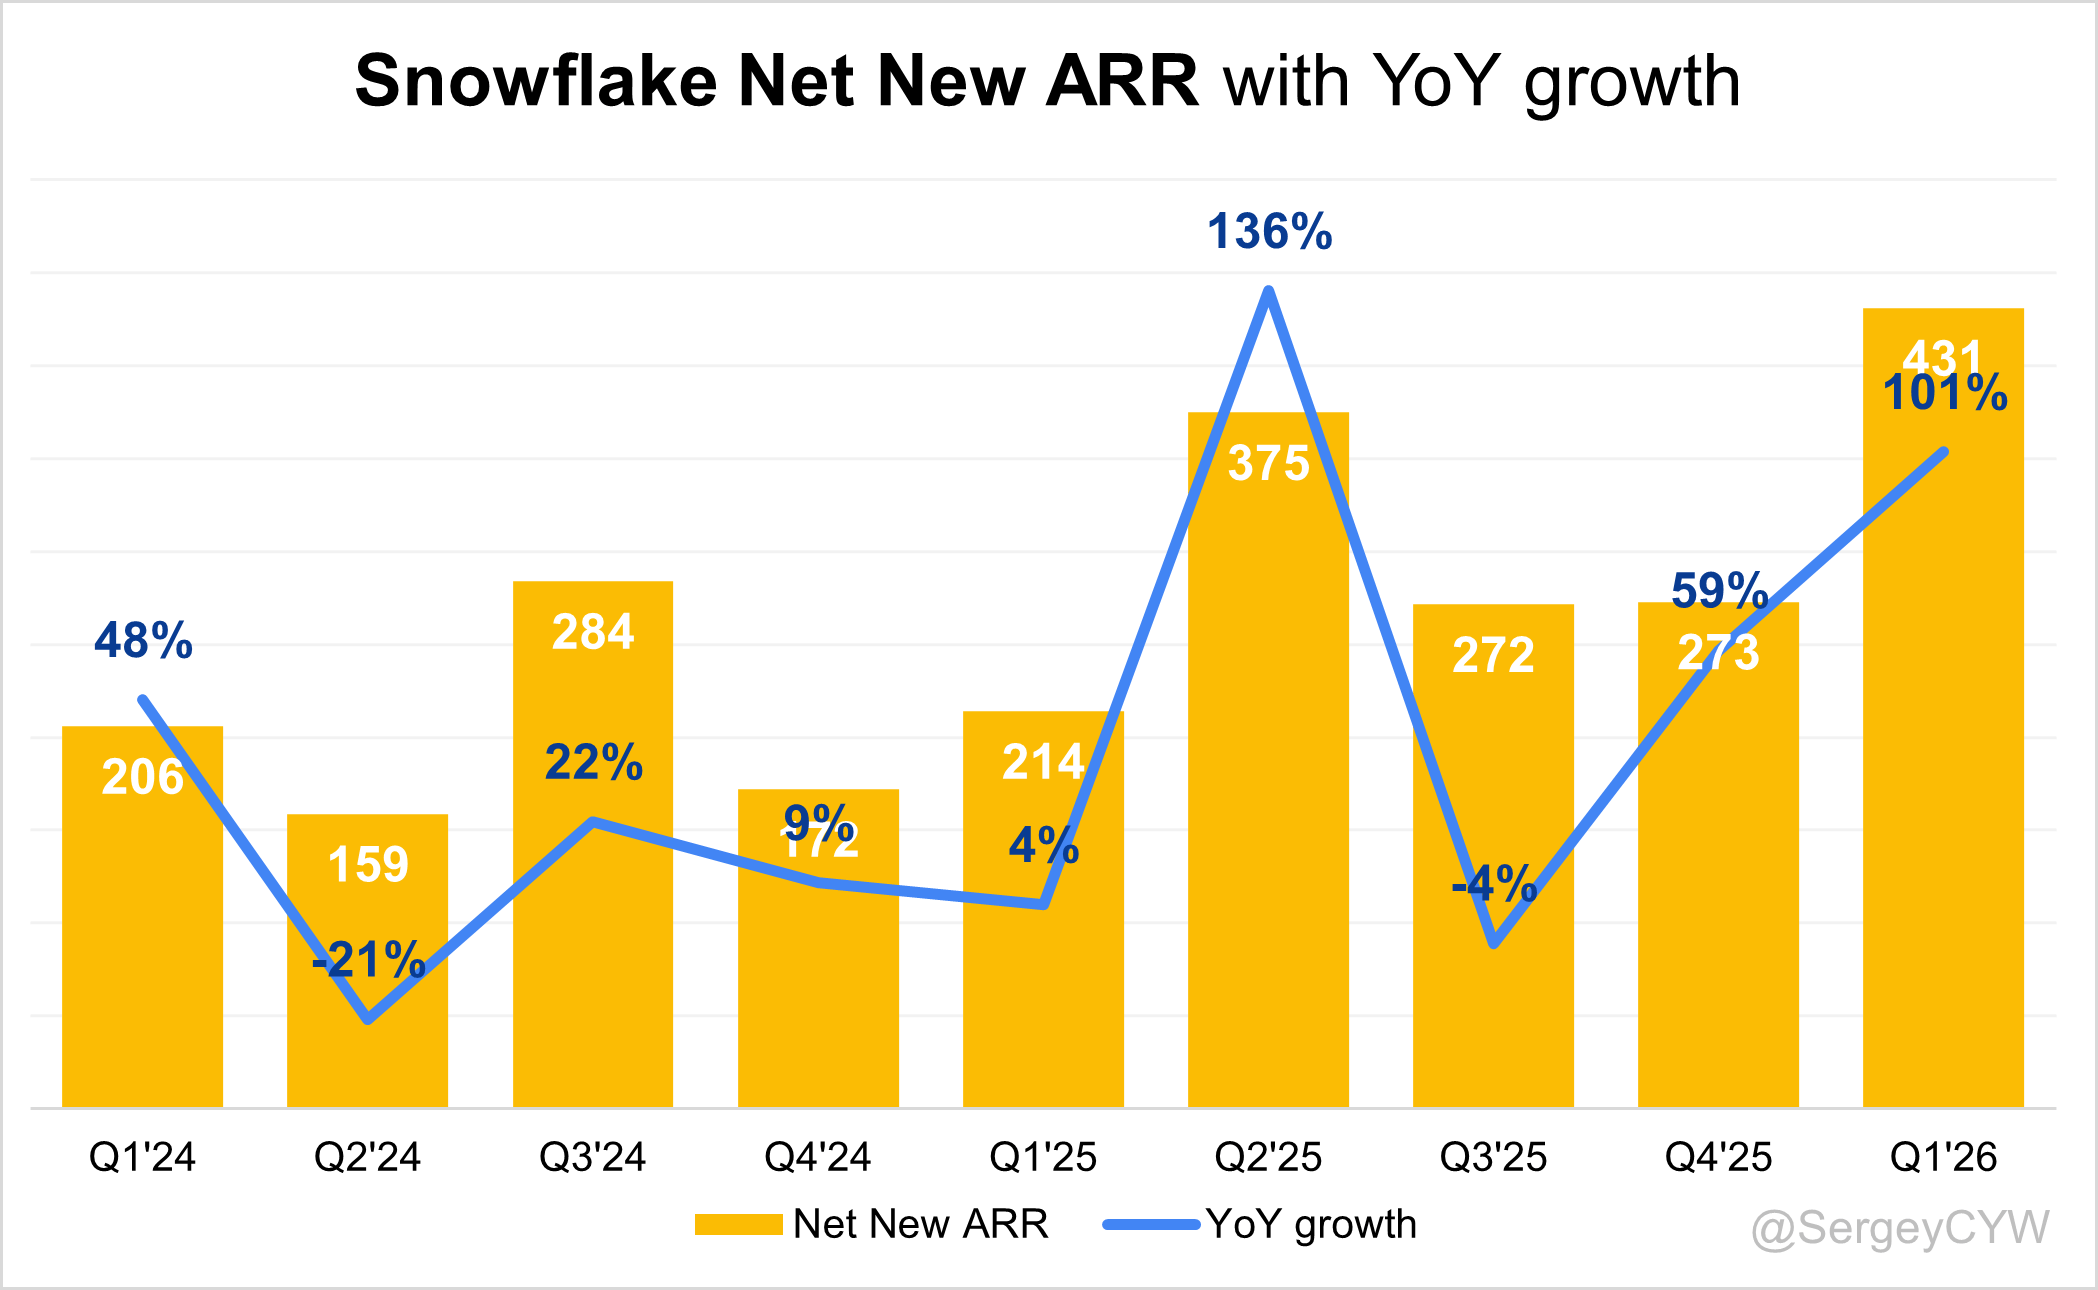
SNOW added $431 million in net new ARR, representing +101% YoY growth. This was a record level of net new ARR addition in the company's history.
CAC Payback Period and RDI Score
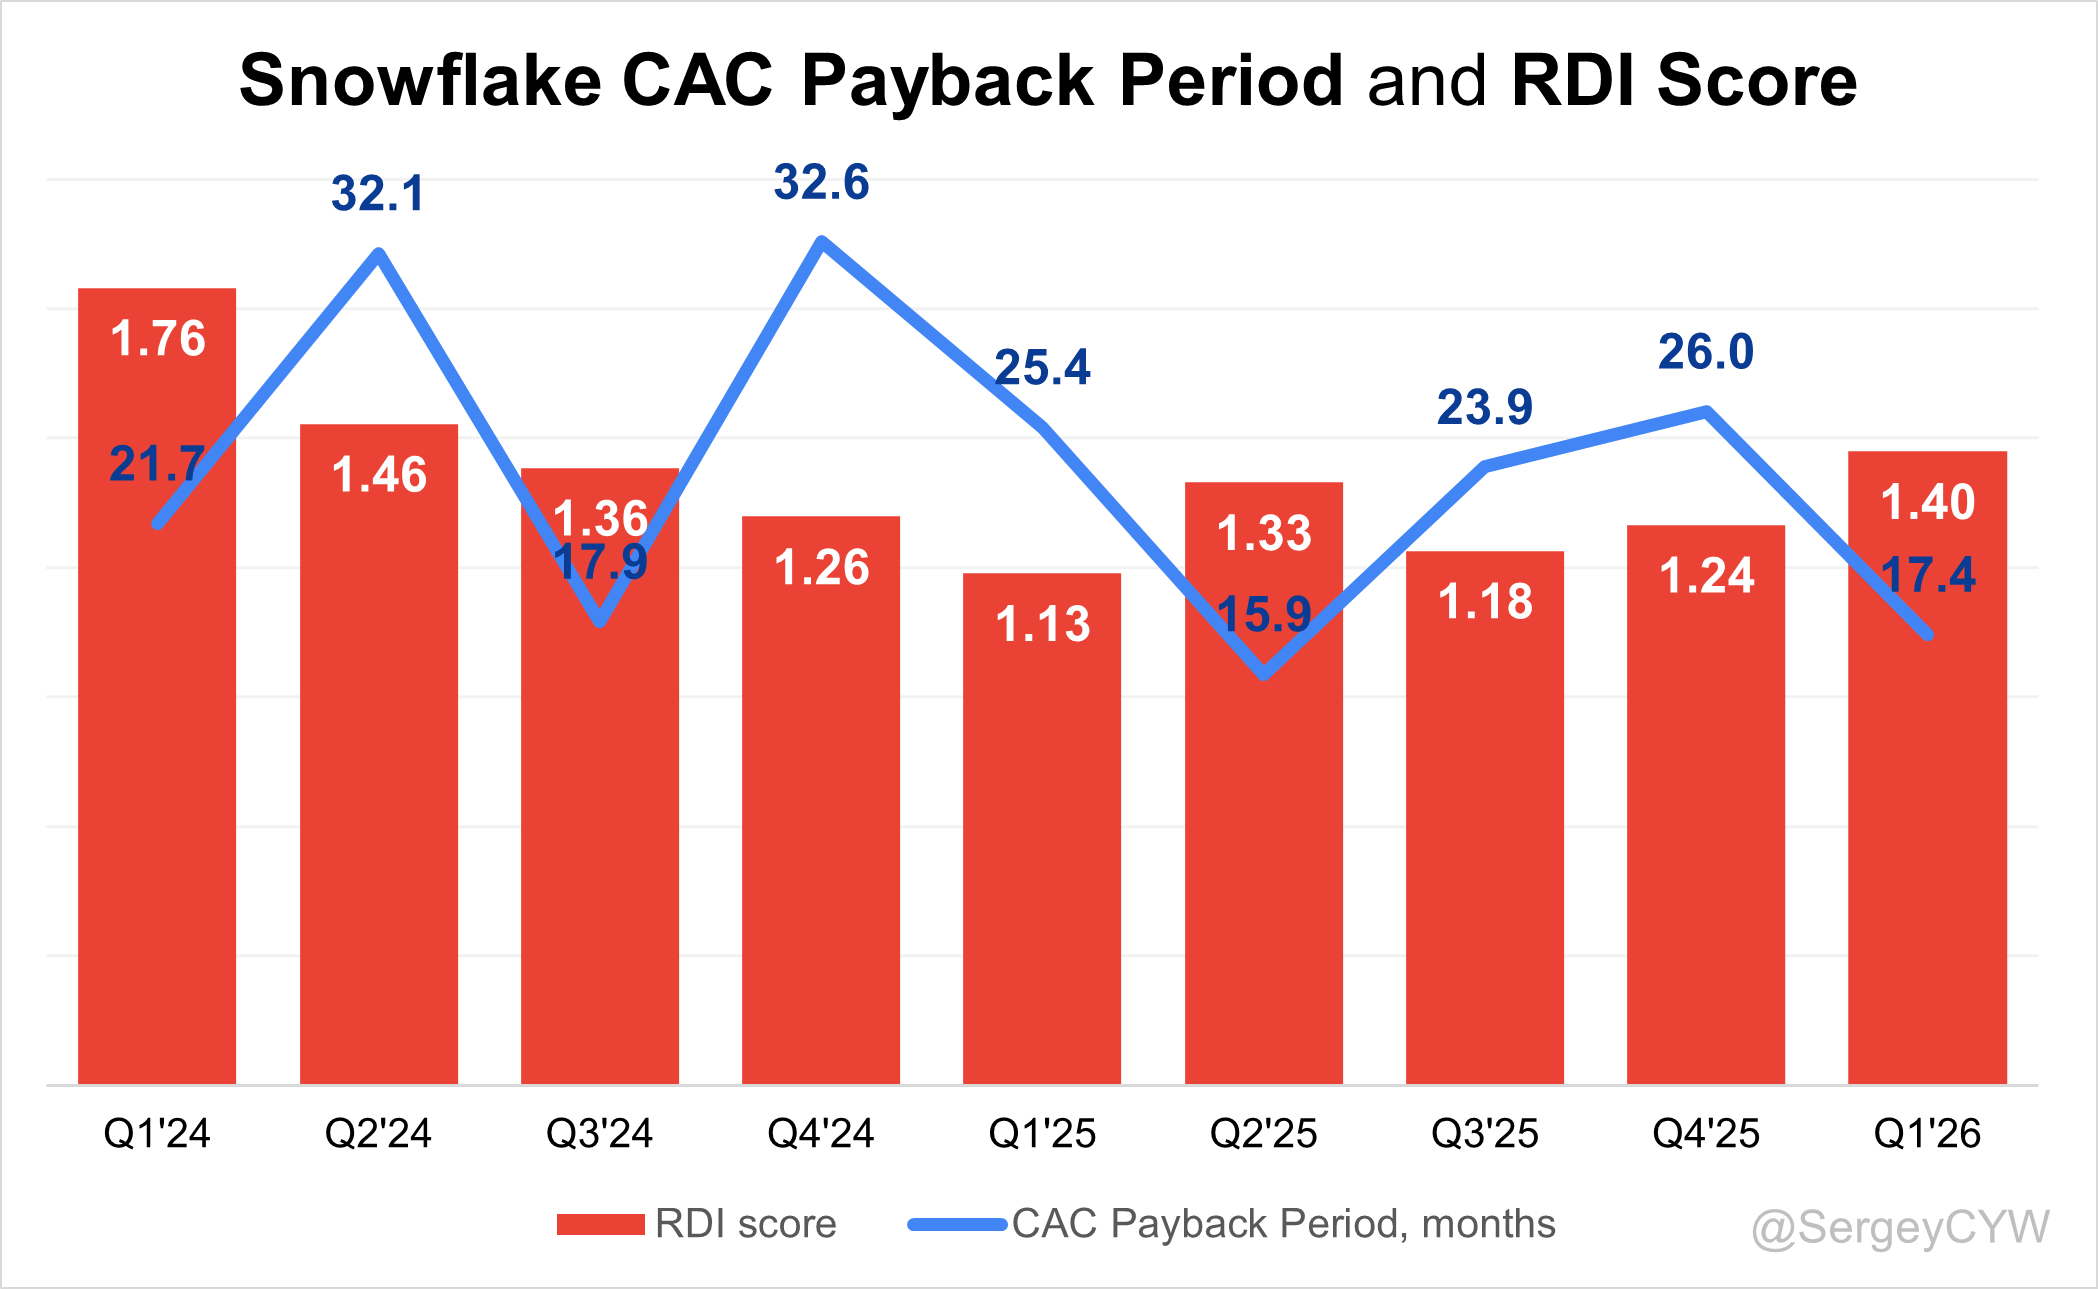
SNOW Snowflake’s return on S&M spending is 17.4 months, a significant improvement compared to the previous quarter and meaningfully better than the 22.9-month median for the SaaS companies I track.
Snowflake isn’t a pure SaaS company—it operates on a consumption-based model, which makes metrics such as CAC Payback Period and net new ARR more volatile than those of traditional subscription-based SaaS businesses.
The R&D Index (RDI Score) for Q1 came in at 1.40, in line with the 1.4 median for the SaaS companies I track. This remains a strong result and is well above the industry median of 0.7.
Snowflake has increased its R&D spending, which has temporarily lowered its RDI Score. However, this is expected, as the benefits of those investments should be reflected in future revenue growth and product innovation.
An RDI Score above 1.4 is considered best-in-class, while the industry median of 0.7 highlights the importance of efficient R&D investment.
Two key components of SNOW Snowflake’s economic moat are high switching costs and strong network effects.
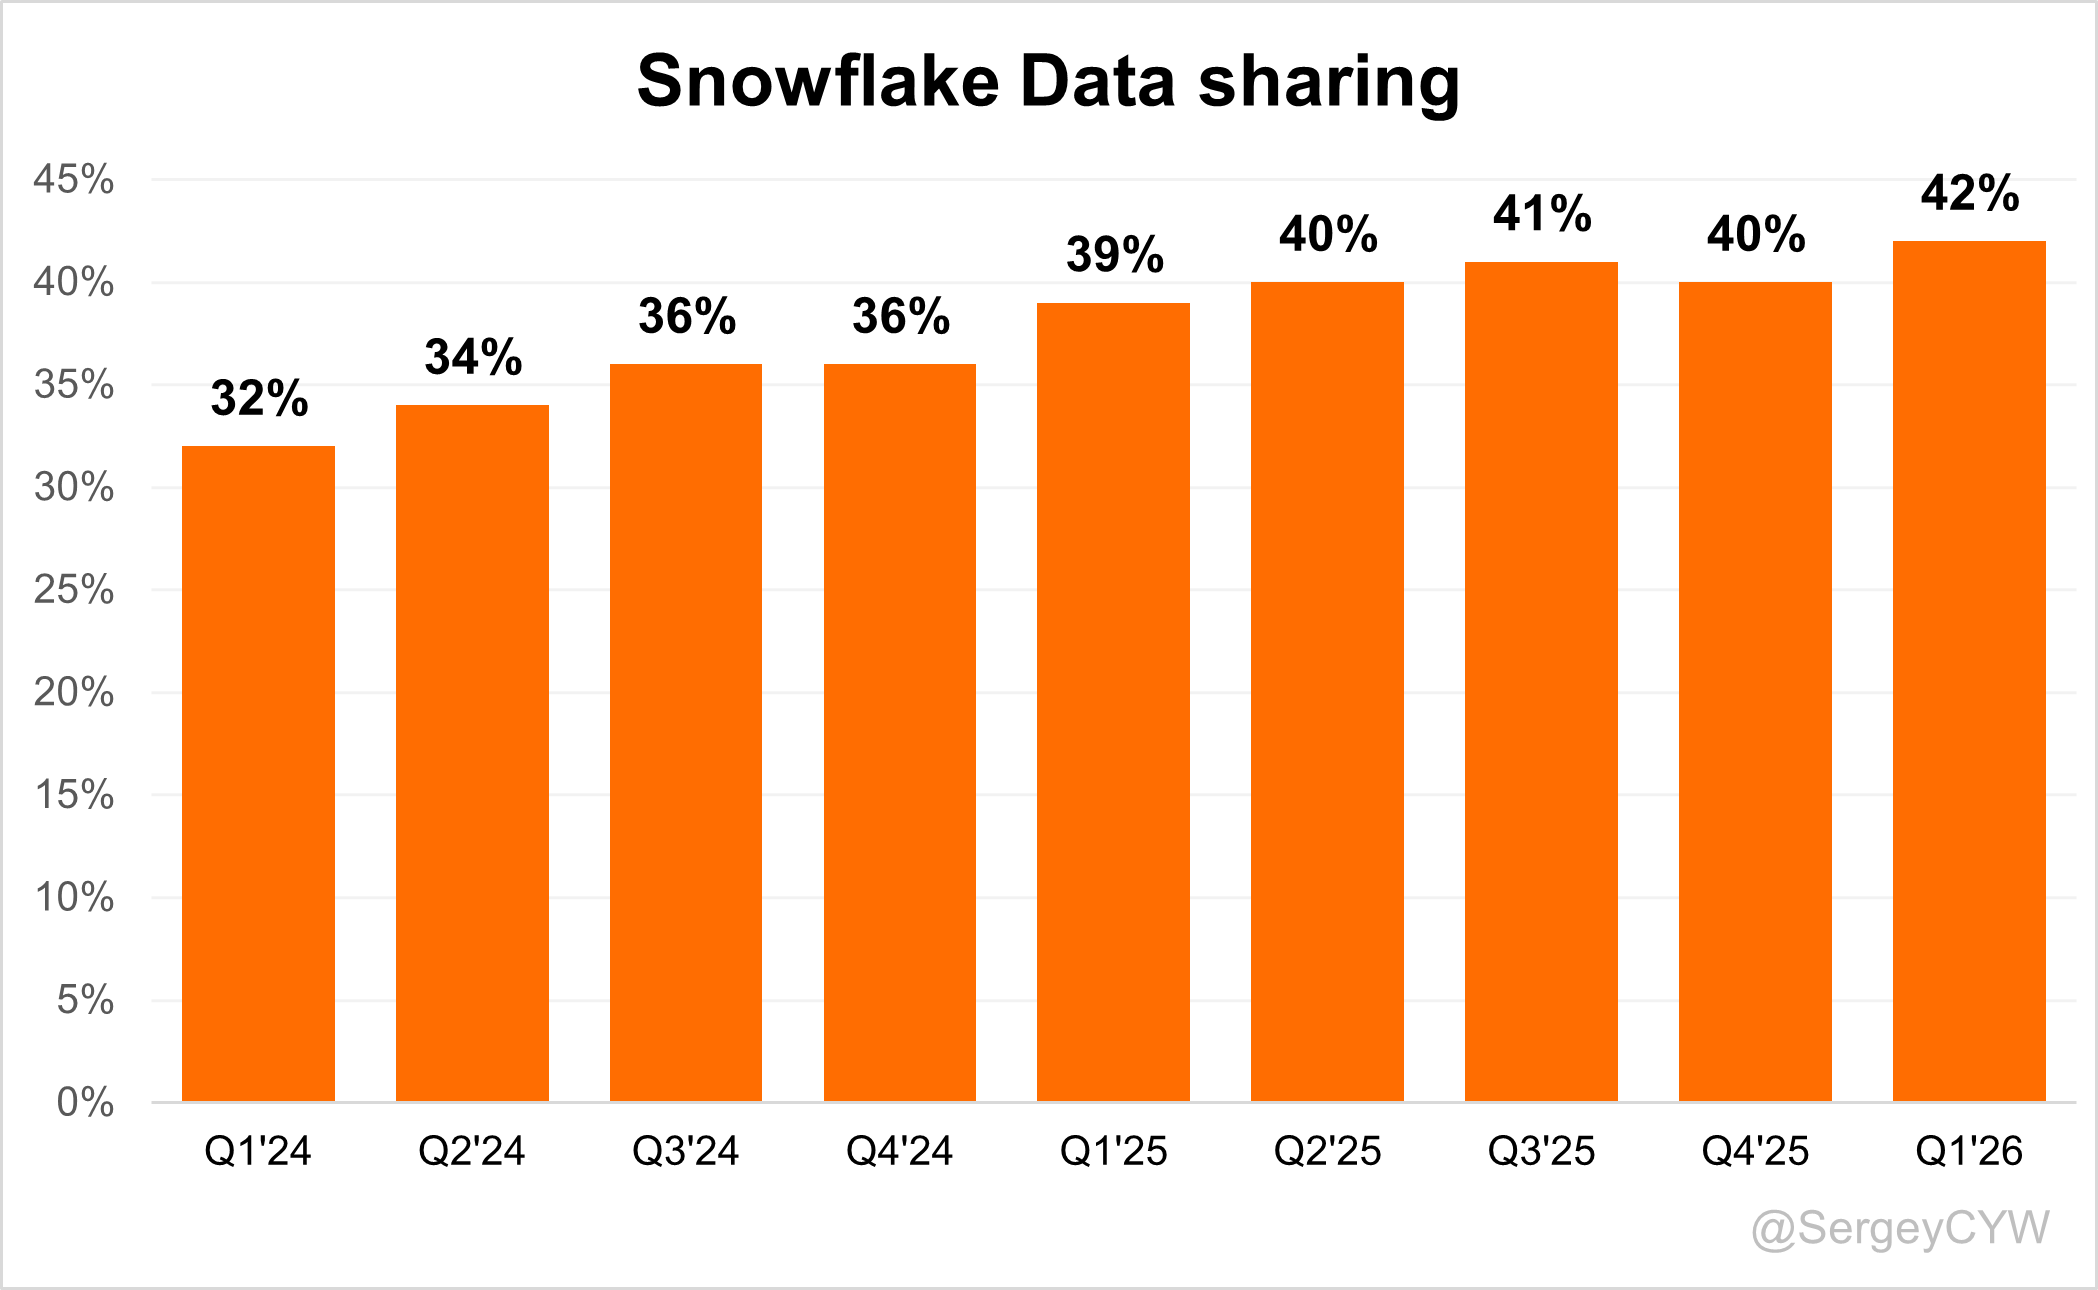
Data sharing has steadily grown from 32% two years ago to 42% in Q1 2026, reflecting sustained engagement.
This metric is crucial in highlighting Snowflake’s network effect, as higher data sharing enhances platform utility, attracting more customers and reinforcing Snowflake’s competitive edge.
Data sharing remains Snowflake’s structural moat.
Dentsu and CloudZero use live data connections to collaborate across networks and eliminate third-party tools. Snowflake’s Data Clean Room supports secure, privacy-preserving sharing—critical for industries like advertising and finance.
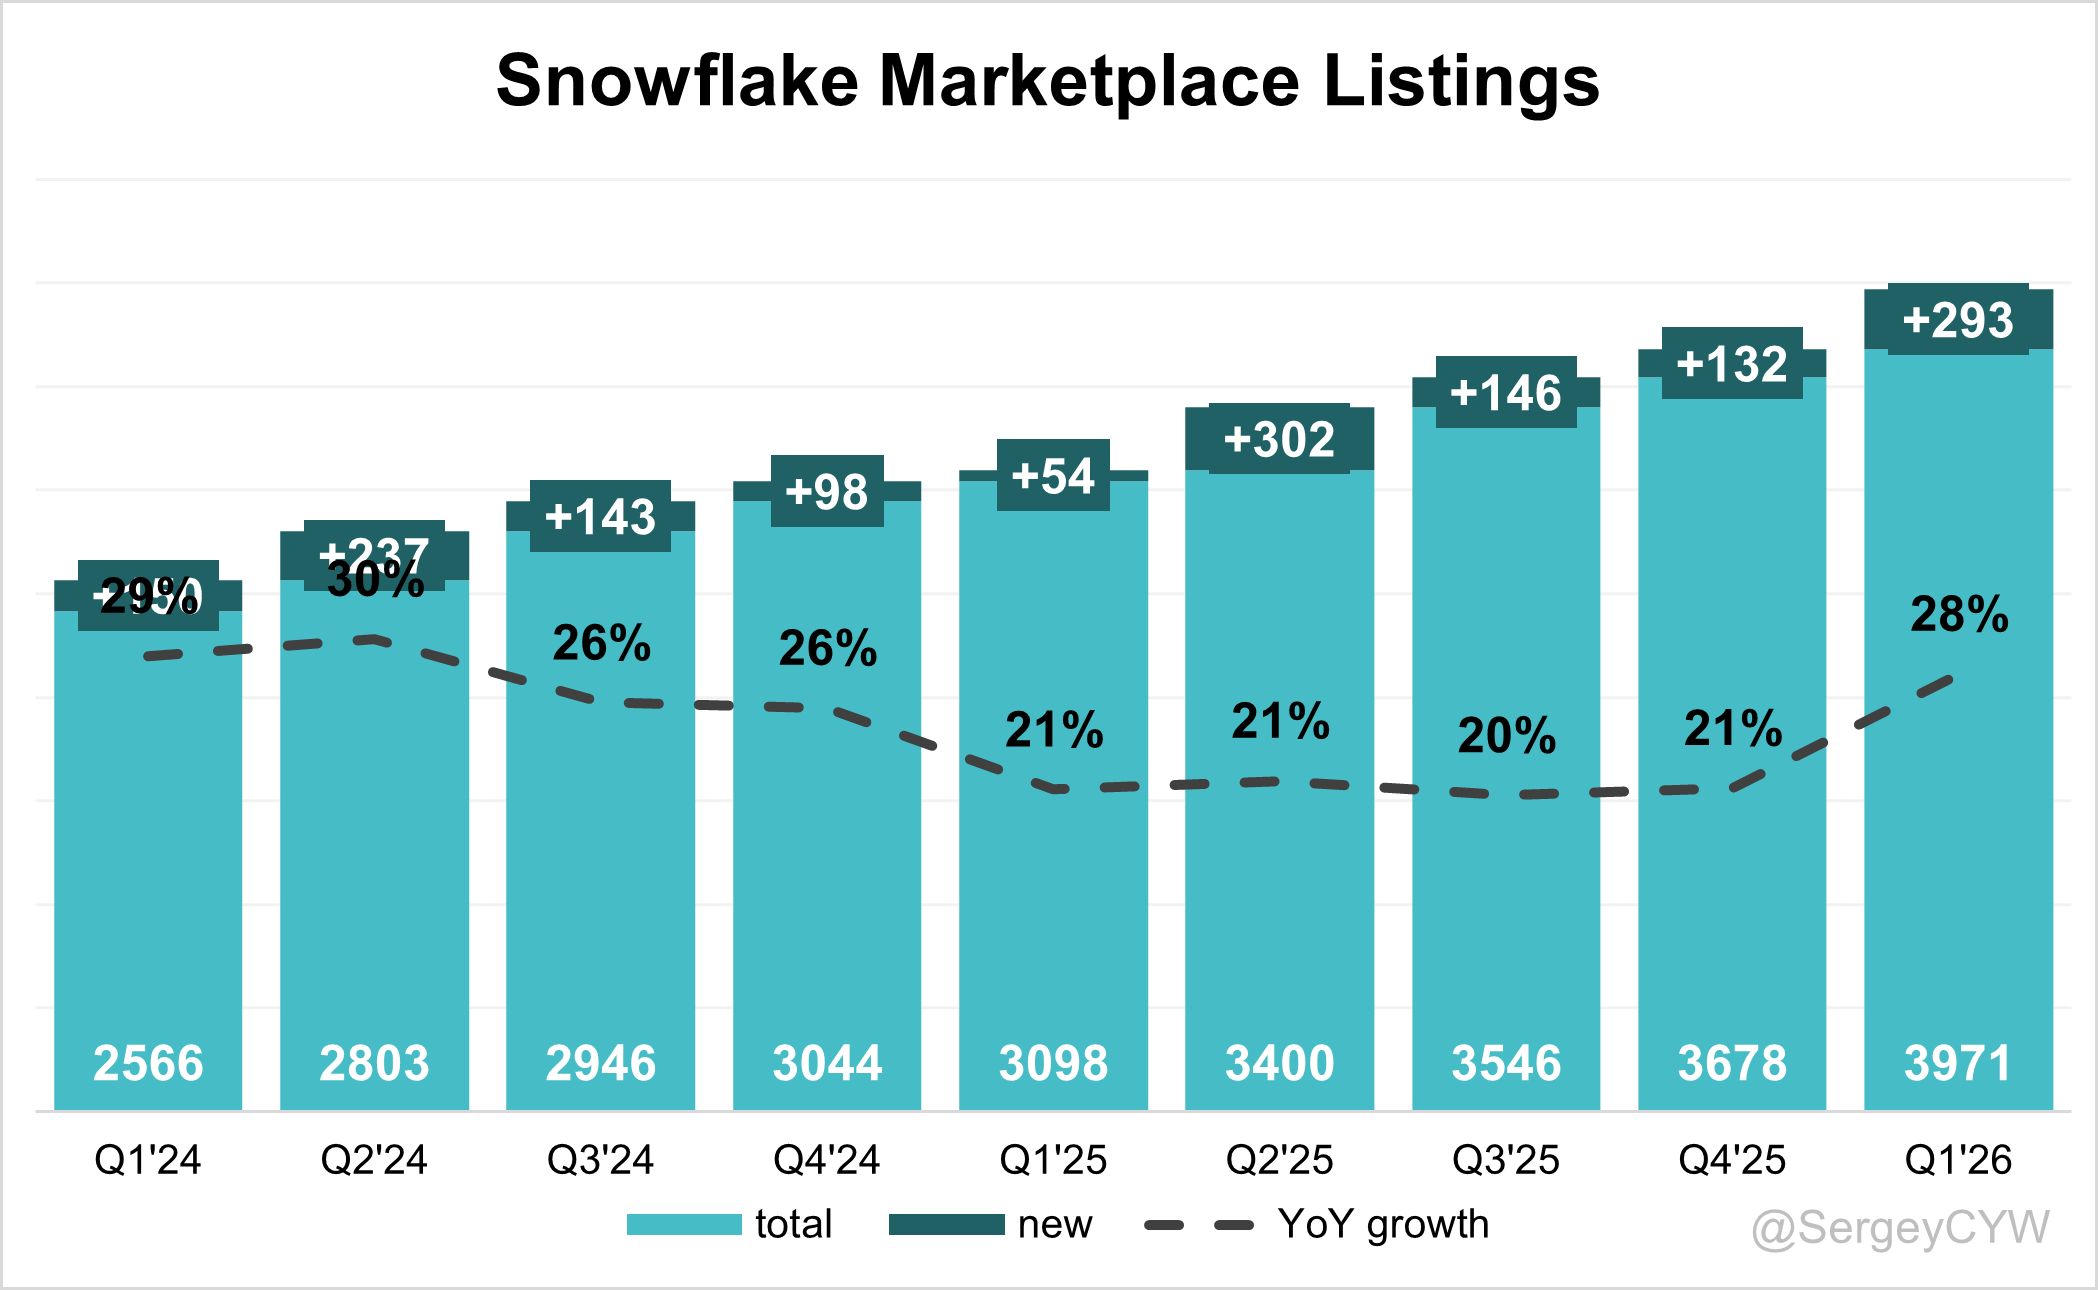
SNOW added 293 new listings to its Marketplace in Q1 2026, with growth accelerating to +28% YoY. After a weak Q1 2025, when only 54 new listings were added, this represents a record number of Marketplace additions for a first quarter in the company’s history.
This metric continues to reflect the strength of Snowflake’s expanding ecosystem and the growing traction of its data-sharing platform.
Profitability
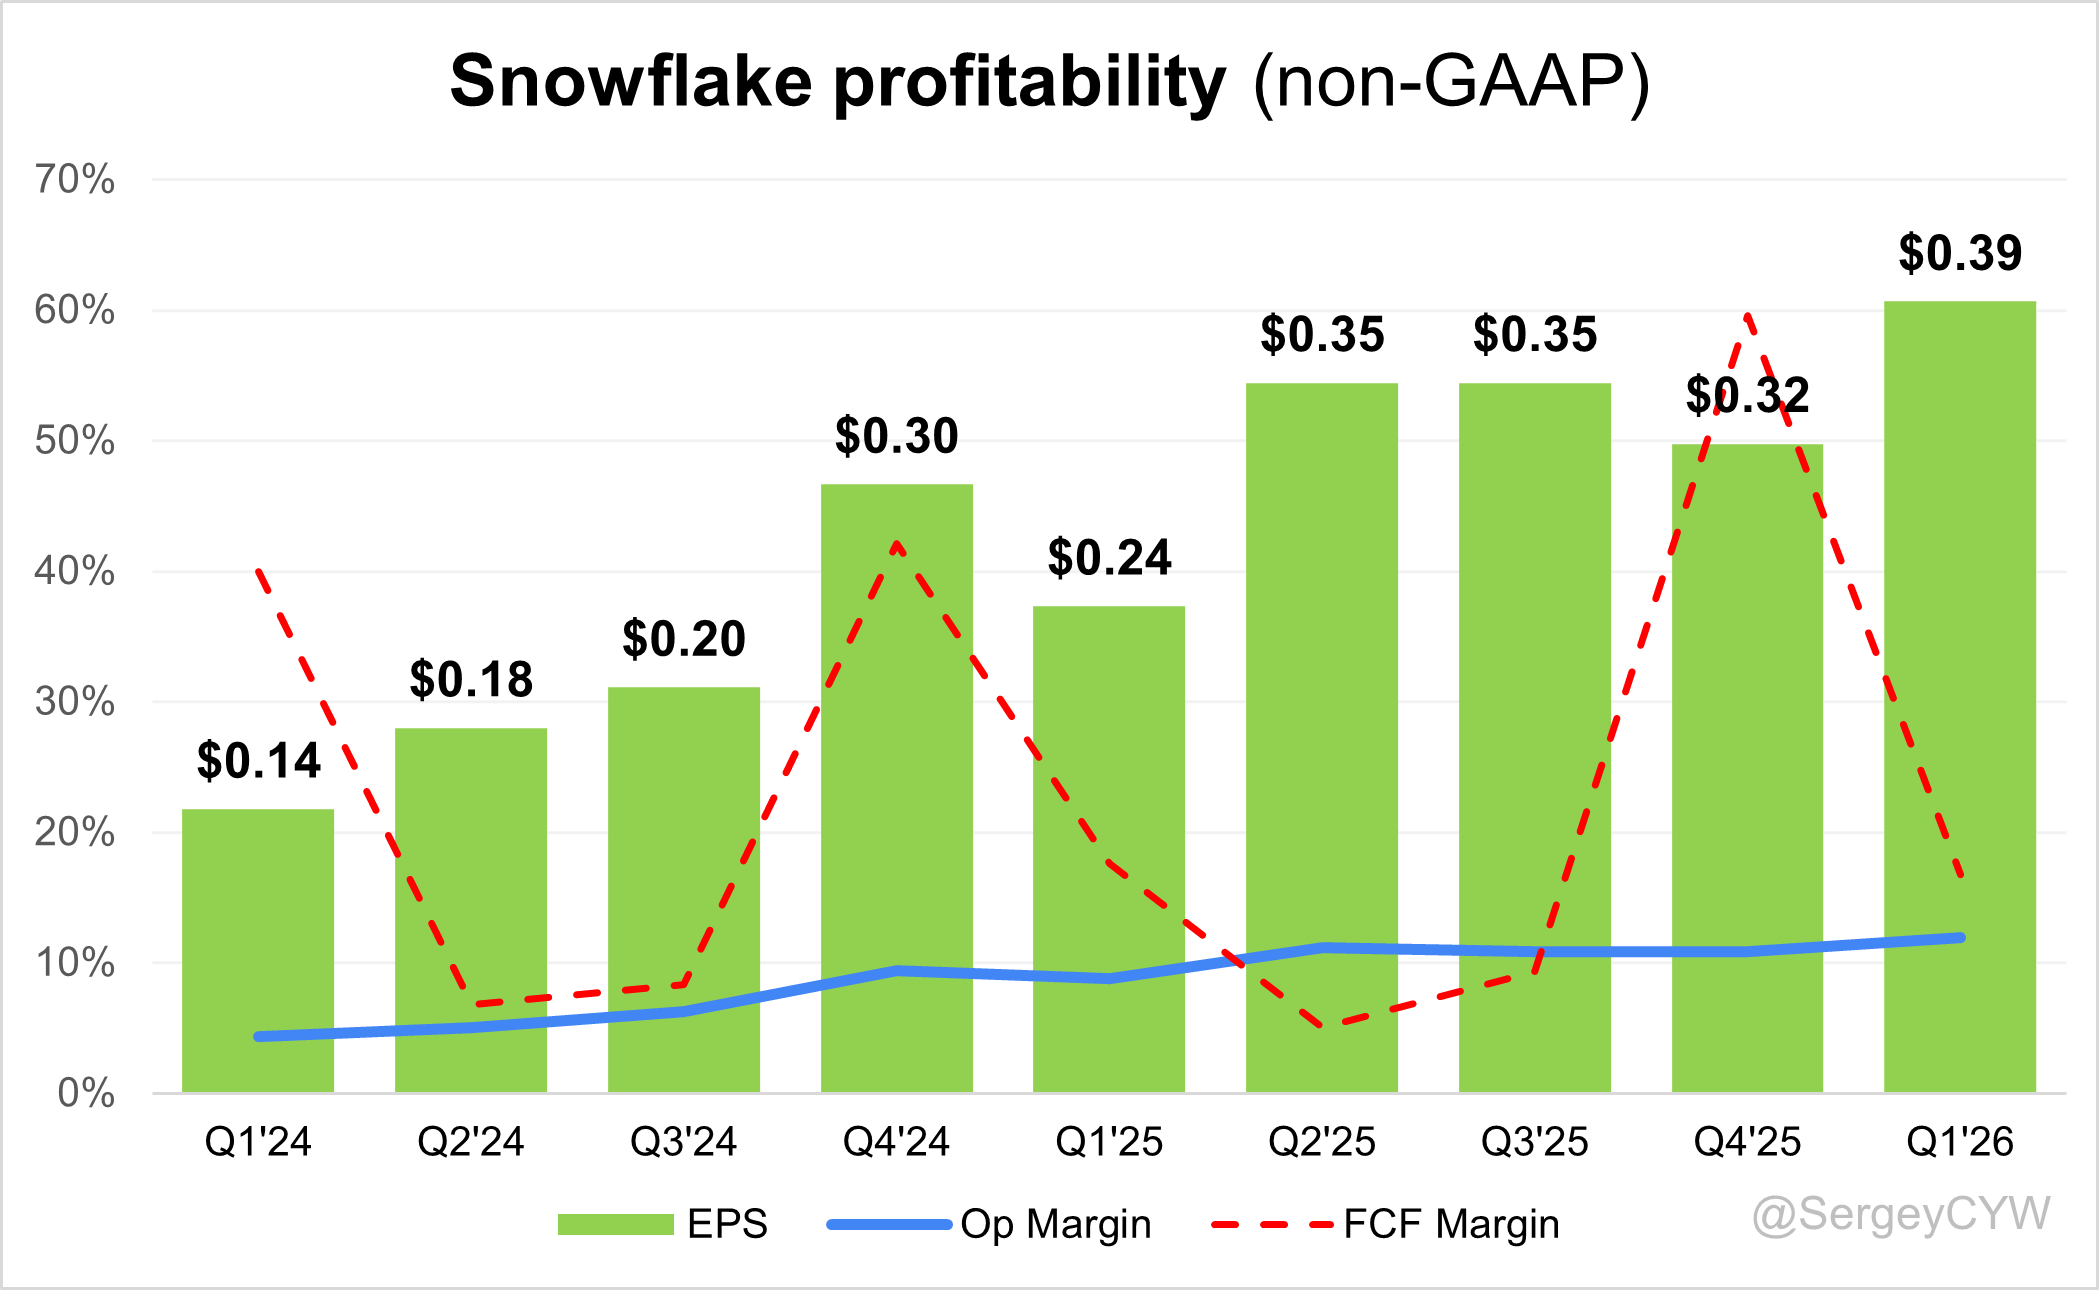
Over the past year, SNOW Snowflake’s margins have changed:
• Gross Margin slightly declined from 72.2% to 71.7%.
• Operating Margin increased from 8.8% to 11.9%.
• FCF Margin slightly declined from 17.6% to 16.7%.
Management guiding for GAAP profitability in 4Q FY2027.
Operating expenses
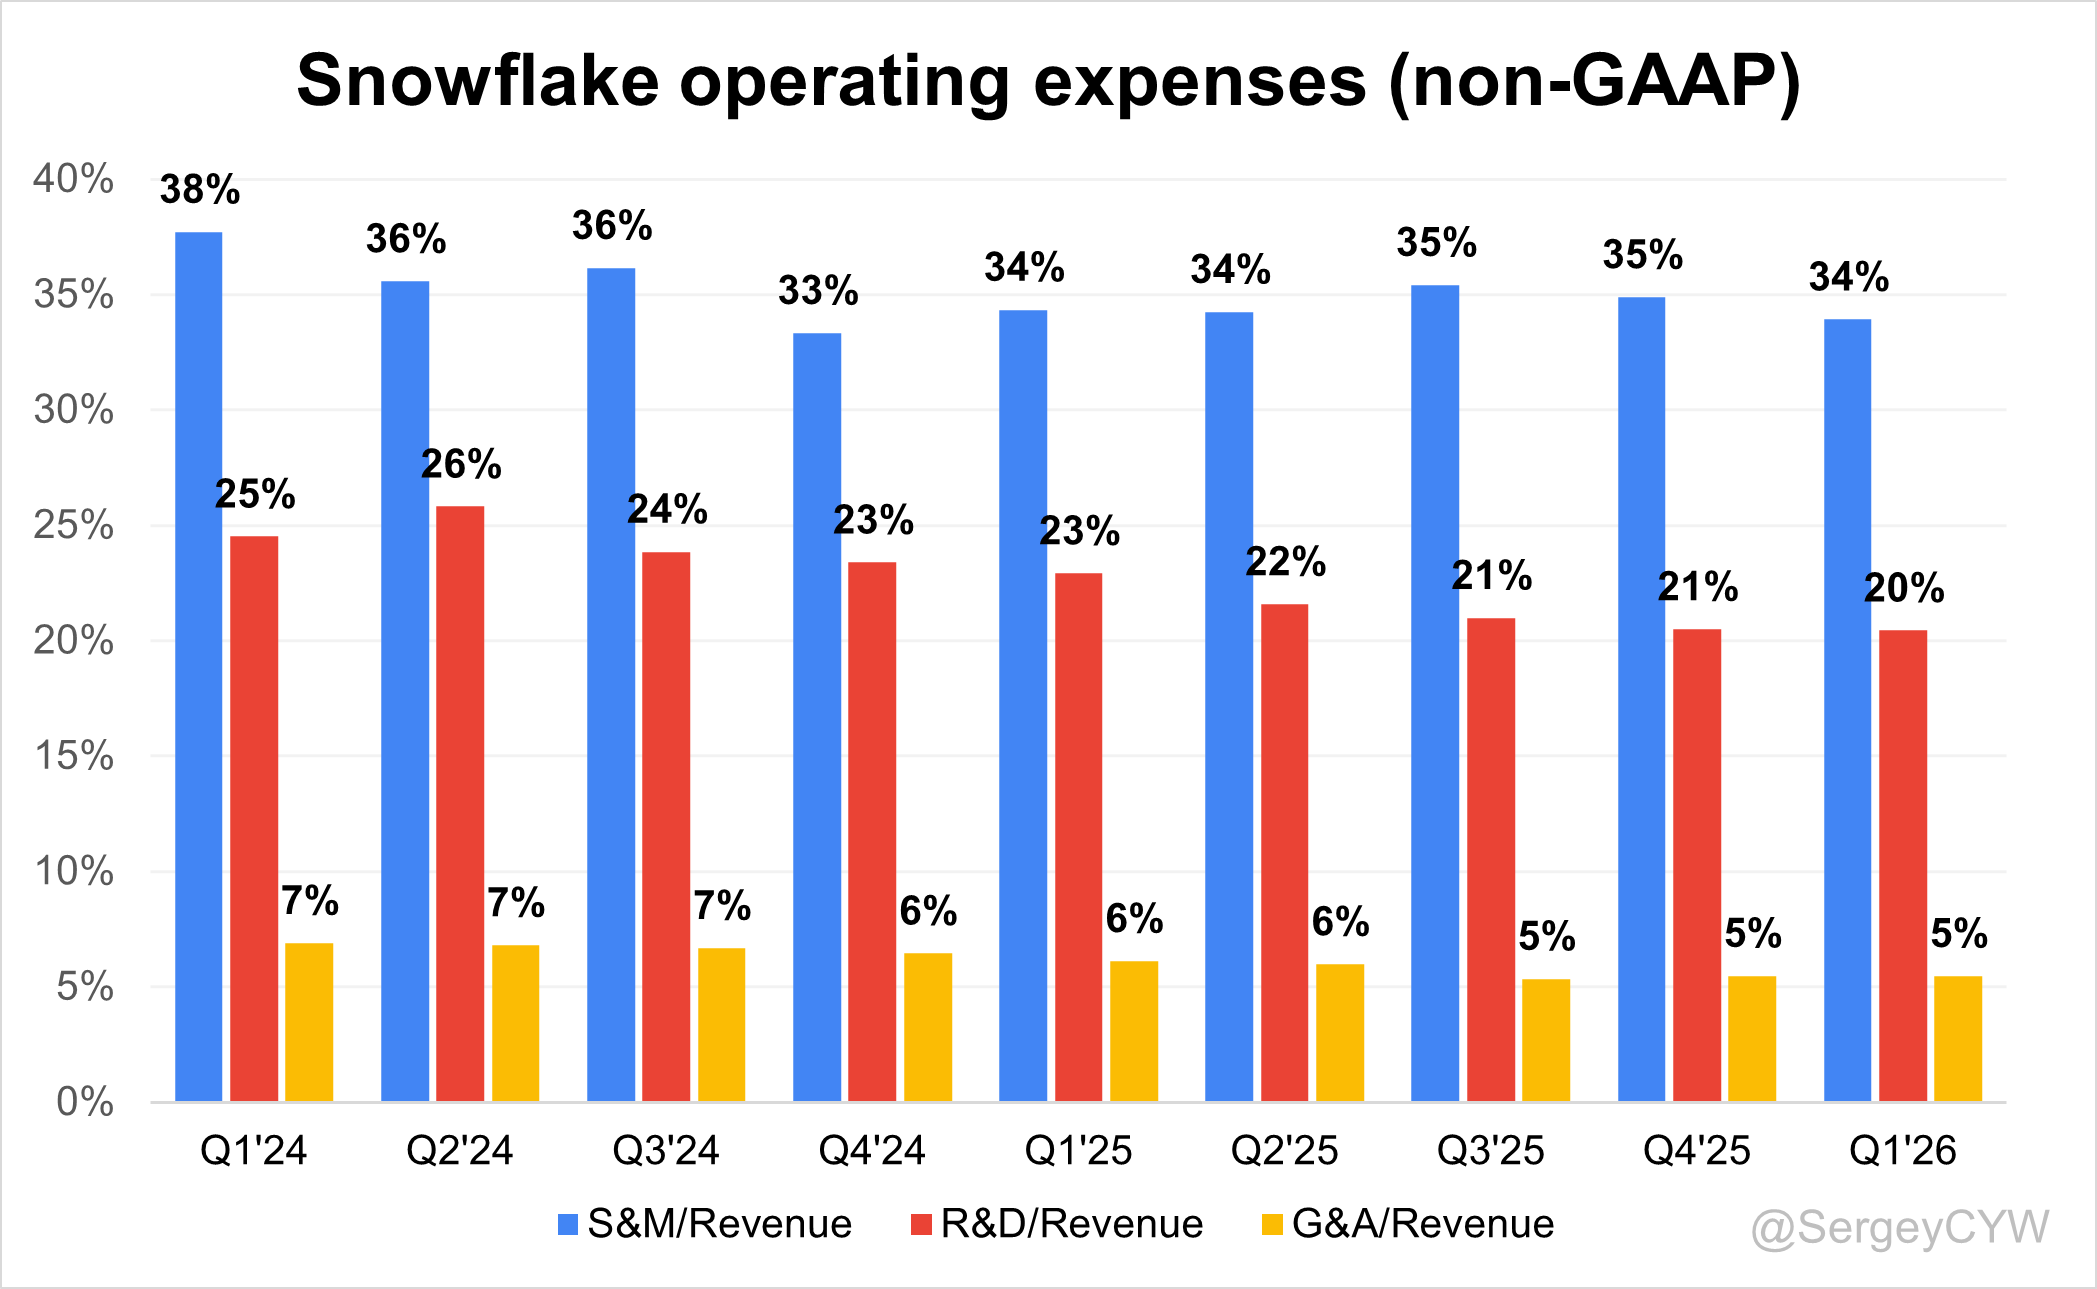
Over the past two years, SNOW has reduced operating expenses as a percentage of revenue, with a significant decline driven by lower S&M and G&A spending.
S&M expenses decreased from 38% in Q1 2024 to 34%, while G&A expenses fell from 7% to 5%. Meanwhile, R&D spending also declined from 25% to 20%, but remained at a relatively high level, reflecting the company’s continued commitment to reinvesting in product development and innovation.
Balance Sheet
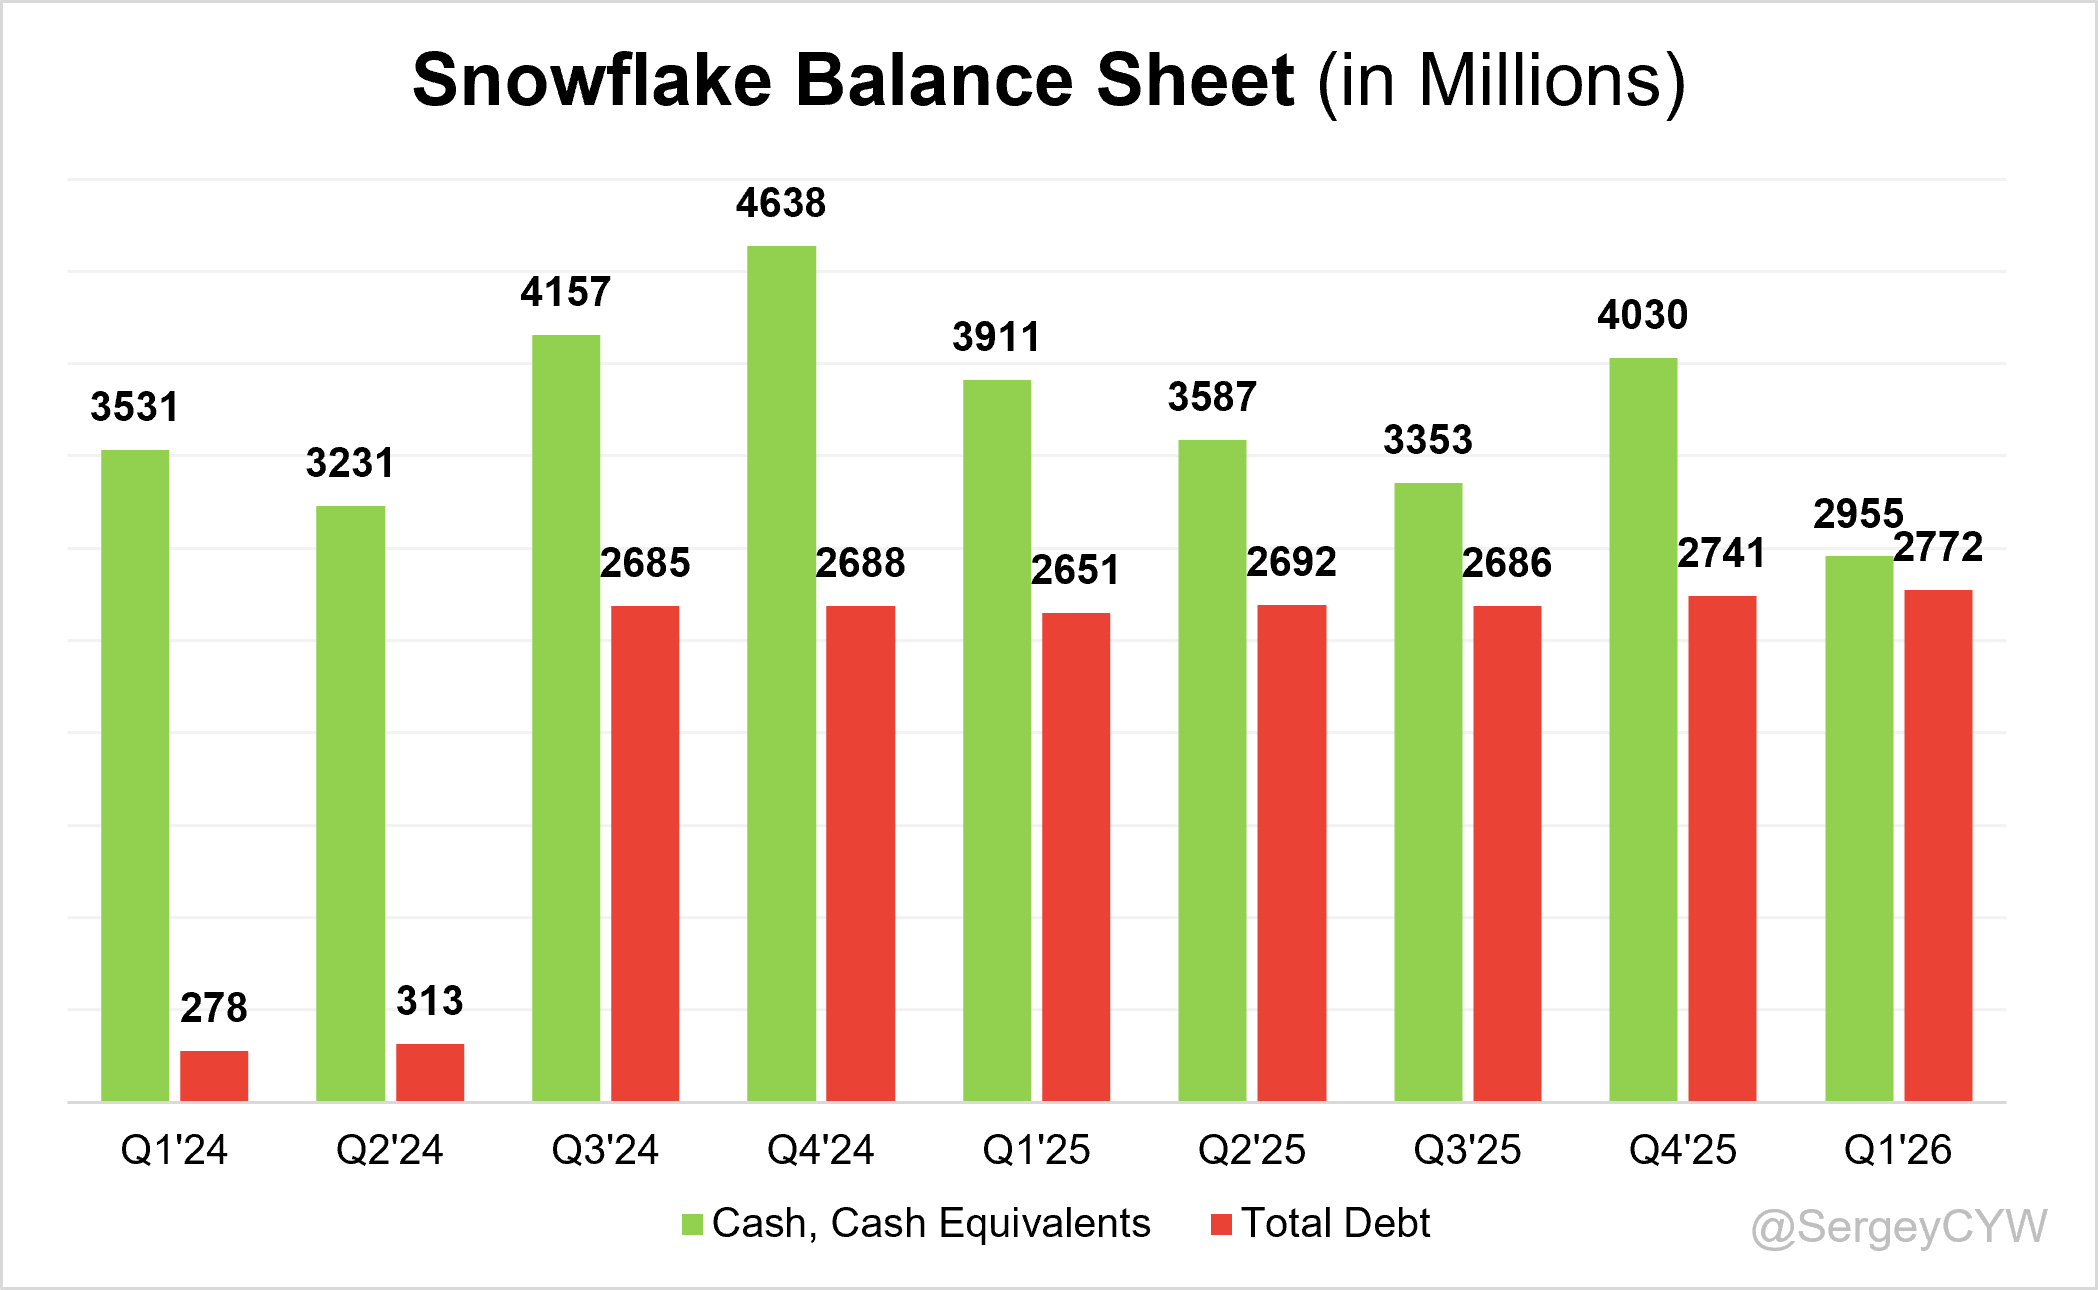
SNOW Balance Sheet: Total debt stands at $2,772 million. The company’s debt increased in Q3 2024 following the issuance of $2.3 billion of 0% convertible senior notes, split between $1.15 billion due in 2027 and $1.15 billion due in 2029.
However, Snowflake holds $2,955 million in cash and cash equivalents, which exceeds its total debt balance and helps keep the company’s balance sheet relatively healthy.
Snowflake recently announced acquisitions:
In late 2024, it acquired Datavolo, a platform for managing multimodal data pipelines powered by Apache NiFi. The deal expands Snowflake into the $17B data integration market and is expected to accelerate growth in the public sector, where Datavolo already has strong adoption.
On June 1, 2025, Snowflake acquired Crunchy Data for about $250M. Crunchy generates $30M+ annualized revenue and is known for secure, enterprise-ready PostgreSQL. The acquisition supports the launch of Snowflake Postgres, aimed at developers building AI-driven applications.
In November 2025, Snowflake acquired Datometry—a company that specializes in database migration and virtualization technology.
In January 2026, Snowflake announced its intent to acquire Observe, an IT observability platform built natively on Snowflake’s architecture. Valued at approximately $1 billion, this marks Snowflake’s largest acquisition to date, surpassing the $800 million Streamlit deal.
Shortly after the Observe announcement, in February 2026, Snowflake acquired TensorStax, an AI-powered data pipeline planner and autonomous data engineering platform.
In May 2026, Snowflake announced a definitive agreement to acquire Natoma. This acquisition is central to CEO Sridhar Ramaswamy’s vision of an “agentic control plane.”
Dilution
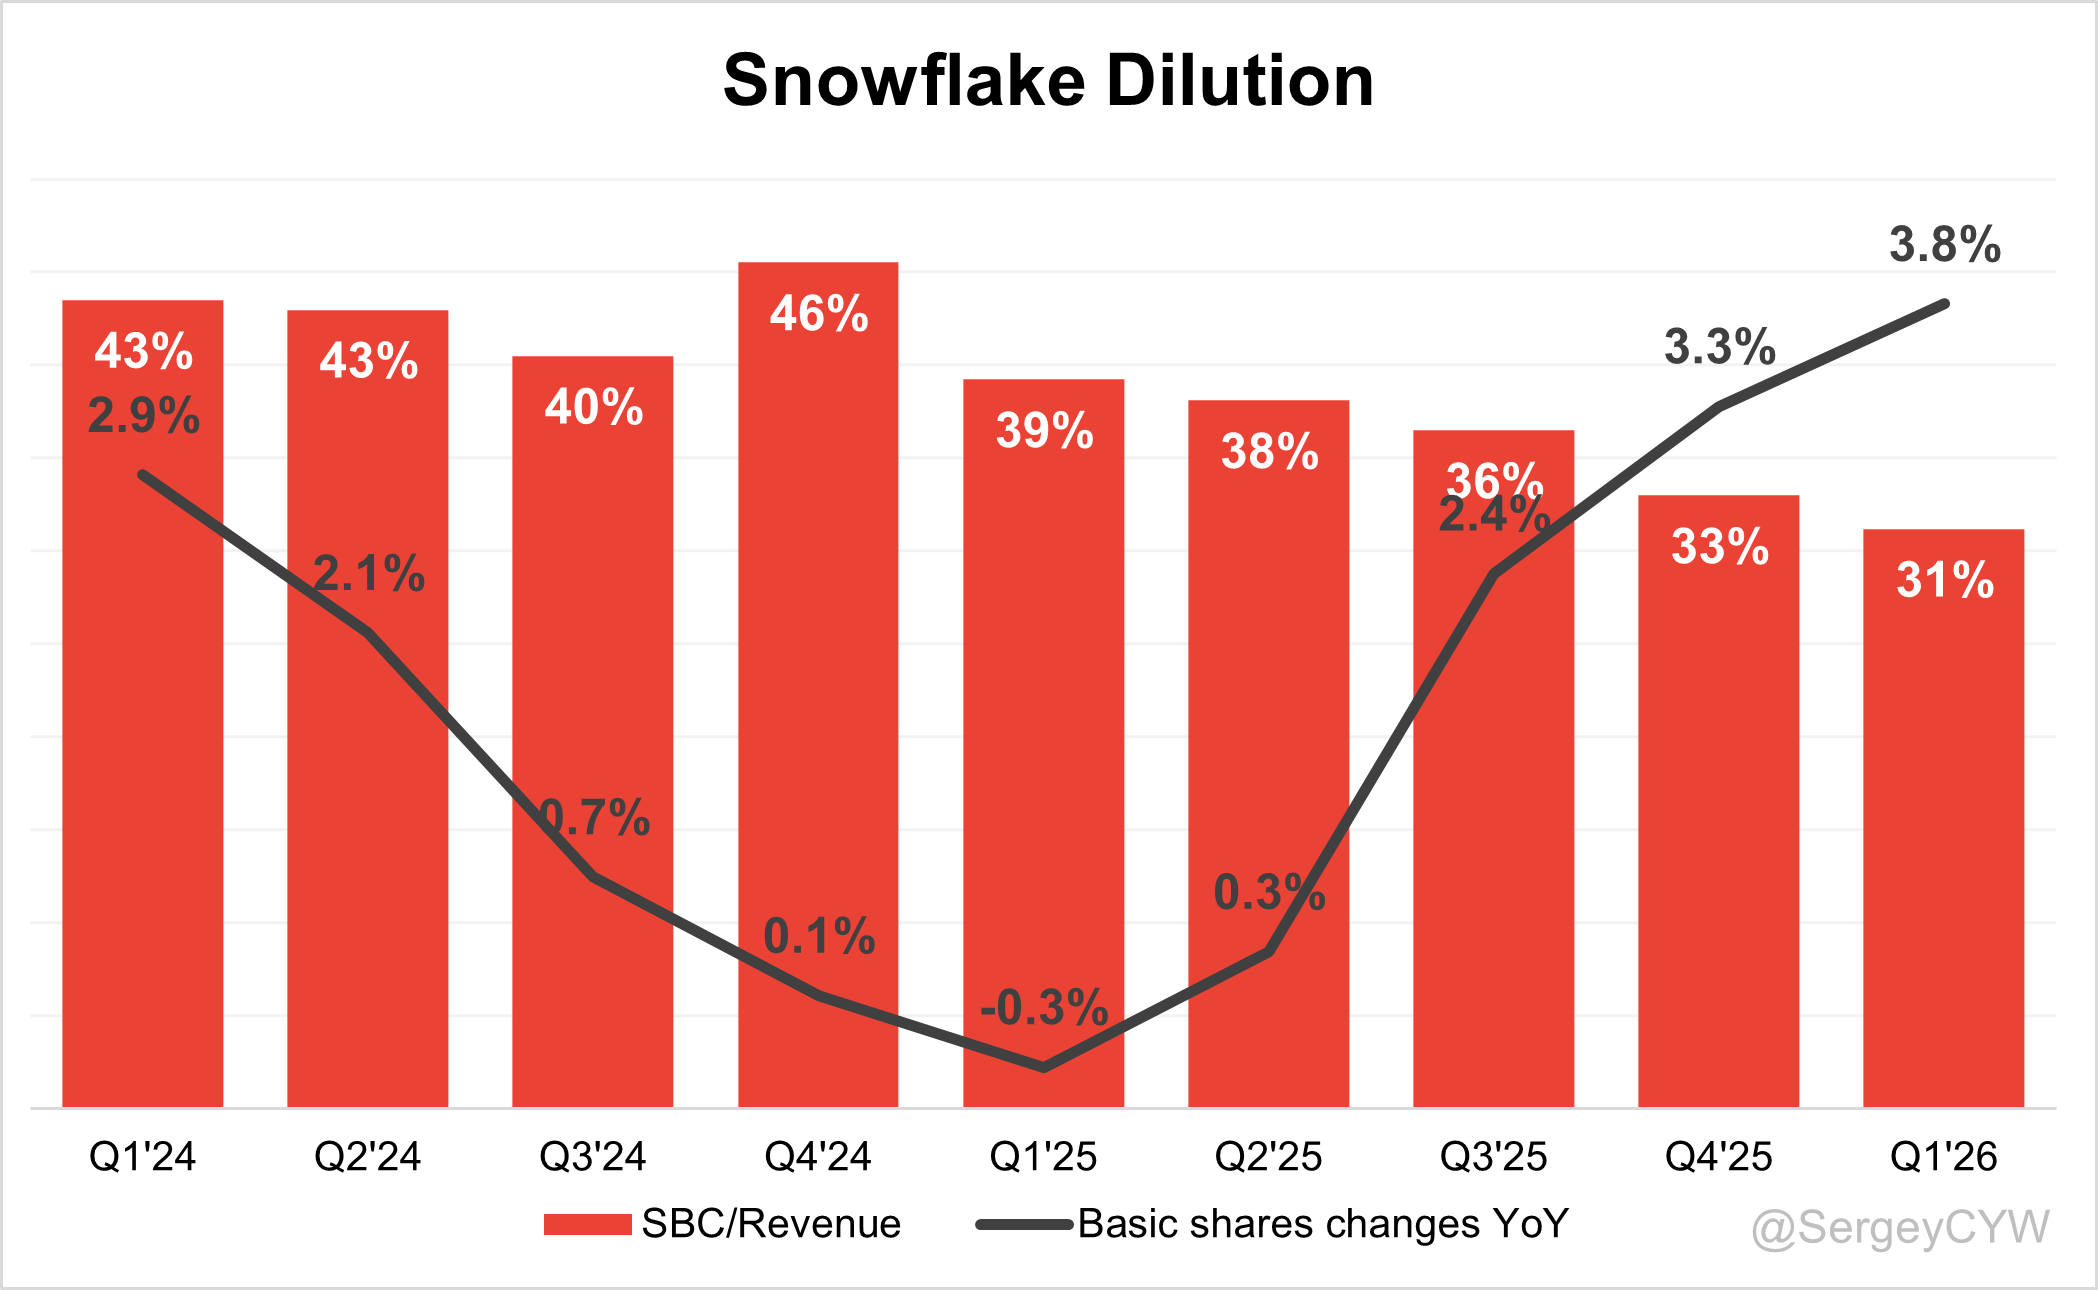
SNOW Shareholder Dilution: Snowflake’s stock-based compensation (SBC) expenses were previously at very high levels but declined in the last quarter to 31% of revenue, which remains relatively elevated. Management expects SBC as a percentage of revenue to decline to 27% this year.
Snowflake still has approximately $800 million remaining under its previously announced $4.5 billion share repurchase authorization. Management has emphasized prioritizing organic growth investments, particularly in R&D, before accelerating share repurchases, which I believe is the right strategy for Snowflake at its current stage of development.
The weighted-average number of common shares outstanding increased by 3.8% YoY, indicating a relatively high level of shareholder dilution.
9. Conclusion
Snowflake is strengthening its competitive position through new products such as CoCo. Management devoted a large portion of the earnings call to discussing CoCo, expressing significant enthusiasm for the product and highlighting highly compelling early results.
Sridhar Ramaswamy: “CoCo gives builders a natural language way to create applications, pipelines, agents, and workflows directly on Snowflake.”
“It in turn drives more consumption on the core data platform simply because it’s much easier to get projects done.”
Snowflake also completed a number of acquisitions over the past year, expanding its Total Addressable Market and entering the observability market. The acquisition of Natoma deepens Snowflake’s economic moat in AI by providing a secure gateway for AI agents to interact with enterprise applications. Snowflake Intelligence is also showing truly outstanding traction, with the number of accounts more than doubling QoQ, while AI workloads have become a meaningful revenue driver.
Innovation has accelerated under CEO Sridhar Ramaswamy, reflected in a substantial increase in R&D investment and a series of strategic acquisitions—a direction that I believe is the right strategy for the company. Management estimates Snowflake’s Total Addressable Market at approximately $170 billion in 2025 and $355 billion in 2029, representing a 16% CAGR.
Leading Indicators
• RPO growth of +37.5% and cRPO +37.5%, outpacing revenue growth
• Billings growth at +17.8%, slower than revenue growth
• Record net new ARR added in Q1, up +101% YoY
• Record large enterprise customer additions for Q1
Key Indicators
• Net Dollar Retention at 126%, up +1pp QoQ
• CAC Payback Period improved at 17.4 month
• RDI Score is up 1.6PPs QoQ, at 1.40, placing Snowflake among the leaders in SaaS
Snowflake’s economic moat—built on high switching costs and strong network effects—continues to strengthen. Data sharing now accounts for 44% of platform usage, up from 32% two years ago. Marketplace activity also remains strong, with 293 new listings added in Q1, a record for a first quarter.
Snowflake reduced S&M and G&A expenses while continuing to invest heavily in R&D, reinforcing its long-term competitive advantages. Revenue growth reaccelerated to +33.5% YoY under Ramaswamy’s leadership, supported by aggressive reinvestment into future growth. If Snowflake beats its own revenue guidance by 5.3%, consistent with Q1 performance, Q2 revenue growth would accelerate to approximately +36.2% YoY, supported by strong RPO growth and robust customer additions.
Q1 2026 was an exceptionally strong quarter, which was reflected in the stock’s +37.5% move following earnings. Most importantly, Snowflake continues to strengthen its economic moat.
During Q1, Snowflake signed a significant new five-year $6 billion AWS contract, more than doubling the prior FY2023 agreement. The company also announced an expanded $200 million partnership with OpenAI.
The Forward EV/Sales multiple appears fairly valued relative to Big Data peers, especially considering Snowflake’s high revenue growth rate.
SBC as a percentage of revenue remains elevated, but it has declined meaningfully, demonstrating that management is actively controlling dilution.
CEO Sridhar Ramaswamy:
“We believe that Snowflake is uniquely positioned to lead in the era of the agentic enterprise.”
$SNOW is one of the largest positions in my portfolio, currently representing 12.4% of total holdings. I increased my position on May 22, ahead of the Q1 earnings report.
Thank you for reading!
Follow me for more frequent updates on X/Twitter and Threads, and on LinkedIn. For visual infographics, check out Instagram, and for portfolio changes, follow me on SavvyTrader.
Disclaimer: This earnings review is for informational purposes only and does not constitute financial, investment, or trading advice.