

IOT Samsara continues to strengthen its position in connected physical operations, delivering a strong Q1 with revenue growth acceleration, nearly $2B in ARR, 115% NRR, and record first-quarter net new ARR additions.
Samsara is moving beyond fleet telematics into Operational AI, Connected Asset Maintenance, Ground Intelligence, Waste Intelligence, Asset Tags, Connected Workflows, and agent-based automation. Emerging products now contribute more than 20% of net new ACV, showing broader product-market fit.
Valuation has reset near historical lows, while analysts forecast 21.4% NTM revenue growth. But one question matters: can Samsara sustain high growth while gross margin faces pressure from AI, cloud infrastructure, DRAM, and NAND costs?
Table of Contents:
1. Company Overview – A brief summary of the company, including its mission, sector, competitive advantage, and total addressable market (TAM).
2. Valuation – Analysis of changes in Forward EV/Sales and Forward P/E multiples, along with comparisons to peers within the same sector.
3. Economic Moat – Evaluation of the company’s moat across five key types: Economies of Scale, Network Effect, Brand, Intellectual Property, and Switching Costs.
4. Revenue Growth – Review of revenue growth dynamics over the past two years.
5. Segments and Main Products – Overview of the company’s business segments, latest quarterly performance by segment, product innovation.
6. Market Leadership – Assessment of the company’s leadership status in its segment, as recognized by reputable rating agencies like Gartner, The Forrester Wave, etc.
7. Customers – Analysis of customer growth trends, customer success stories, and major customer wins.
8. Key Performance Indicators (KPIs) – Review of Retention, net new ARR, CAC payback period, RDI score, profitability, operating expenses, balance sheet strength, and shareholder dilution.
9. Conclusion – Final thoughts and summary based on the above analysis.
1. Company overview
About Samsara
Samsara is a pioneer in the Connected Operations Cloud, a platform that enables organizations reliant on physical operations to leverage Internet of Things (IoT) data for actionable insights and operational improvements. Founded in 2015 by Sanjit Biswas and John Bicket, the company is headquartered in San Francisco, California. Samsara serves tens of thousands of customers across industries such as construction, transportation, manufacturing, logistics, and retail, helping them digitize operations for enhanced safety, efficiency, and sustainability.
Company Mission
Samsara’s advantage comes from multi-product adoption, operational data scale, and workflow depth. The platform integrates video-based safety, telematics, app workflows, equipment monitoring, and real-time analytics into one operating layer for physical industries. AI capabilities such as Ground Intelligence help customers optimize routing, safety, utilization, and maintenance decisions.
Samsara recently won a $30 million arbitration award against Motive Technologies for unfair competition, highlighting the value of its technology, customer relationships, and position in connected operations.
Total Addressable Market (TAM)
Samsara’s official 2025 TAM is $137 billion, driven by its core Connected Operations opportunity. Connected Fleet Solutions represent $51 billion, covering telematics, fleet optimization, safety, and asset visibility.
External market estimates point to a much larger long-term opportunity. Future Market Insights projects the Smart Connected Assets and Operations Market at $195.4 billion in 2025, rising to $511.1 billion by 2035 at a 6.8% CAGR. Data Bridge Market Research estimates $258.79 billion in 2024, expanding to $538.02 billion by 2032 at a 9.58% CAGR. Market Research Future forecasts $284.1 billion in 2024, reaching $690.7 billion by 2035 at an 8.41% CAGR.
Growth is supported by digital transformation across physical operations industries, which represent about 40% of global GDP. Adoption is accelerating as transportation, construction, logistics, utilities, and field services digitize fleets, assets, workflows, and safety systems.
AI integration is another core driver. Samsara’s platform processes more than 14 trillion data points, supporting predictive analytics, safety insights, routing optimization, maintenance decisions, and operational automation.
Regulatory pressure also supports demand. Electronic logging, safety monitoring, environmental reporting, and compliance requirements continue to push asset-heavy industries toward connected platforms.
2. Valuation
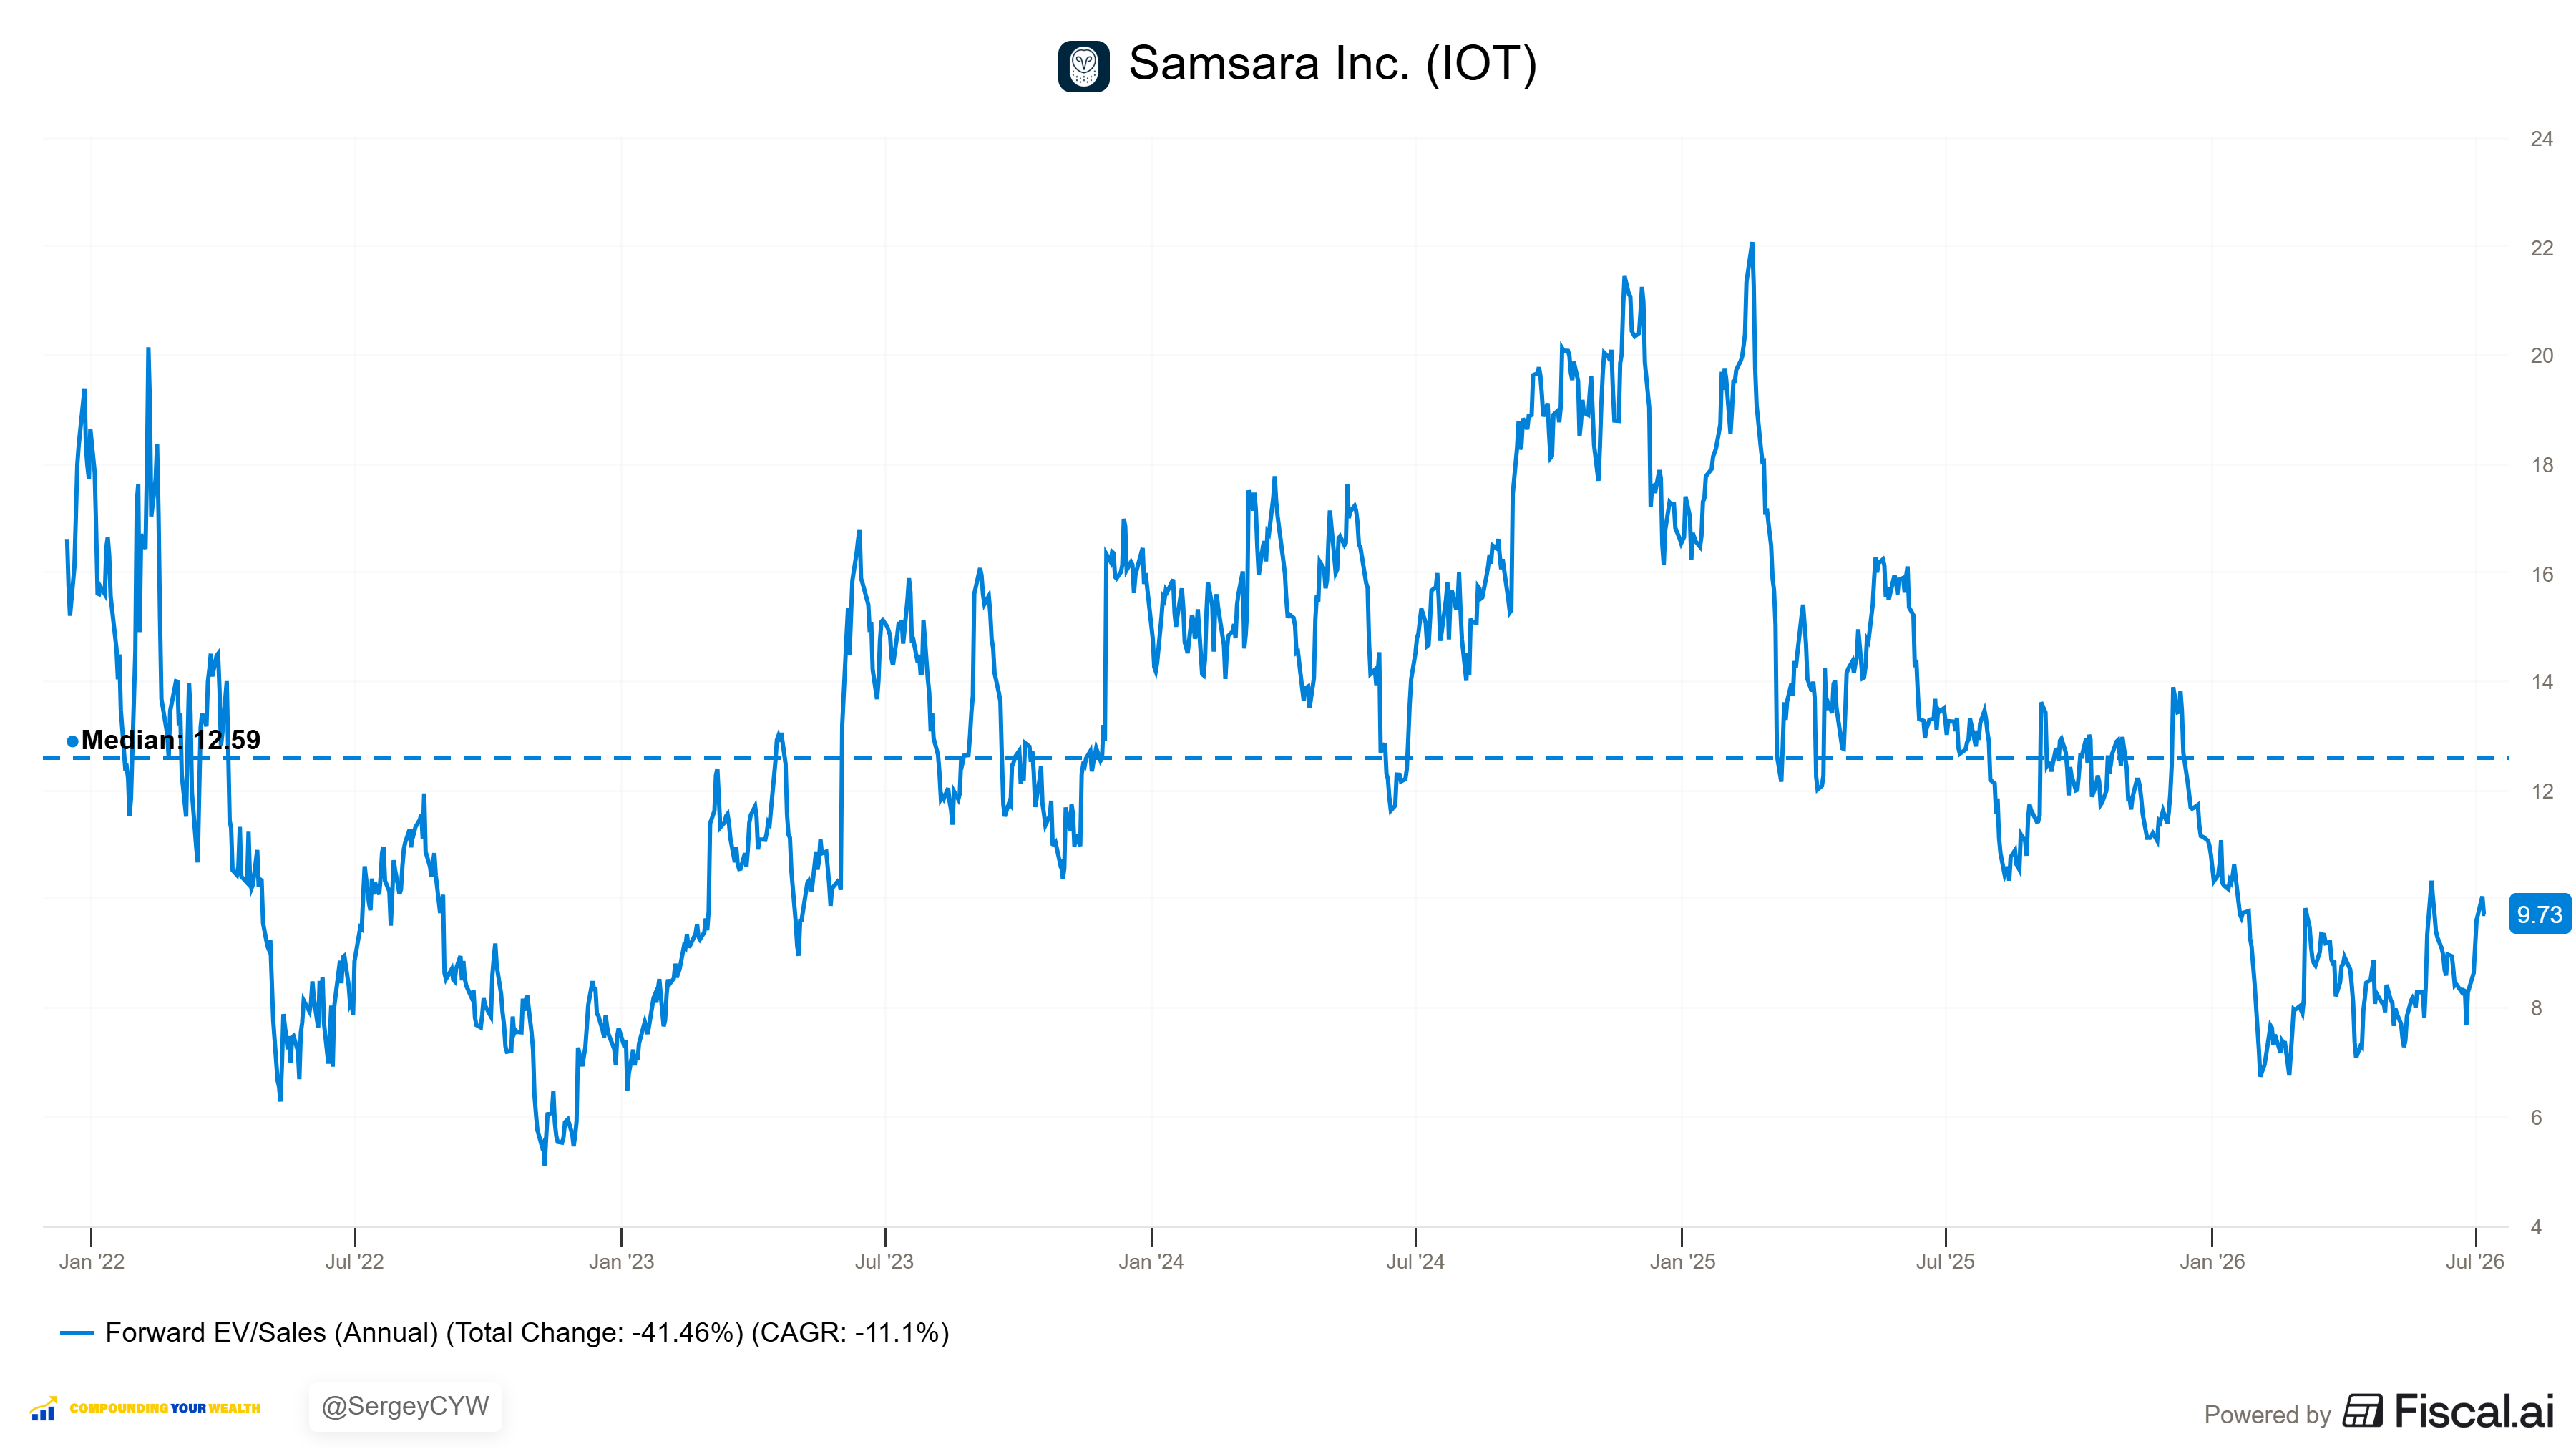
IOT Samsara is trading at a Forward EV/Sales multiple of 9.74, which is below its average of 12.59.
Currently, Samsara is trading well below its historical average valuation, with its valuation near historical lows.
Powered by Fiscal.ai — get 15% off with affiliate link for Compounding Your Wealth readers.
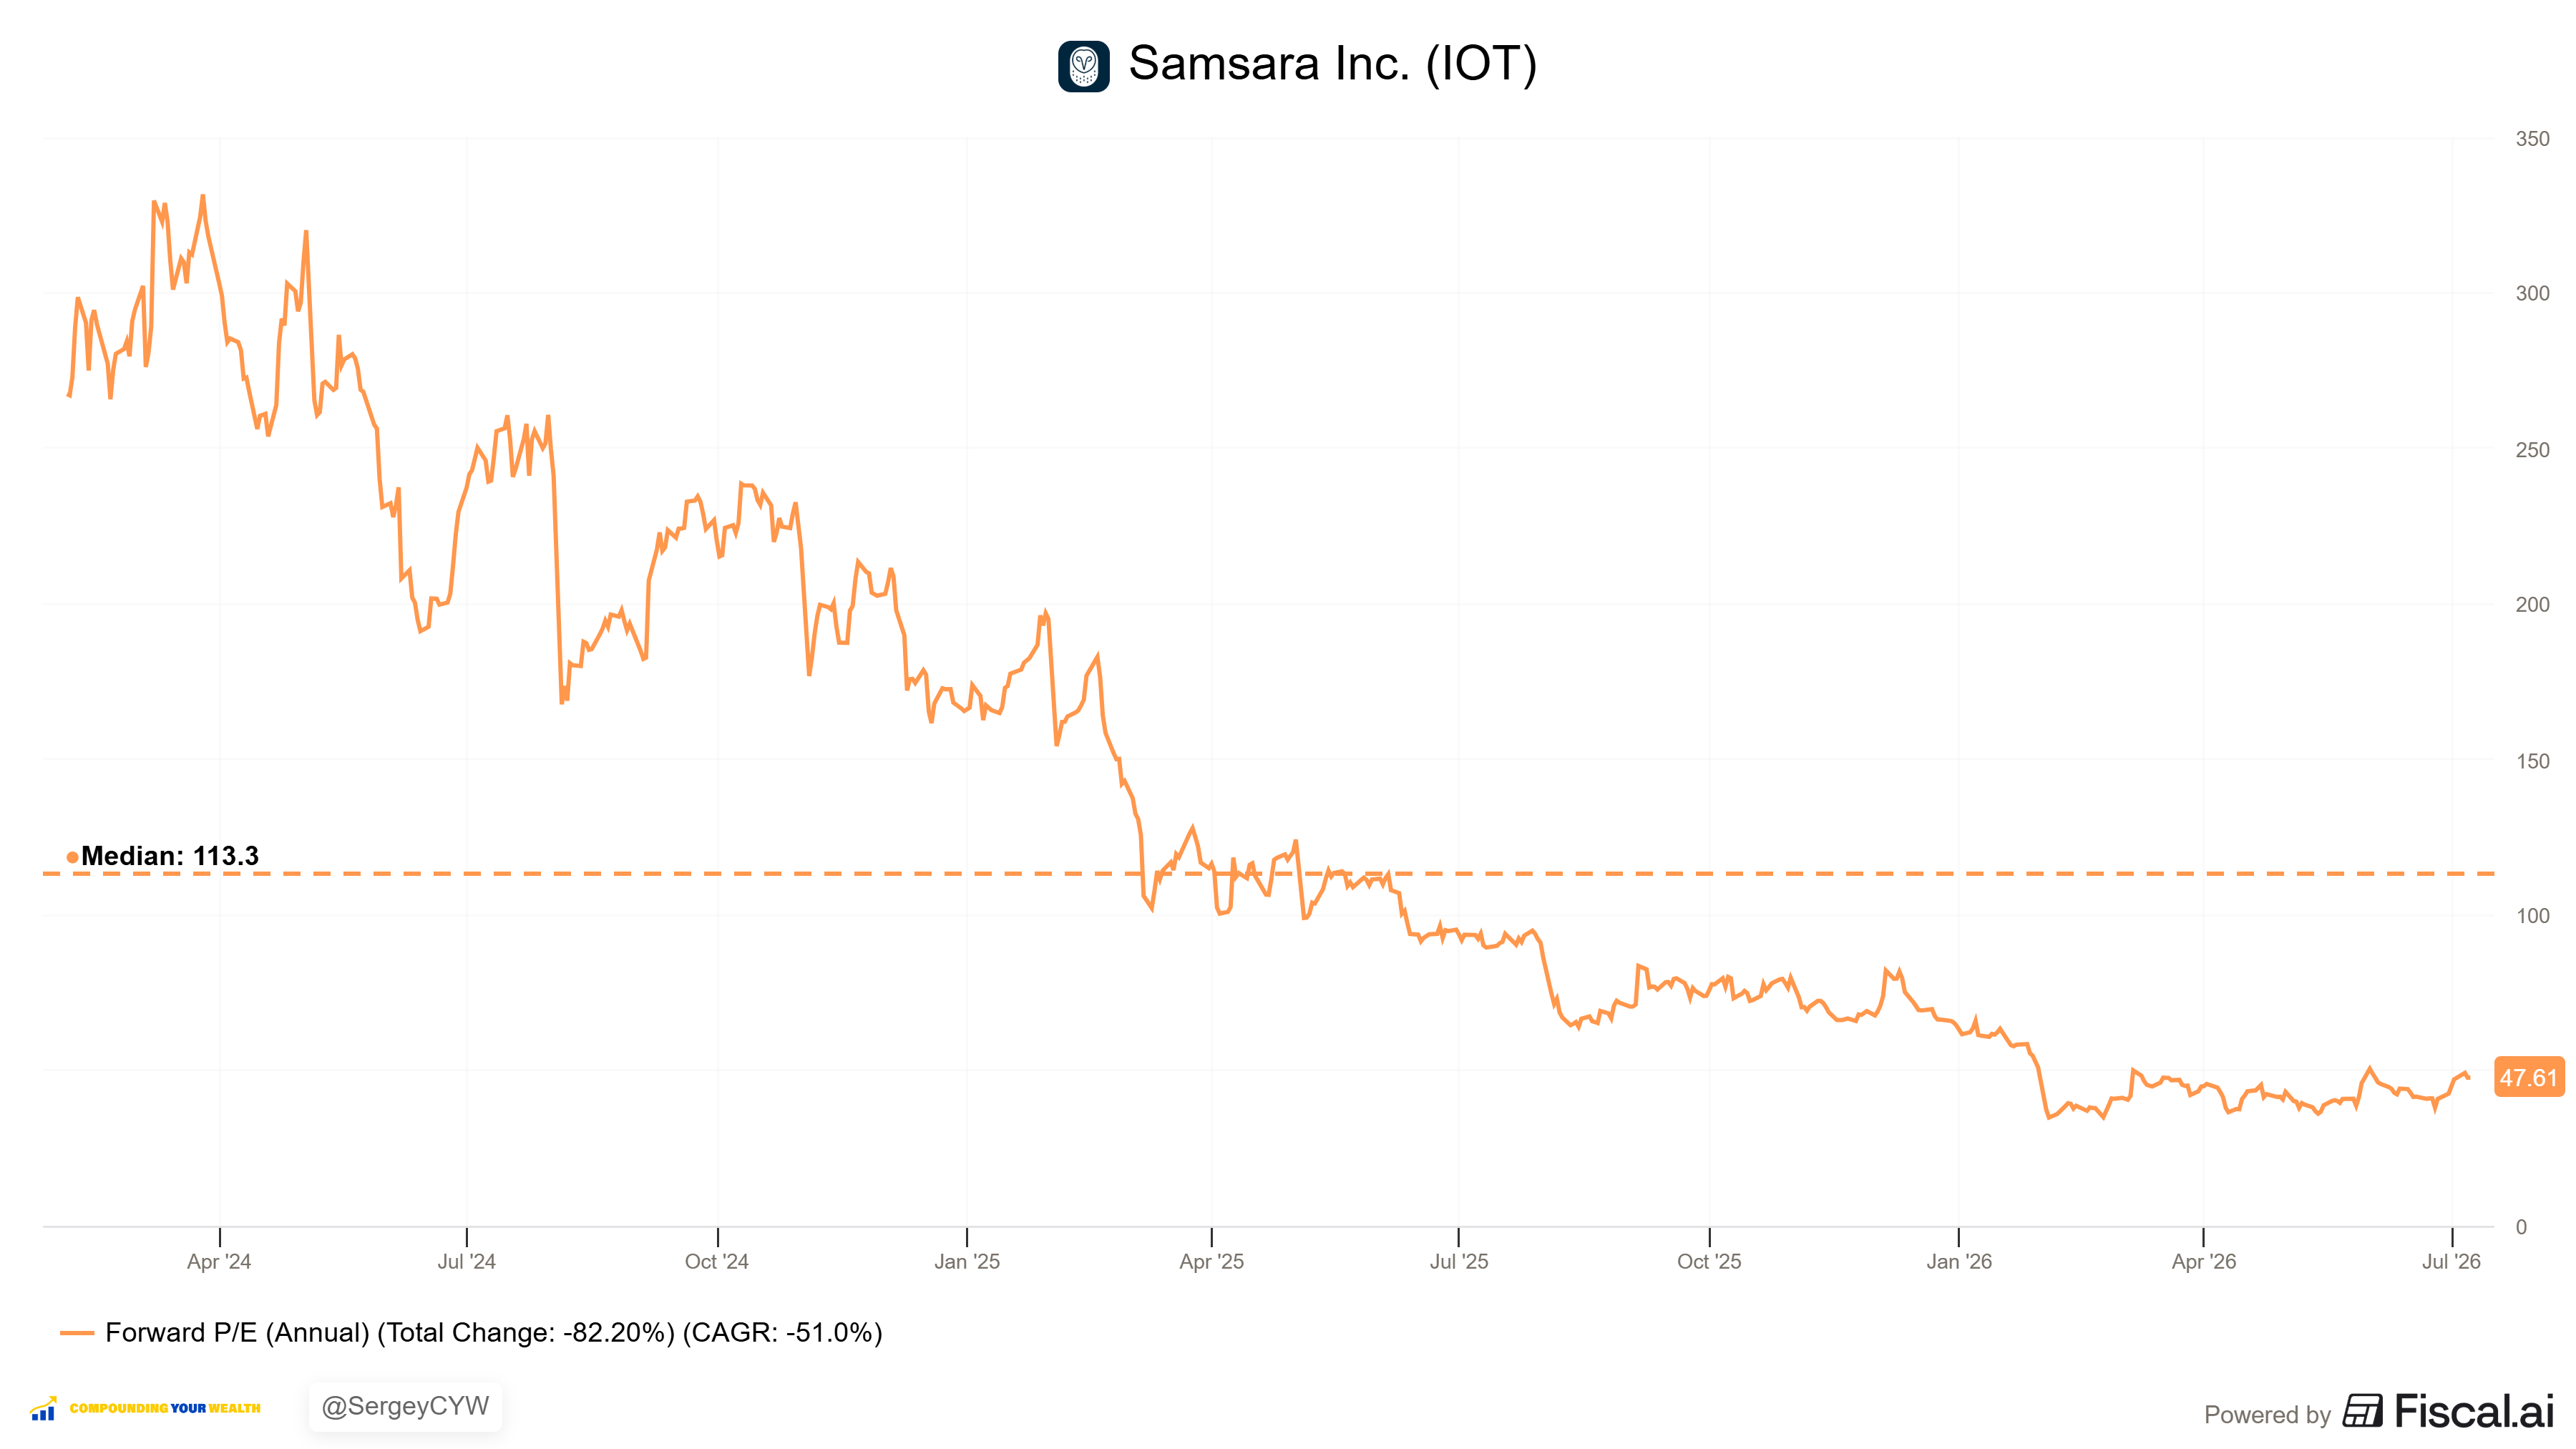
IOT Samsara trades at a Forward P/E of 47.6, with revenue growth of 30.5% YoY in the last quarter. This forward P/E ratio is 1.56 times the anticipated revenue growth rate.
The EPS growth forecast for 2026 is +26.4%, with a P/E of 50.7, resulting in a 2026 PEG ratio of 1.9.
Powered by Fiscal.ai — get 15% off with affiliate link for Compounding Your Wealth readers.
The PEG (Price/Earnings to Growth) ratio is a key tool for evaluating growth stocks, introduced by Peter Lynch.
PEG < 1: Undervalued – A ratio below 1 suggests the stock is undervalued. For example, if the P/E is 15 and earnings are expected to grow by 20%, the PEG would be 0.75, indicating a good buying opportunity.
PEG = 1: Fair Value – A PEG of 1 means the stock price matches its growth expectations, representing fair value.
PEG > 1: Overvalued – A PEG above 1 indicates the stock may be overvalued, as its price is higher than its projected growth rate, making it riskier.
Valuation comparison
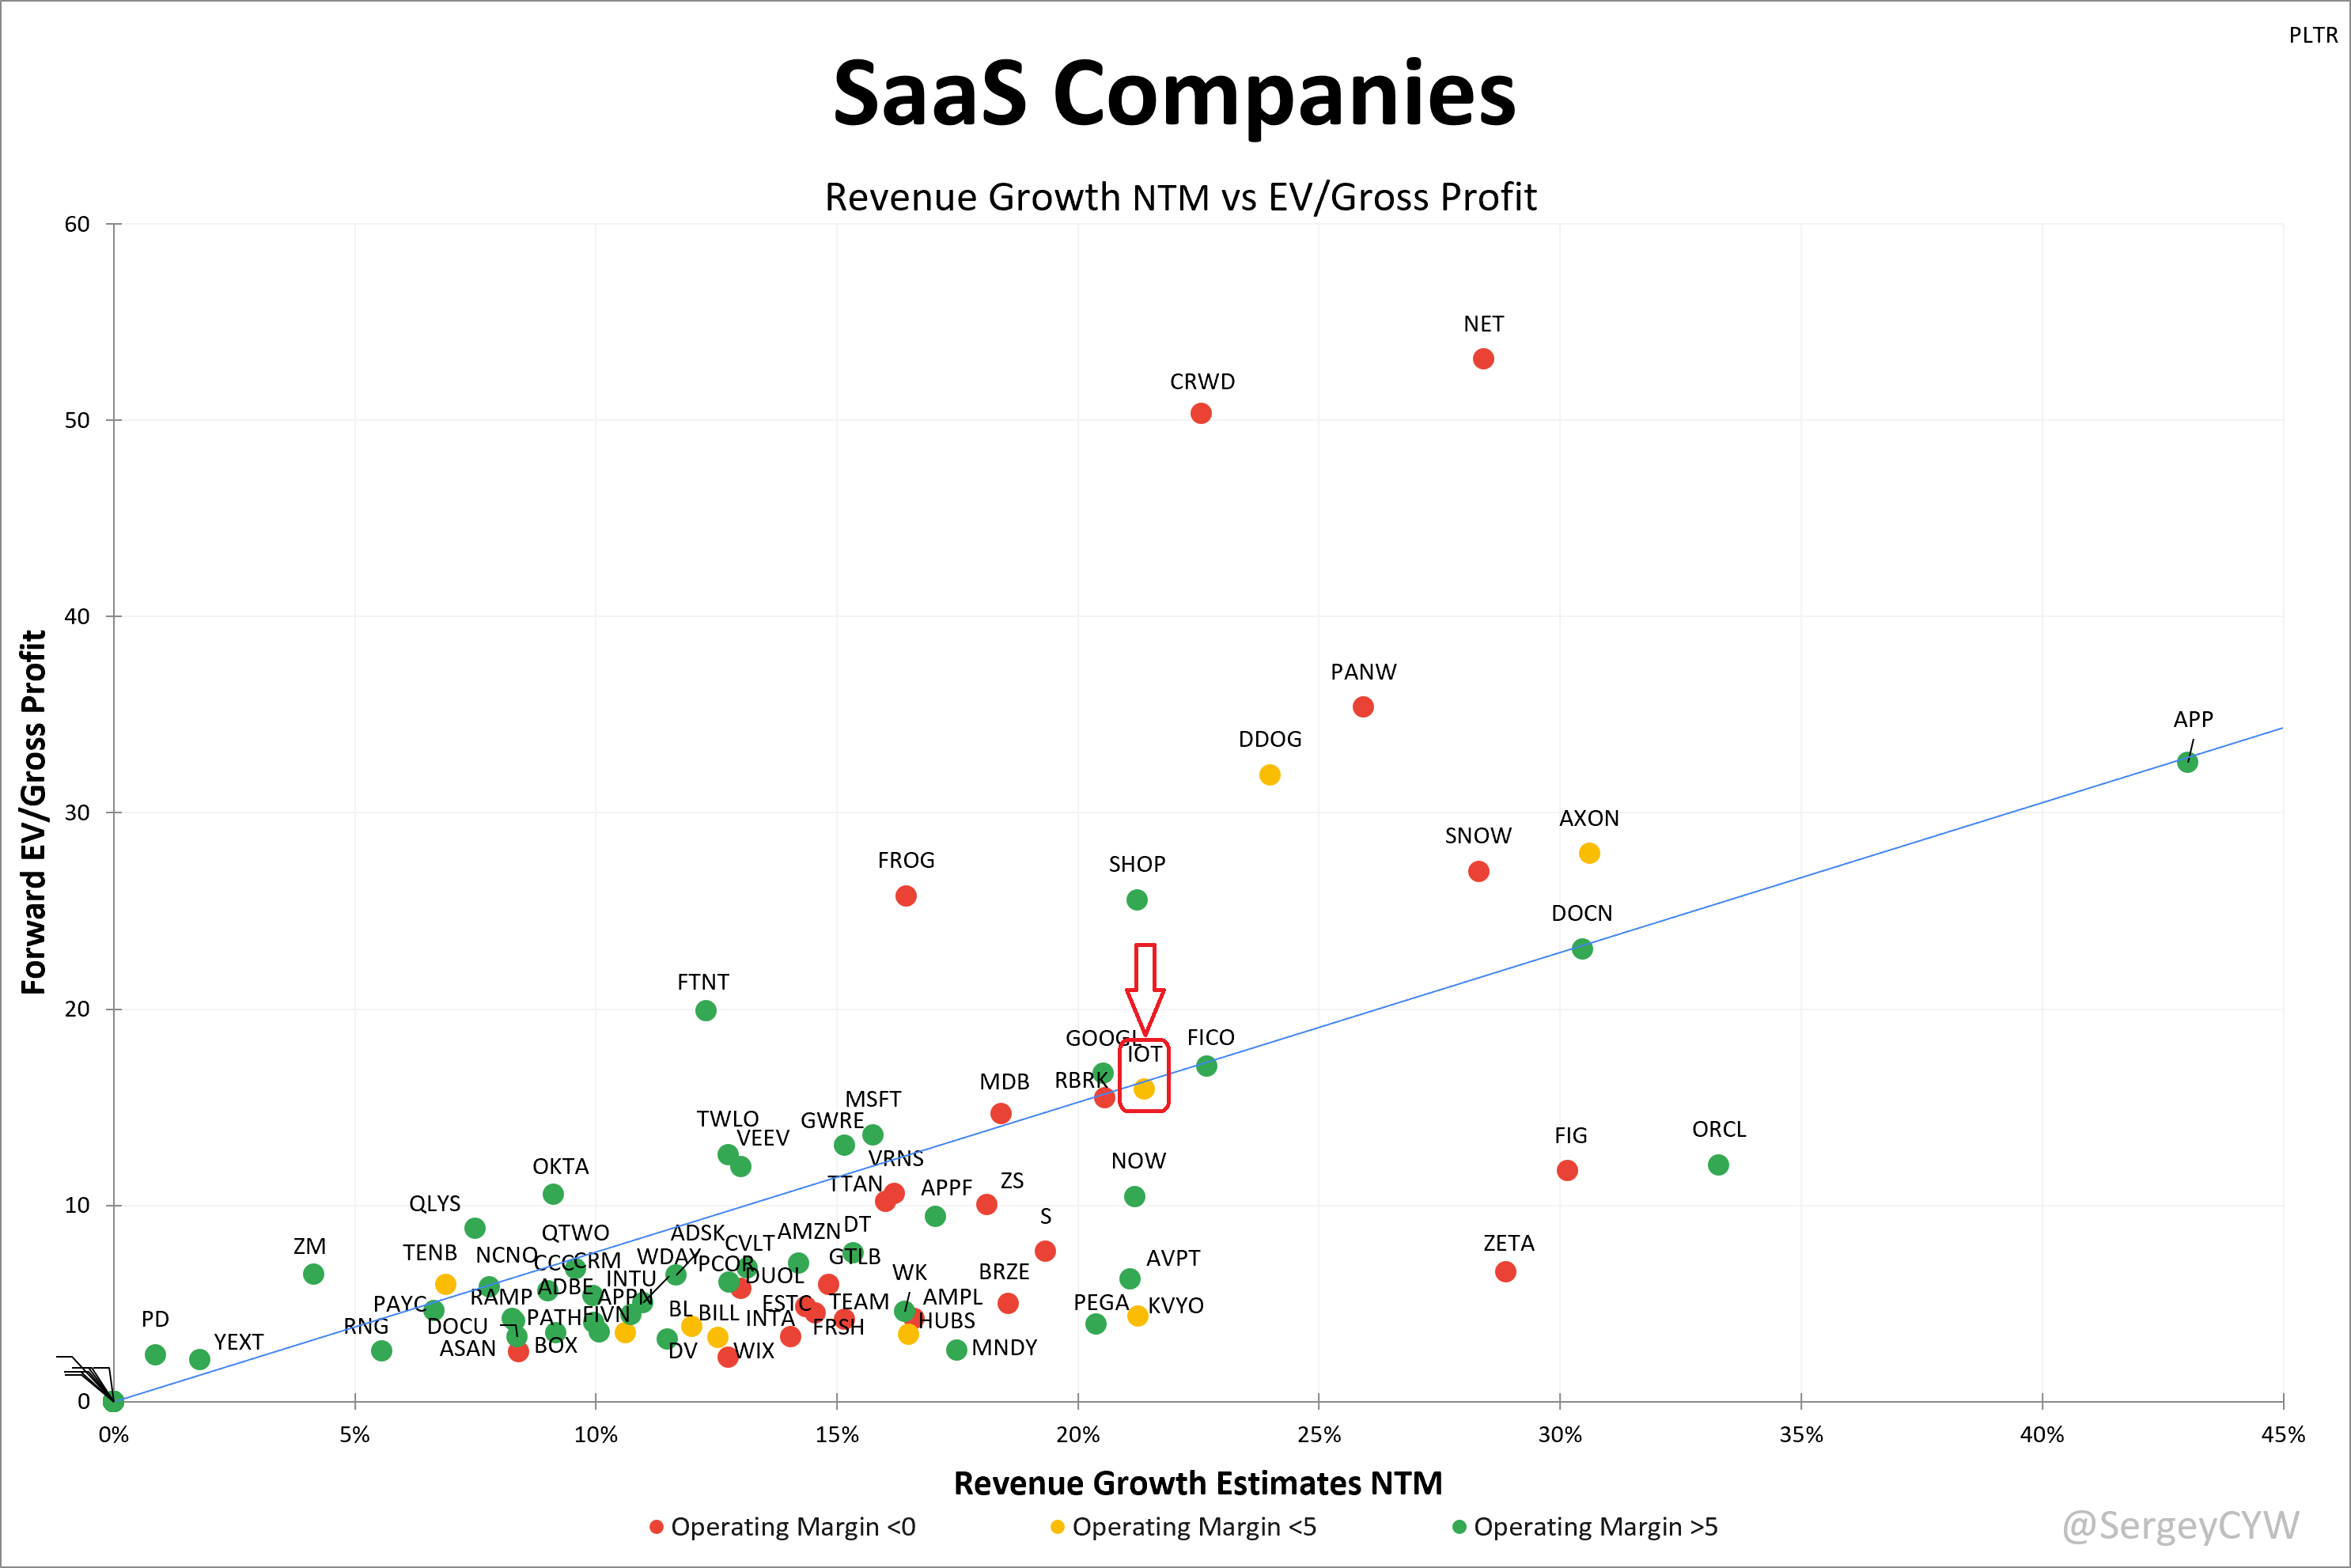
Analysts forecast +21.4% NTM revenue growth for IOT.
Based on these projections, the valuation—using the EV/Gross Profit multiple—appears slightly undervalued compared to other SaaS companies.
GAAP and non-GAAP operating margin is positive, but GAAP < 5%.
Analysts expect strong revenue growth, so let’s examine the key metrics to determine whether these expectations are justified.
We’ll evaluate the company’s economic moat, which supports long-term revenue growth, analyze revenue trends and the forecast for next quarter, and identify key factors that could help the company exceed expectations and sustain future growth.
We’ll assess the performance of key segments, the launch of new products and updates, customer acquisition growth, key financial metrics, financial stability, and margin trends.
Additionally, we’ll review the SBC/Revenue ratio, shareholder dilution, and finally, draw conclusions on the company’s outlook.
3. Economic Moat
Samsara possesses a narrow economic moat overall, with varying strengths across different moat categories. Let’s examine each type of economic moat in detail.
Economies of Scale
Samsara’s scale advantage is improving as the customer base grows and operating leverage expands. In Q1 FY2027, the company reached nearly $2 billion in ARR, up 30% year over year, while non-GAAP operating margin continued to improve. The limitation is gross margin. AI infrastructure, cloud processing, and hardware costs still pressure cost of revenue. Operating expenses are scaling better, but the gross margin moat remains Moderate.
Network Effects
Samsara’s network effect comes from data scale. The platform processes roughly 25 trillion data points annually across connected vehicles, equipment, and assets. More customers create more operational data, which improves predictive analytics, safety algorithms, and AI features such as Ground Intelligence. The data advantage is meaningful and hard for smaller vendors to replicate. The broader enterprise lock-in effect is still developing, but the network effect moat is Strong.
Brand
Samsara has built a strong reputation in Connected Operations Cloud, especially across transportation, construction, logistics, utilities, and field services. However, the brand does not yet carry the default buying power of legacy enterprise software leaders. Competition remains intense, and customers still compare alternatives such as Motive. The brand moat is Moderate.
Intellectual Property
Samsara holds 237 active IoT sensor patents, with 92% still active, covering key technologies like driver monitoring, sensor fusion, and battery management. Samsara’s IP is based on the combination of hardware sensors, edge computing, cloud software, and AI-driven analytics. The company actively defends its technology and trade secrets, including legal actions involving Motive. Still, telematics, dashcams, and fleet monitoring are not impossible to replicate. The proprietary value lies in execution, data, and integration depth. The IP moat is Moderate.
Switching Costs
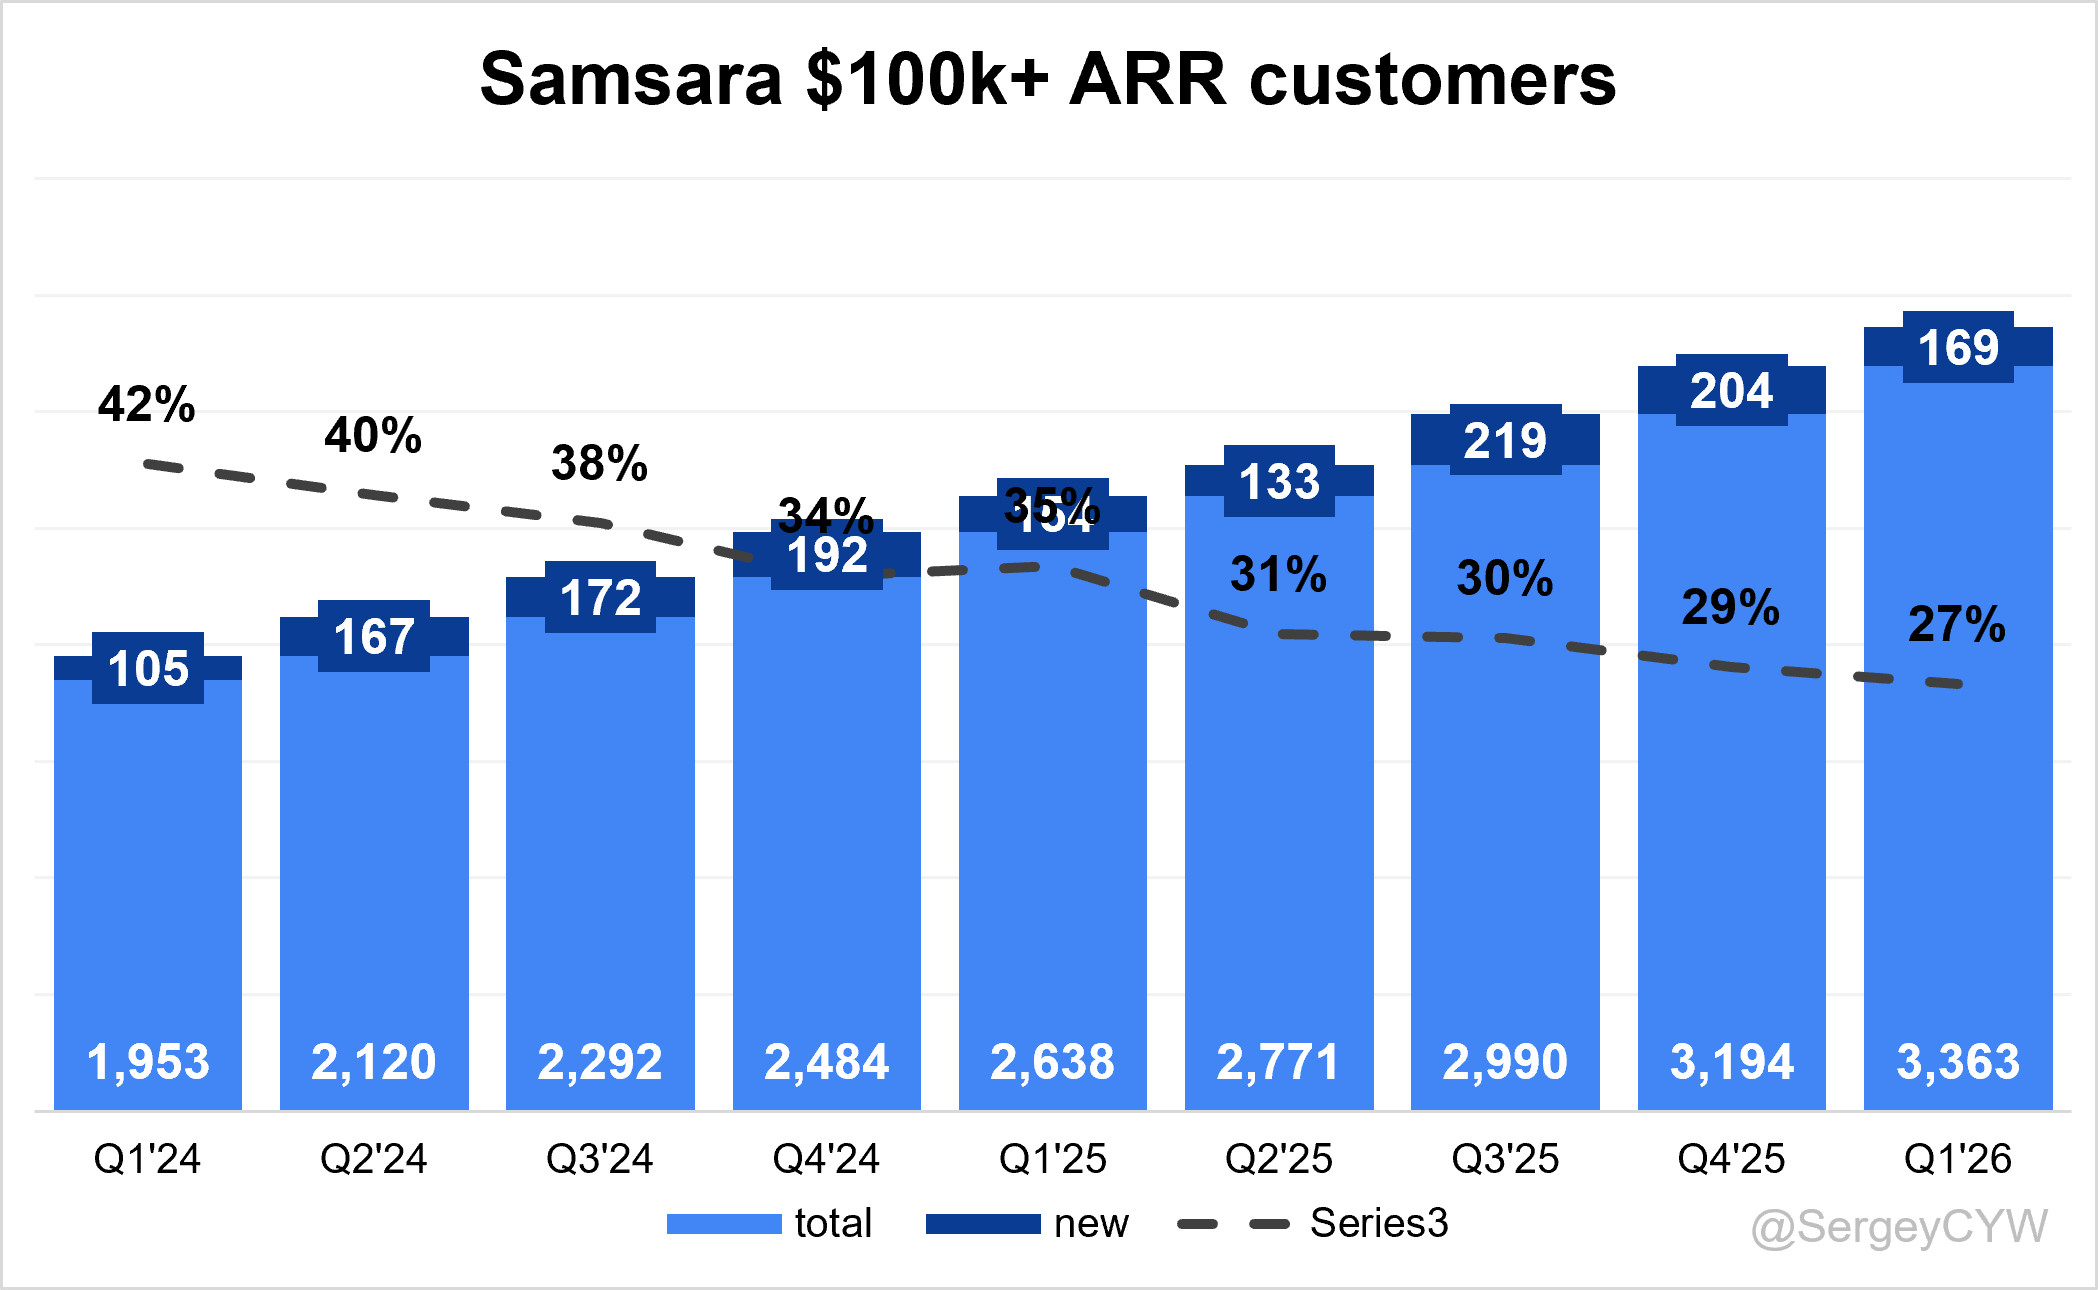
Switching costs are Samsara’s strongest moat. In Q1 FY2027, Samsara added 169 new customers with more than $100,000 in ARR, 115% net revenue retention in Q1. Once customers install hardware across fleets or industrial assets and embed Samsara into safety, maintenance, compliance, and operational workflows, switching becomes expensive and disruptive. Customers frequently describe Samsara as their “most utilized company-wide system,” reinforcing the platform’s centrality. The solution touches physical assets, software processes, and historical operating data. This moat is Very Strong.
Overall, Samsara’s economic moat relies on deep workflow integration, a growing data advantage, and improving scale in physical operations. The latest quarter, Q1 FY2027, shows stronger platform traction, but also highlights pressure from AI, hardware, and cloud infrastructure costs.
4. Revenue growth
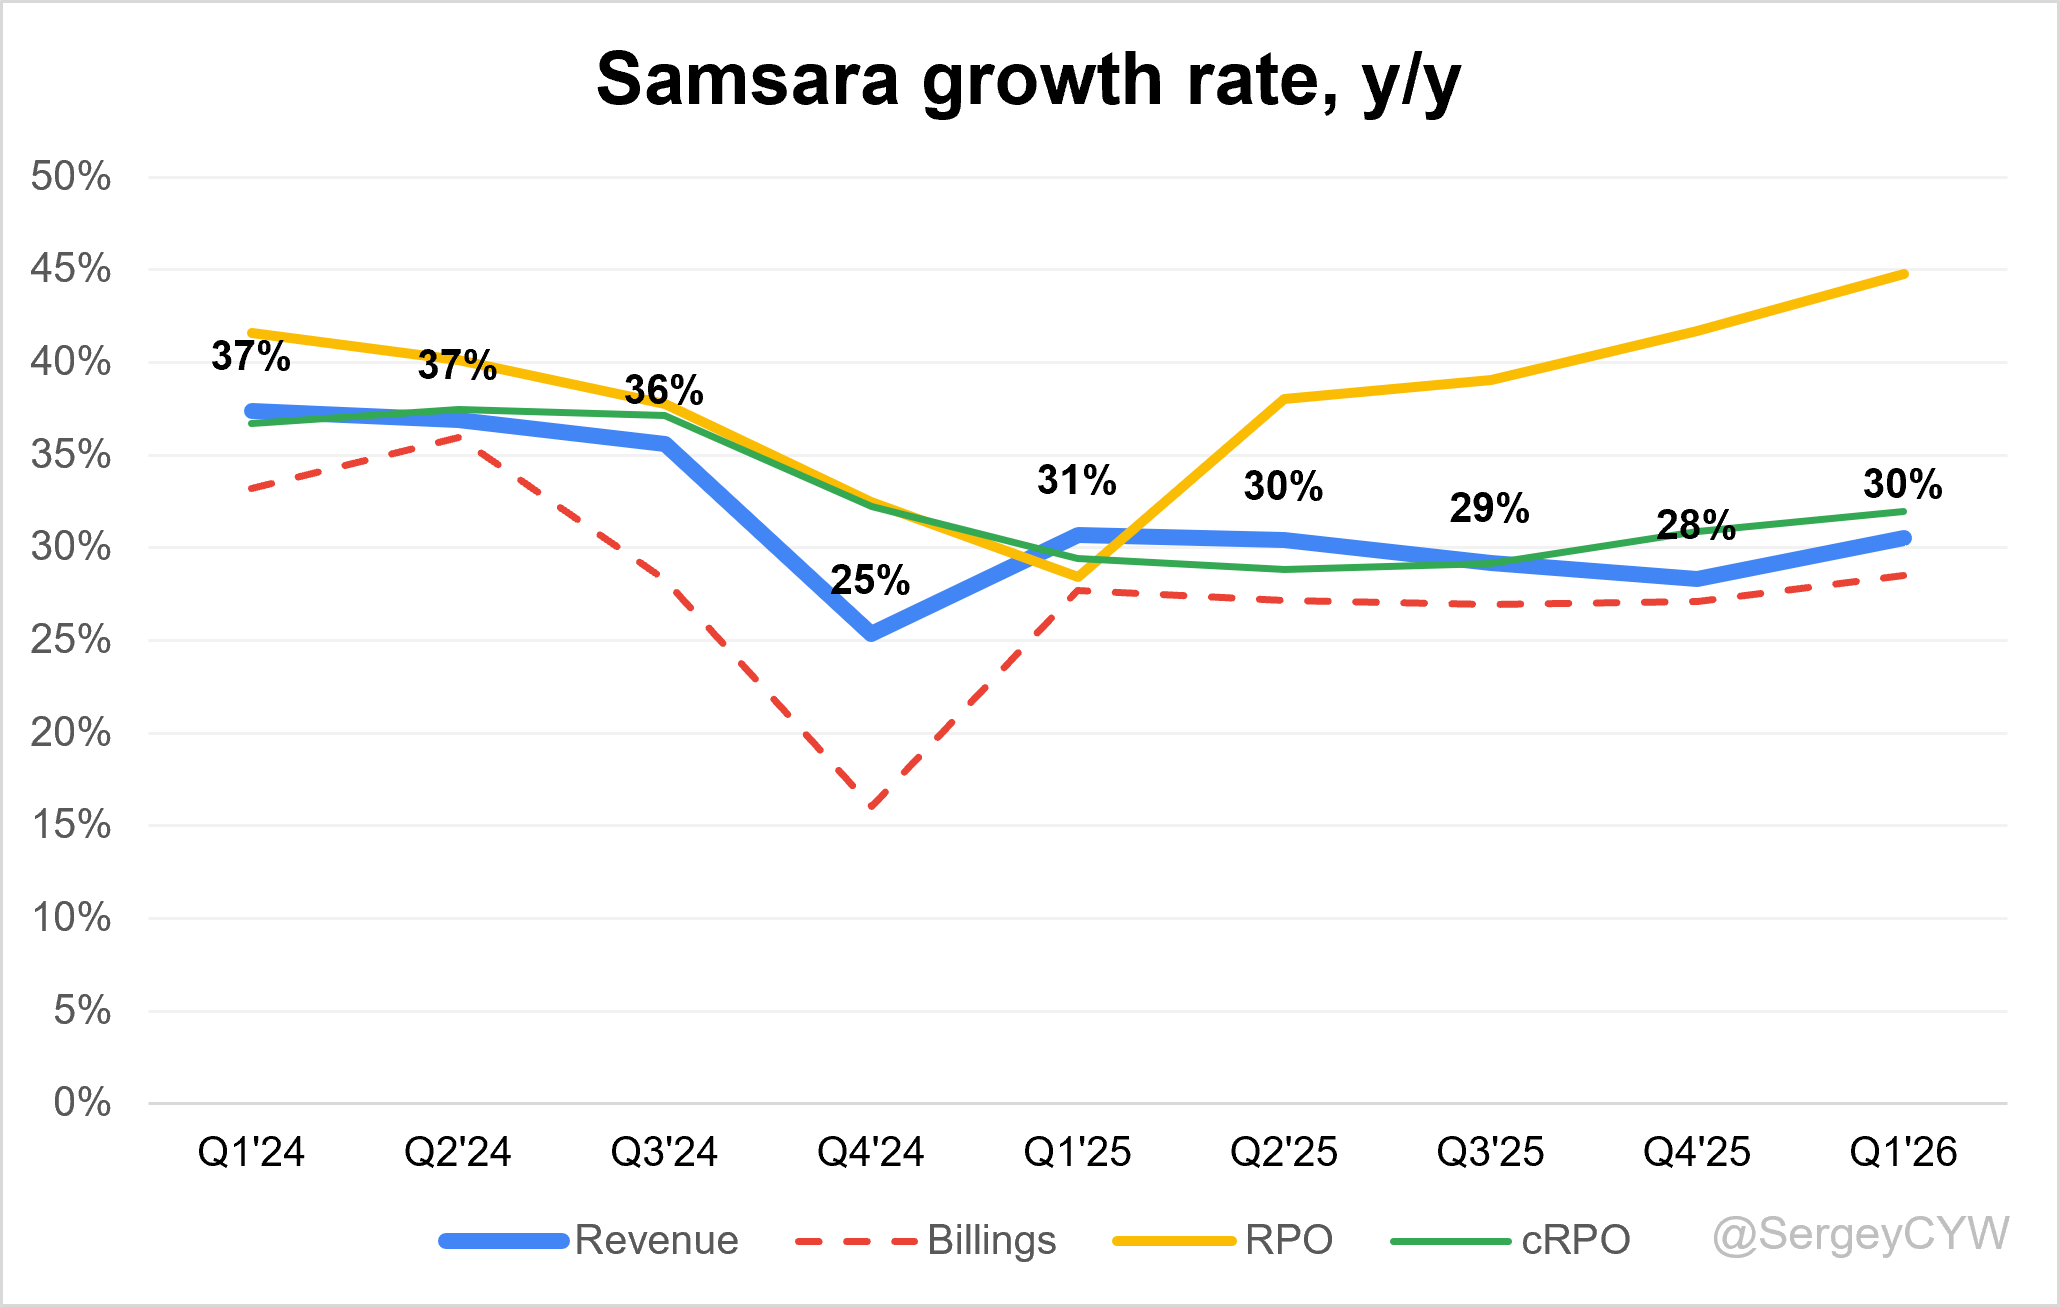
Samsara's revenue growth accelerated to +30.5% YoY in Q1, maintaining a strong and consistently high growth rate.
Based on guidance for the next quarter, if Samsara beats by 5.0% again, as it did in Q1, Q2 revenue growth would reach ~29.8%, indicating a stabilization in growth.
RPO growth accelerated to +44.7%, outpacing revenue, and cRPO growth also accelerated to +31.9%.
Billings growth stabilized at +29.6% YoY, growing at approximately the same pace as revenue.
5. Segments and Main Products
Samsara operates across three primary segments: fleet management, asset tracking, and industrial IoT.
The fleet management segment offers tools for real-time GPS tracking, vehicle diagnostics, driver safety, and compliance, enabling businesses to improve operational efficiency and safety. It is widely adopted in transportation and logistics.
The asset tracking segment monitors physical assets like trailers, containers, and heavy equipment. It provides real-time location data, geofencing, and environmental monitoring, ensuring better utilization and regulatory compliance for machinery-dependent industries. Samsara’s Asset Tags support this segment by offering real-time visibility into high-value assets, aiding in theft prevention, inventory management, and asset recovery. These rugged tags have a four-year battery life and integrate with Samsara’s IoT network, helping field teams locate equipment quickly and reduce downtime.
The industrial IoT segment connects equipment and machinery to Samsara’s cloud-based platform, delivering data-driven insights for sectors like manufacturing, construction, and logistics. This improves efficiency and supports sustainability goals.
Connected Workflows digitize multi-step processes by integrating forms like inspections and incident reports directly into the platform. This enables real-time data capture, simplifies compliance, reduces admin overhead, and allows teams to resolve field issues faster. By centralizing information and connecting departments, operations become more agile and coordinated.
Main Products Performance in the Last Quarter
Fleet Management
Samsara’s fleet platform remains the core growth engine. The company reached ~$2B ARR, growing ~30% YoY, with over 13,000 core customers worldwide. Fleet demand is supported by low digitization: only ~34% of commercial vehicles in North America and Western Europe are connected from a telematics perspective, while North America still has >35M commercial vehicles and only ~50% telematics penetration. Growth is helped by enterprise expansion, but rollout remains gradual because customers cannot stop physical operations to install hardware across trucks, trailers, bulldozers, and field teams.
Safety & Telematics
Safety and telematics continue to show strong ROI and high customer relevance. AI Dash Cameras are only ~15% penetrated in North America, leaving ~85% of the market unpenetrated. Customer results were strong: Primoris reported 66% fewer total events, 40% lower severe speeding, 42% fewer crashes, and roughly $5M annual savings from crashes and claims. Performance Food Group reported 90% reduction in speeding over 10 mph, 60% reduction in collision risks, and 67% improvement in repeat behaviors. Main challenge remains change management, especially around driver adoption, unions, privacy concerns, and large-scale deployments.
Industrial IoT
Industrial IoT is expanding Samsara beyond trucks into broader physical operations. The company targets industries representing ~40% of global GDP, including construction, energy, utilities, waste, food distribution, field services, and public sector. Penetration is still low: powered construction equipment is only ~13% connected, while unpowered equipment is below 1% connected. Growth dynamics are attractive because customers have large operations budgets, often spending about 80% of revenue on frontline labor, assets, vehicles, fuel, maintenance, insurance, and accident costs. The challenge is hardware deployment and operational complexity.
Asset Tags
Asset Tags are becoming a meaningful expansion layer. Samsara started with durable equipment tracking, then expanded into smaller assets with the XS version for PPE, fire extinguishers, gas meters, tools, and other field equipment. Primoris highlighted theft recovery as a clear ROI case, noting one recovered mini excavator or backhoe can pay for almost the whole program. Asset Tags also create product-market pull: customer demand for smaller, cheaper, more flexible tracking led to the new Tracking Label, a single-use label for shipments. Main challenge is scaling into new use cases without turning the product into low-margin hardware-only tracking.
Connected Asset Maintenance
Maintenance is becoming one of the more important AI-driven expansion areas. Samsara collects diagnostic data, fault codes, vehicle inspections, work orders, OEM integrations, and maintenance inputs. Management said customers generate more than 300M vehicle inspection workflows annually. AI can predict fault severity, estimate repair cost, identify whether a fault may worsen, check warranty eligibility, and create work orders. In the demo, a fault could move from $100–$800 repair cost to around $3,900 if ignored. Customers spend about 10% of operating budget on maintenance, and large fleets may have $10M–$20M of warranty recovery opportunity. The challenge is proving agent ROI at scale and integrating with customer maintenance workflows.
Embedded AI
Samsara is moving from data collection to embedded AI and agentic automation. The company described three phases: data collection, AI insights, and agents taking action. Its data asset is large, with references to 60T+ and 90T data points collected over more than a decade across vehicles, equipment, cameras, workflows, diagnostics, and GPS. Emerging products already contribute >20% of net new ACV and are approaching ~$150M ARR. AI agents can automate safety coaching, ride-alongs, warranty checks, maintenance workflows, dispatch tasks, ETAs, shift compliance, weather alerts, and start-of-day briefings. The challenge is execution: agents must deliver measurable ROI, not just demos.
Waste Intelligence
Waste Intelligence opens a new vertical. Management described waste management as a $1.6T global industry and said Samsara already has seven-figure deals in the pipeline. The product connects garbage trucks, monitors pickup arms, adds up to 10 cameras, and uses AI to identify missed pickups, overfilled bins, contamination, and service exceptions. The value proposition is both cost reduction and revenue recovery: missed pickups create extra truck rolls, while overfilled bins and contamination can become billable events. The challenge is vertical specialization, because waste operations require deeper workflow integration than generic telematics.
Ground Intelligence
Ground Intelligence expands Samsara into public-sector infrastructure monitoring. The product uses existing cameras, vehicle data, G-force signals, and AI to detect potholes, broken guardrails, low-hanging branches, power lines, graffiti, encampments, and road defects. Management cited pothole-related damage around $3B and said Samsara vehicles drive 99% of U.S. roads, giving the company a strong data advantage. In Kalamazoo, Samsara detected 4,000 potholes from about 28,000 observations. This is attractive because it can be sold as software without new hardware deployment. The challenge is converting sensor coverage into repeatable public-sector budgets and contracts.
Product Innovation and Updates
Samsara introduced several major updates around AI, tracking, and operational intelligence. The most important launch is the Tracking Label AT11, a thin, flexible, disposable tag for one-way shipments. It lasts 45 days after activation, has about nine-month shelf life, contains no lithium or hazardous materials, and uses consumption pricing at a $15 list price per shipment before enterprise discounts. The product opens Samsara to shippers such as retail, electronics, automotive, pharmaceuticals, and high-value cargo logistics.
Samsara is also pushing new AI-native products: Maintenance Agent, AI-powered ride-along, two-way communication, Waste Intelligence, Ground Intelligence, multi-cam / 360-degree visibility, object and person detection, Agent Studio, and operational AI detections. The strategy is clear: use the installed hardware network as a data moat, then launch higher-value software and AI products on top. Core growth still comes from fleet, safety, and telematics, but the bigger story is TAM expansion from connected vehicles into connected physical operations.
6. Market Leadership
IOT Samsara has established commanding market leadership positions across numerous IoT and connected operations categories. G2’s Summer 2025 Report awarded Samsara the No.1 Leader position in Fleet Management, marking another consecutive recognition based on thousands of verified user reviews. The company uniquely leads three critical categories simultaneously: Fleet Management, Fleet Tracking, and Video Surveillance—an achievement no other platform has replicated.

Trusted Brand Leadership. A 2025 industry study ranked Samsara the most trusted brand in fleet management technology. 83% of customers reported high satisfaction and 90% are likely to recommend. Samsara leads in customer service, brand awareness, and overall satisfaction, proving its reputation as the top choice for large-scale fleet operators.

Fleet managers rated Samsara highest for customer support and service, the single most crucial factor in purchasing decisions with 85% of respondents considering it extremely or very important. Samsara achieved 83% satisfaction in support and service, outperforming all competitors in the study including Geotab, Motive, and Lytx. Overall satisfaction reached 84% for Samsara compared to Geotab at 76%, Motive at 70%, and Lytx at 68%—an eight percentage point lead over the nearest competitor.

Independent research firm IDC published a comprehensive business value study in June 2024 quantifying Samsara’s customer impact. Organizations using Samsara realized average annual benefits worth $2.02 million per organization, translating to an 815% return on investment. Customers reduced overall vehicle fleet operating costs by 6%, achieved 29% fewer crashes, extended vehicle lifespan by 10%, lowered fuel costs by 4%, and reduced maintenance costs by 9%.

7. Customers
IOT Samsara added 169 new customers with $100K+ ARR in Q1, a record level of additions for a first quarter, which is seasonally weak for the company. This represented +27% YoY growth.
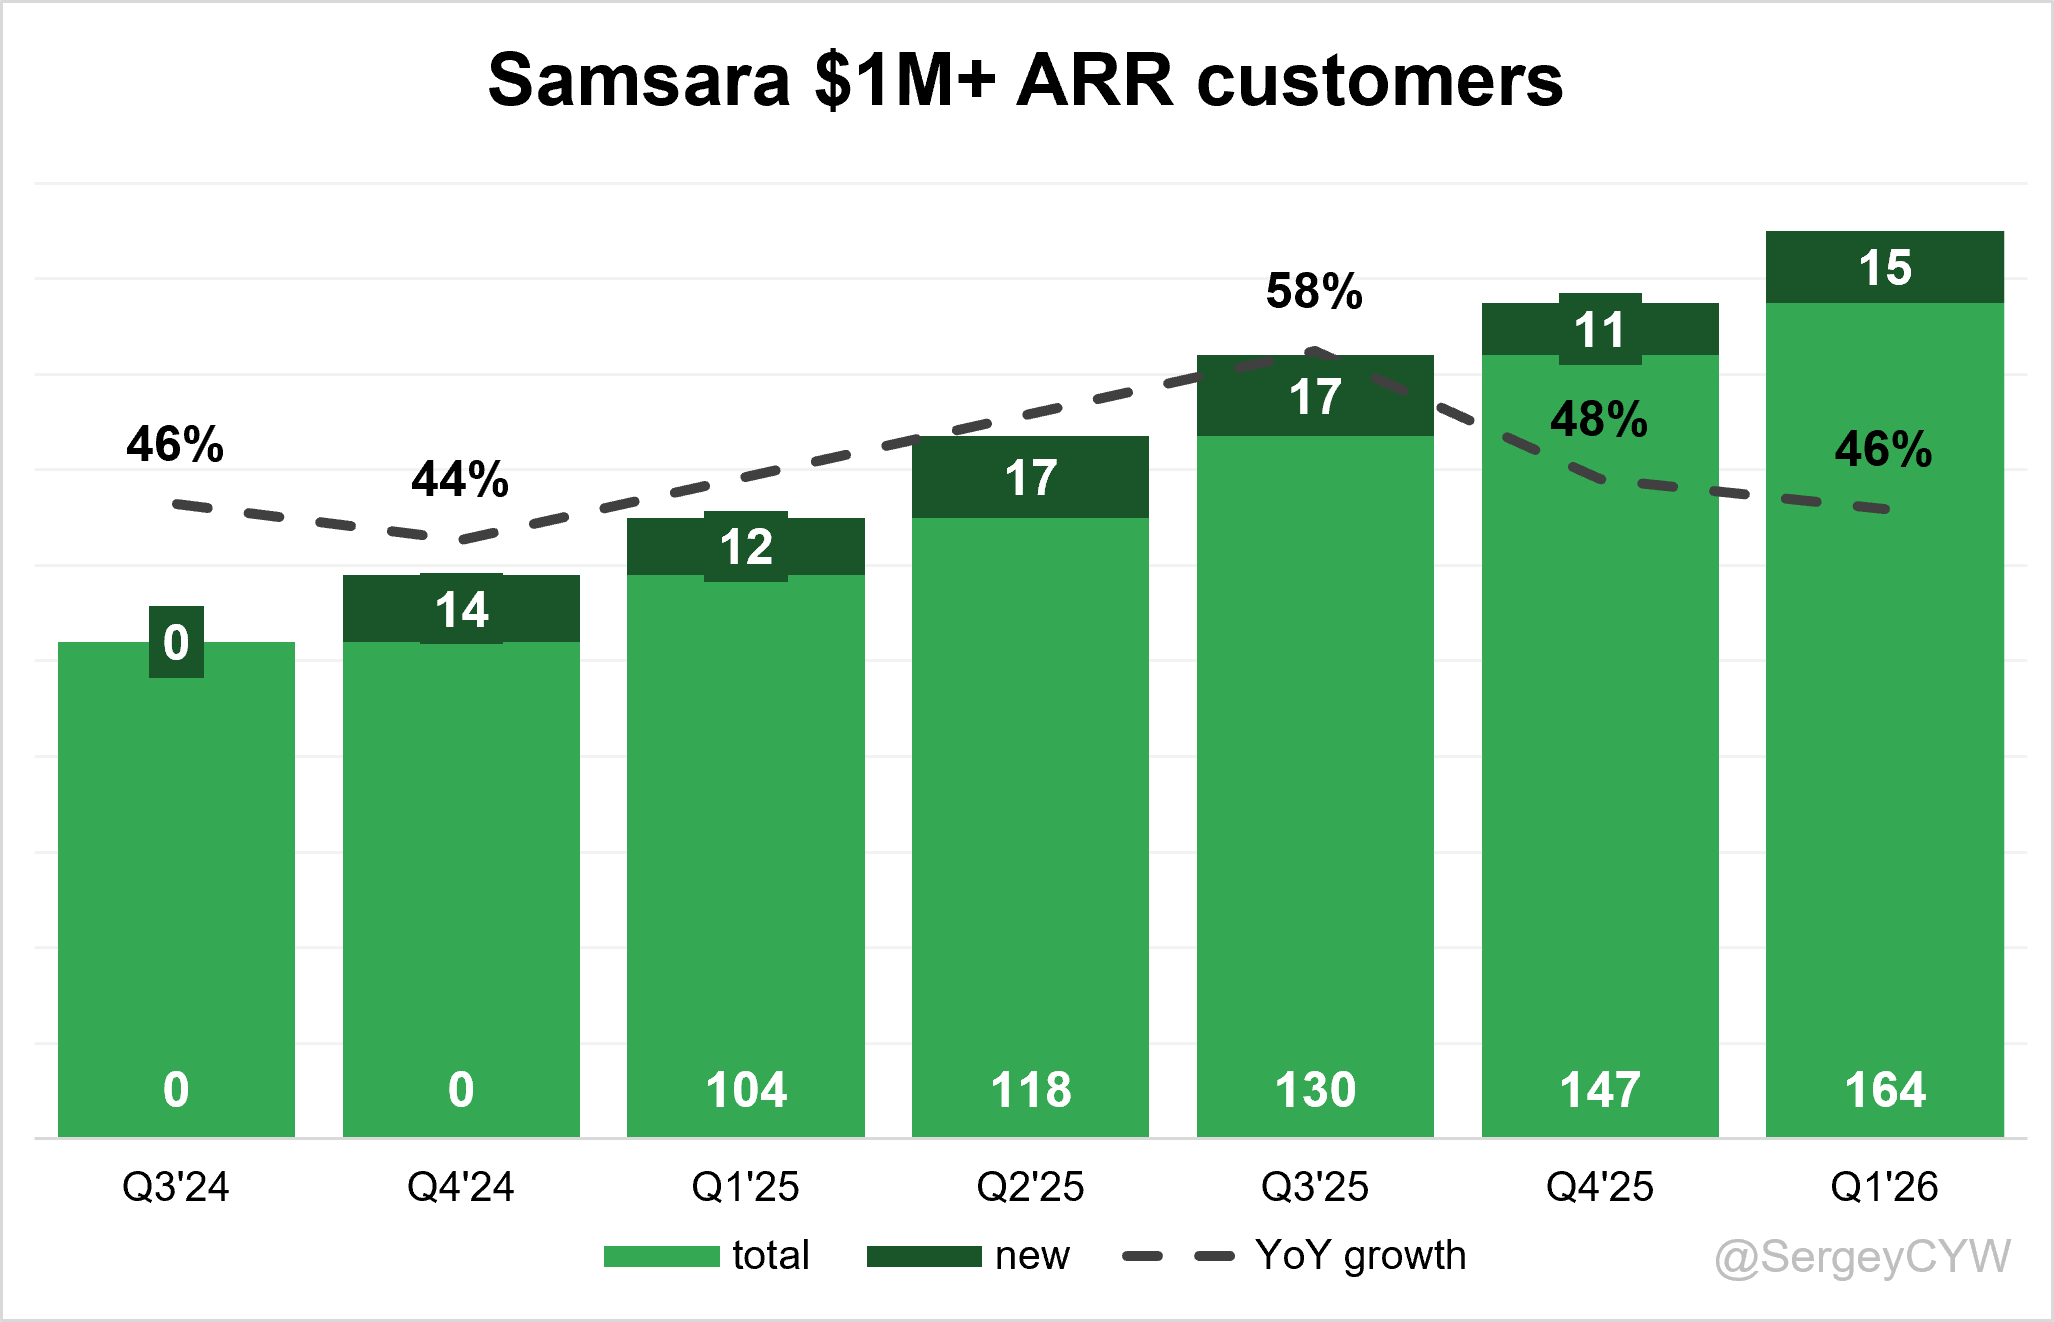
Samsara also added 15 customers with more than $1 million in ARR, which was also a quarterly record, representing +46% YoY growth.
Customer Success Stories
Samsara’s strongest customer success stories center on measurable operating savings, not abstract AI adoption. Management highlighted examples where customers reduced major cost lines across fuel, insurance, maintenance, claims, and driver safety.
One customer saved $3M in fuel costs, showing the value of better fleet visibility, idling reduction, route efficiency, and driver behavior analytics. Fuel is a large operating expense for physical operations customers, especially when pump prices rise 30%–40%, so even small efficiency gains can translate into material savings.
Another customer, USC, achieved a 98% reduction in insurance claims. For Samsara, this is one of the clearest ROI narratives because safety software links directly to fewer incidents, better documentation, faster exoneration, and lower claims exposure.
Maxim Crane saved $13M on maintenance costs, showing the value of asset visibility, preventive maintenance, utilization data, and faster issue detection. Maintenance matters because customers can spend around 10% of operating budgets on it, and large fleets often lose money through missed warranty claims, avoidable downtime, and delayed repairs.
The broader ROI framework is also strong. Samsara cited an IDC study showing roughly 8x ROI from better equipment utilization, maintenance efficiency, fuel savings, and accident-cost reduction. With AI agents, management believes ROI can increase to 8x–10x or more, especially through task automation and warranty recovery.
Primoris is a utility-scale contractor operating across renewables, solar, power generation, and heavy civil infrastructure. The company has roughly 24,000 pieces of equipment, including 8,000 rolling stock units with dual-facing cameras.
Primoris uses Samsara across safety, GPS telematics, yellow iron, trailer tracking, and asset tracking. The strategic value is data aggregation. The company operates equipment from many OEMs, and Samsara acts as a common operating layer across fragmented systems.
The safety impact is material. Primoris reported 66% reduction in total events, 40% reduction in severe speeding, and 42% reduction in crashes across its fleet. Management said this translates into roughly $5M per year in savings from crashes and claims.
Primoris also reduced idling by 30%, creating additional fuel savings. With current fuel costs, management described the savings as “millions of dollars.” The success story is not only financial. Primoris also used dashcam evidence to exonerate drivers and improve employee adoption, which helped overcome early concerns around monitoring and privacy.
Performance Food Group is a Fortune 100 foodservice distributor with more than $60B in annual revenue, 43,000 employees, more than 150 locations, and service to over 300,000 customer locations. Transportation scale is large, with about 12,000 delivery associates and roughly the same number of vehicles.
PFG uses Samsara for safety, environmental monitoring, door sensors, temperature sensors, and trailer storage visibility. Food safety is a key use case because refrigerated and frozen goods require monitoring and compliance. Samsara replaced manual trailer checks that previously required workers to inspect refrigeration units every four hours, around the clock, for months.
The safety results are strong. Over three years, PFG reported a 26% decrease in total event rates, 60% decrease in collision risks, 70% reduction in traffic signal and sign events, 23% reduction in harsh events, 90% reduction in speeding over 10 mph, and 33% improvement in seat belt behavior.
The insurance impact is meaningful. PFG expected insurance costs to increase by $20M, but only needed to spend $10M. Dashcam footage, exoneration, and driver coaching were key contributors. Management said the system can pay for itself through exonerations alone.
PFG also highlighted drowsy detection as a critical AI use case. After early alerts, the company pulled six drivers off the road for fitness testing. All six were diagnosed with obstructive sleep apnea, received treatment, and did not repeat drowsy events afterward. This is a strong example of AI improving safety, liability exposure, and driver health at the same time.
Large Customer Wins
Enterprise account size is expanding. Samsara’s 10th largest customer now pays $6.6M ARR, up 4.4x from $1.5M five years ago and up almost 1.5x in the last year alone. The 25th largest customer pays $4.2M ARR, up 5.3x over five years. The 100th largest customer now pays $1.5M ARR, equal to the size of the 10th largest customer five years ago.
Large customer wins are driven by phased deployments and multi-product adoption. One major home improvement customer started in 2019 with safety and telematics, then added asset gateways, asset tags, and Connected Workflows over time. This shows the standard enterprise path: small initial land, operational proof, broader rollout, then product expansion.
8. KPI
Retention
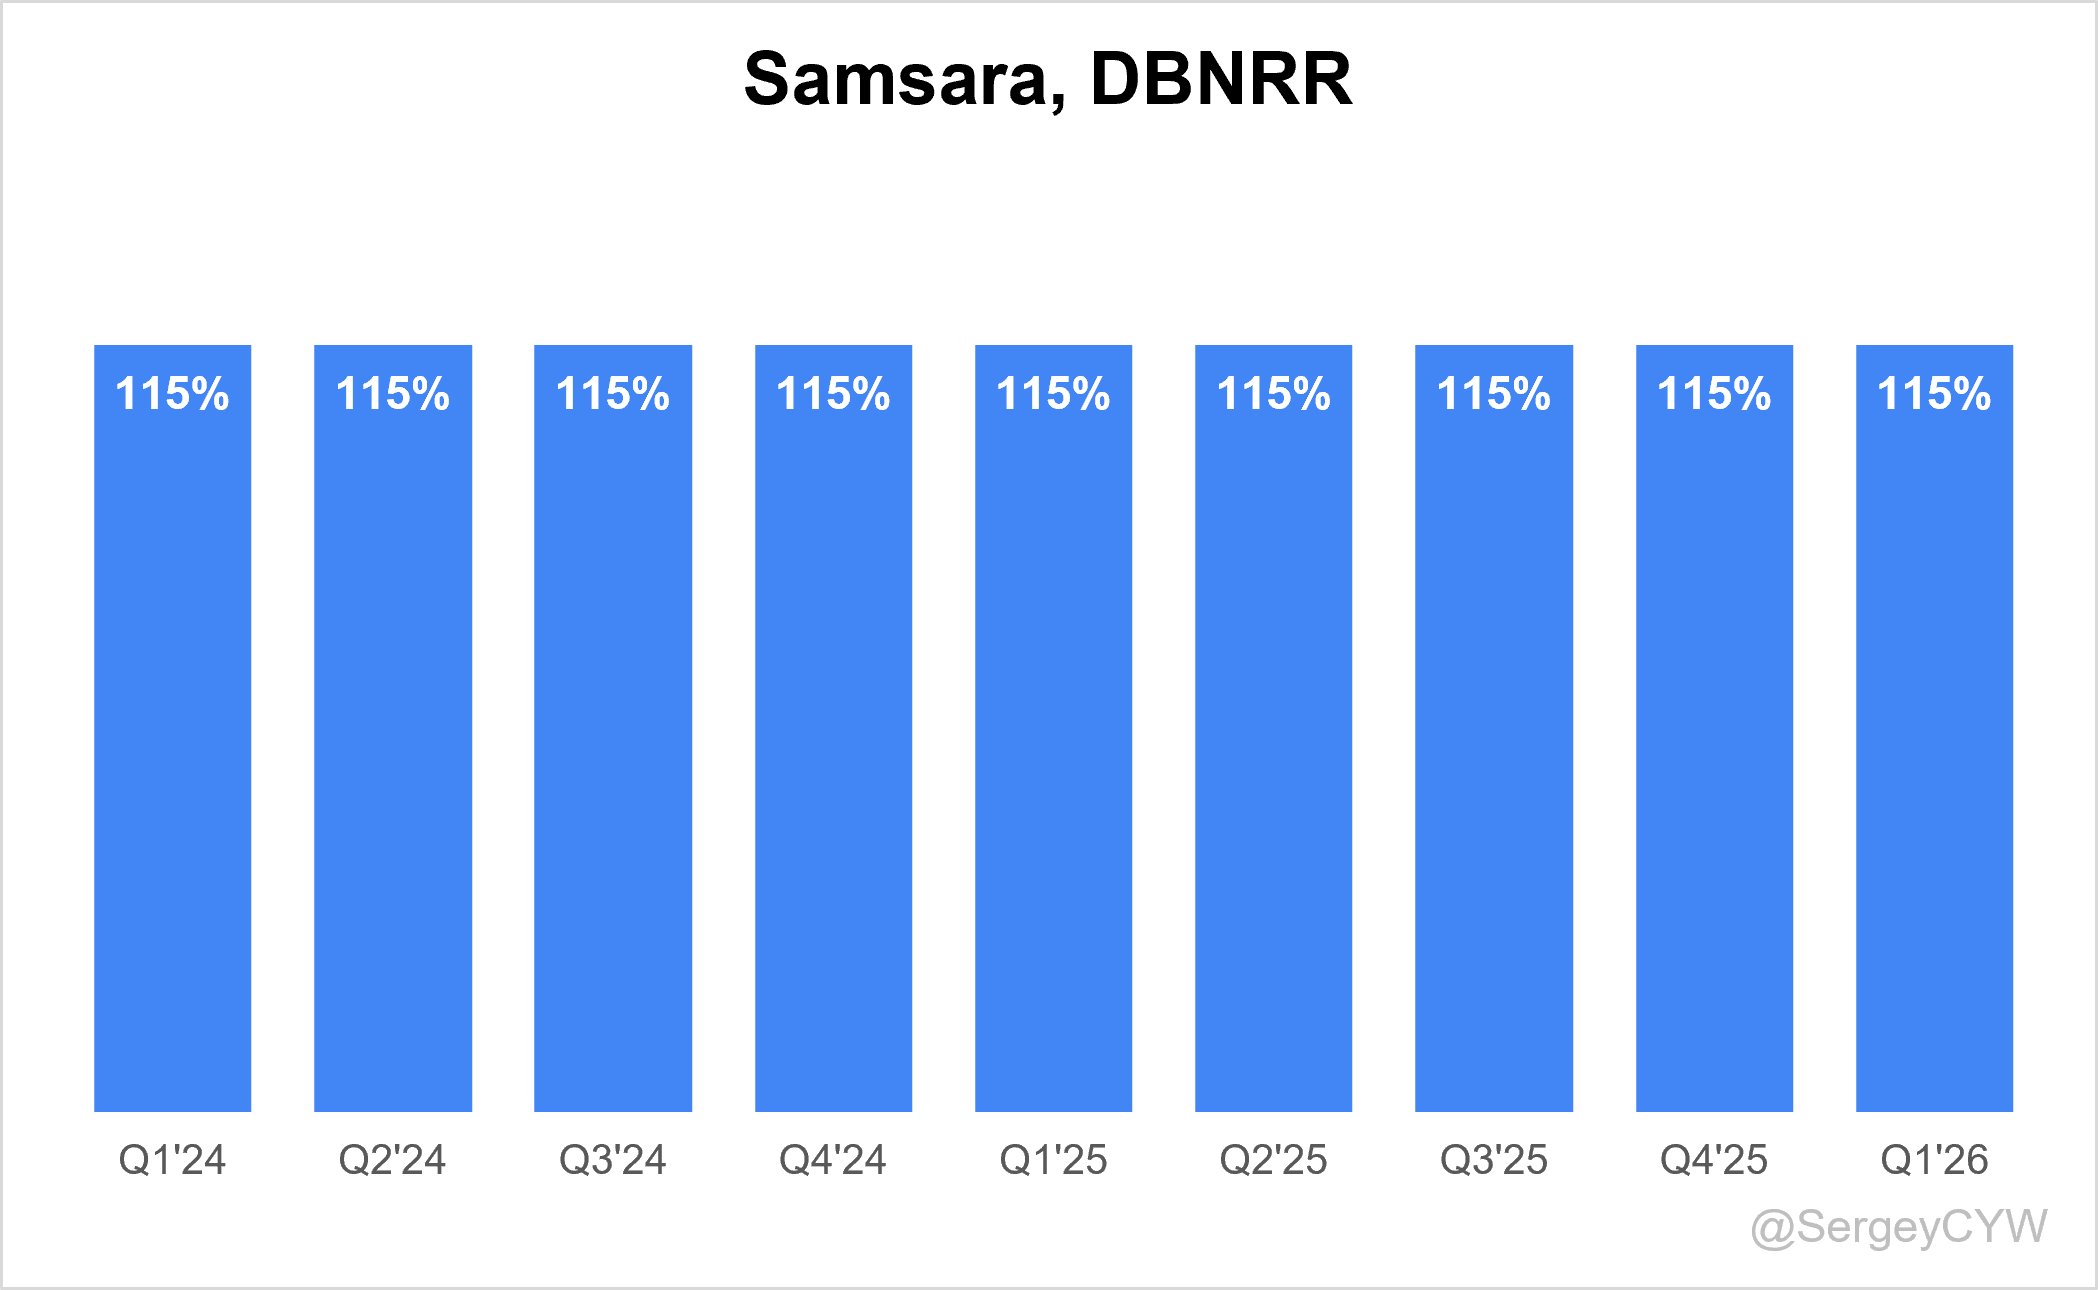
IOT Samsara reported a Net Revenue Retention (NRR) of 115% for customers with ARR over $10K.
For customers with ARR over $100K, NRR stood at 120% in Q4 FY2024. In Q2 FY2025, management did not provide updated NRR data for large customers.
For context, the median NRR among SaaS companies I track is around 118%, so Samsara remains competitive on retention metrics.
ARR Growth
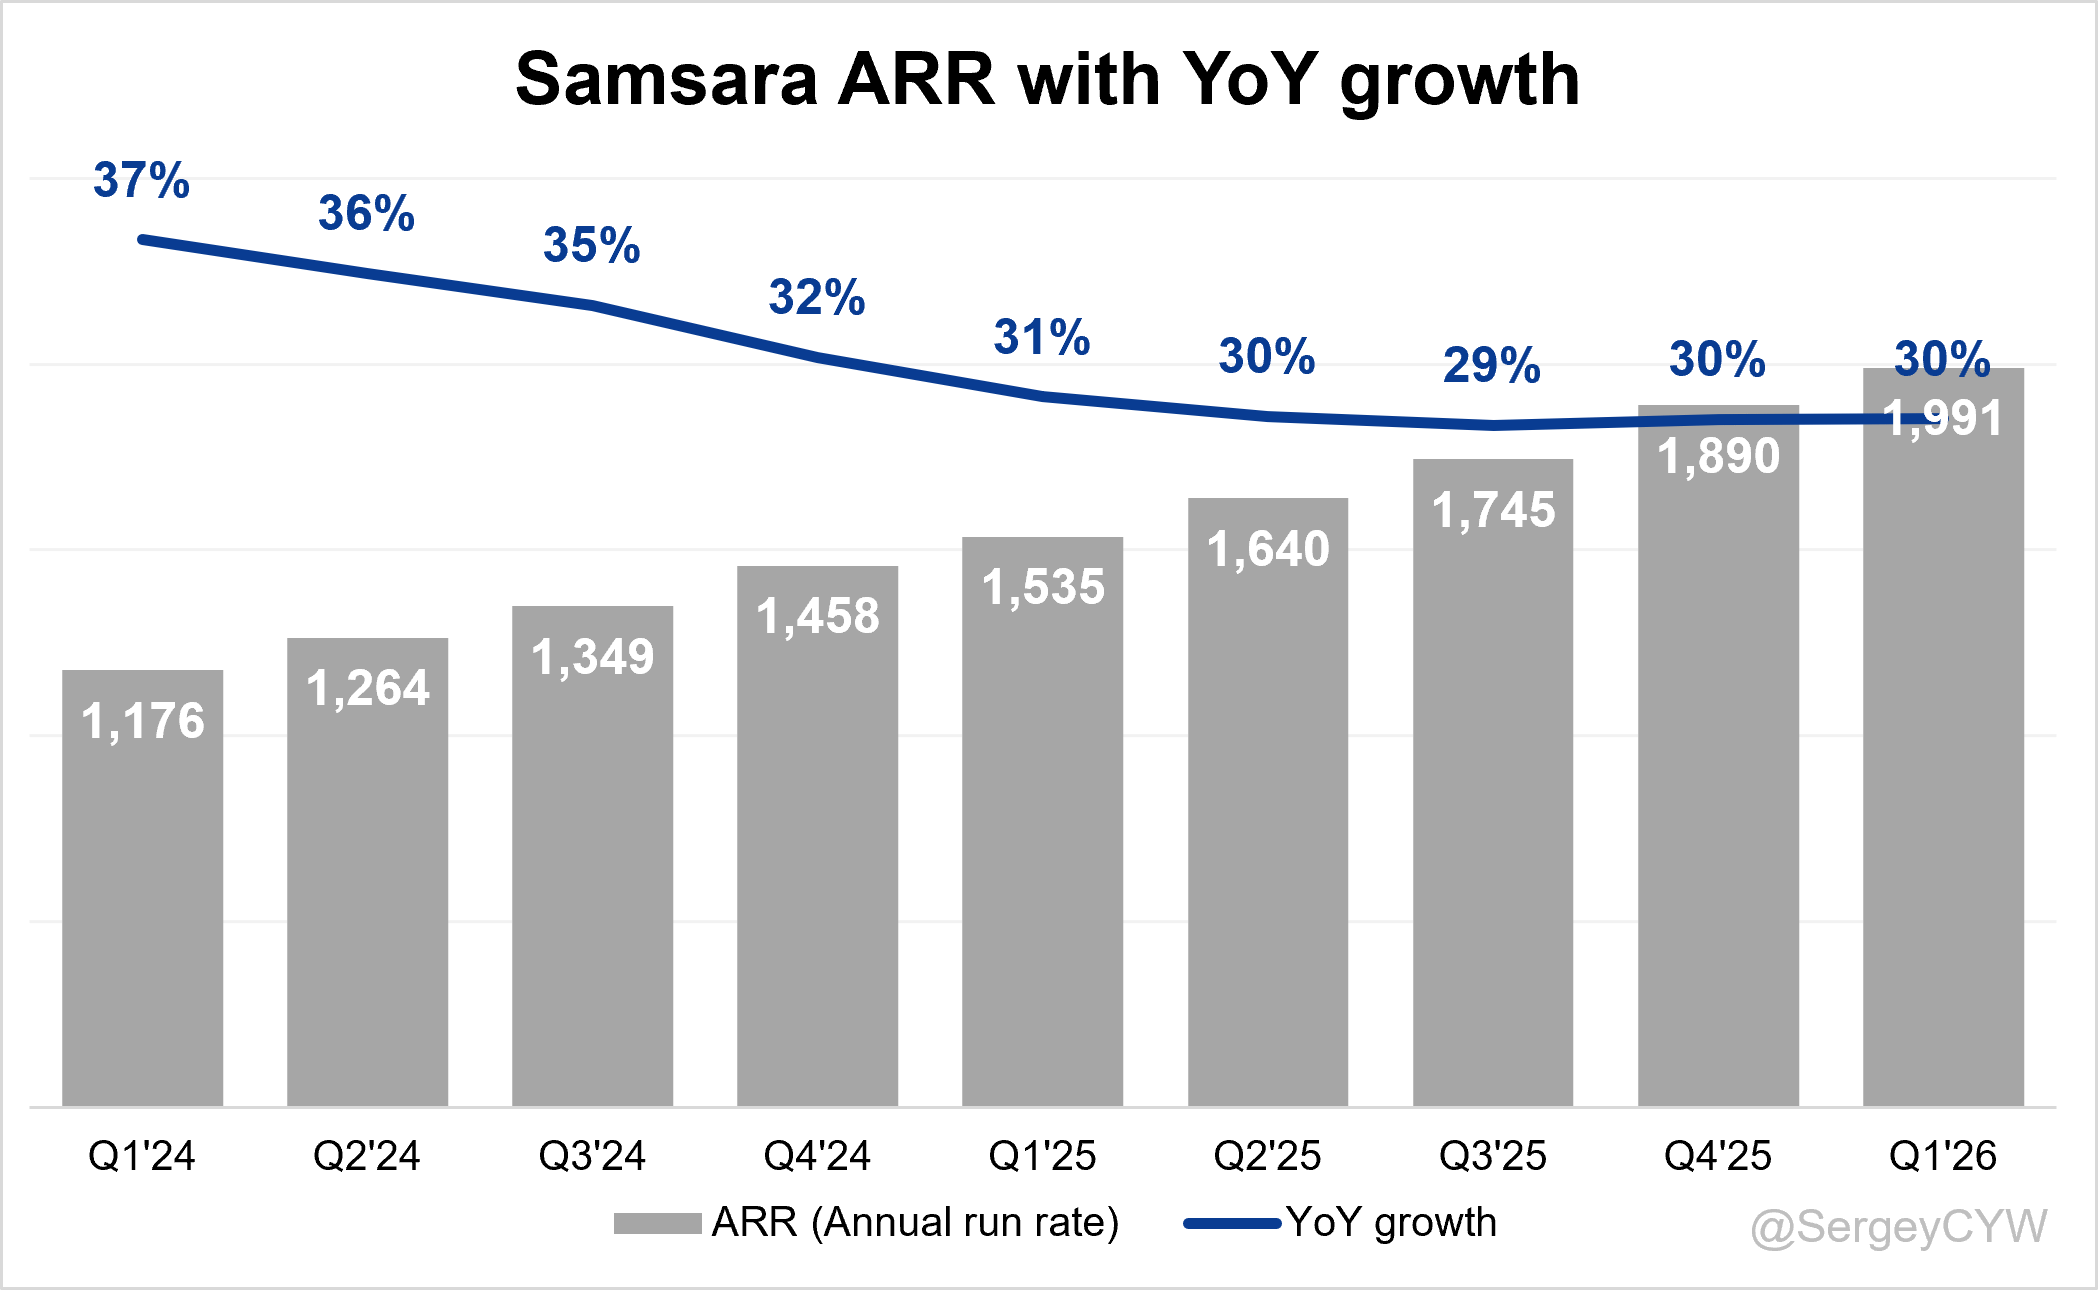
Samsara's Annual Recurring Revenue (ARR) growth stabilized at +29.6% YoY in Q1, roughly in line with the company's revenue growth.
Net new ARR
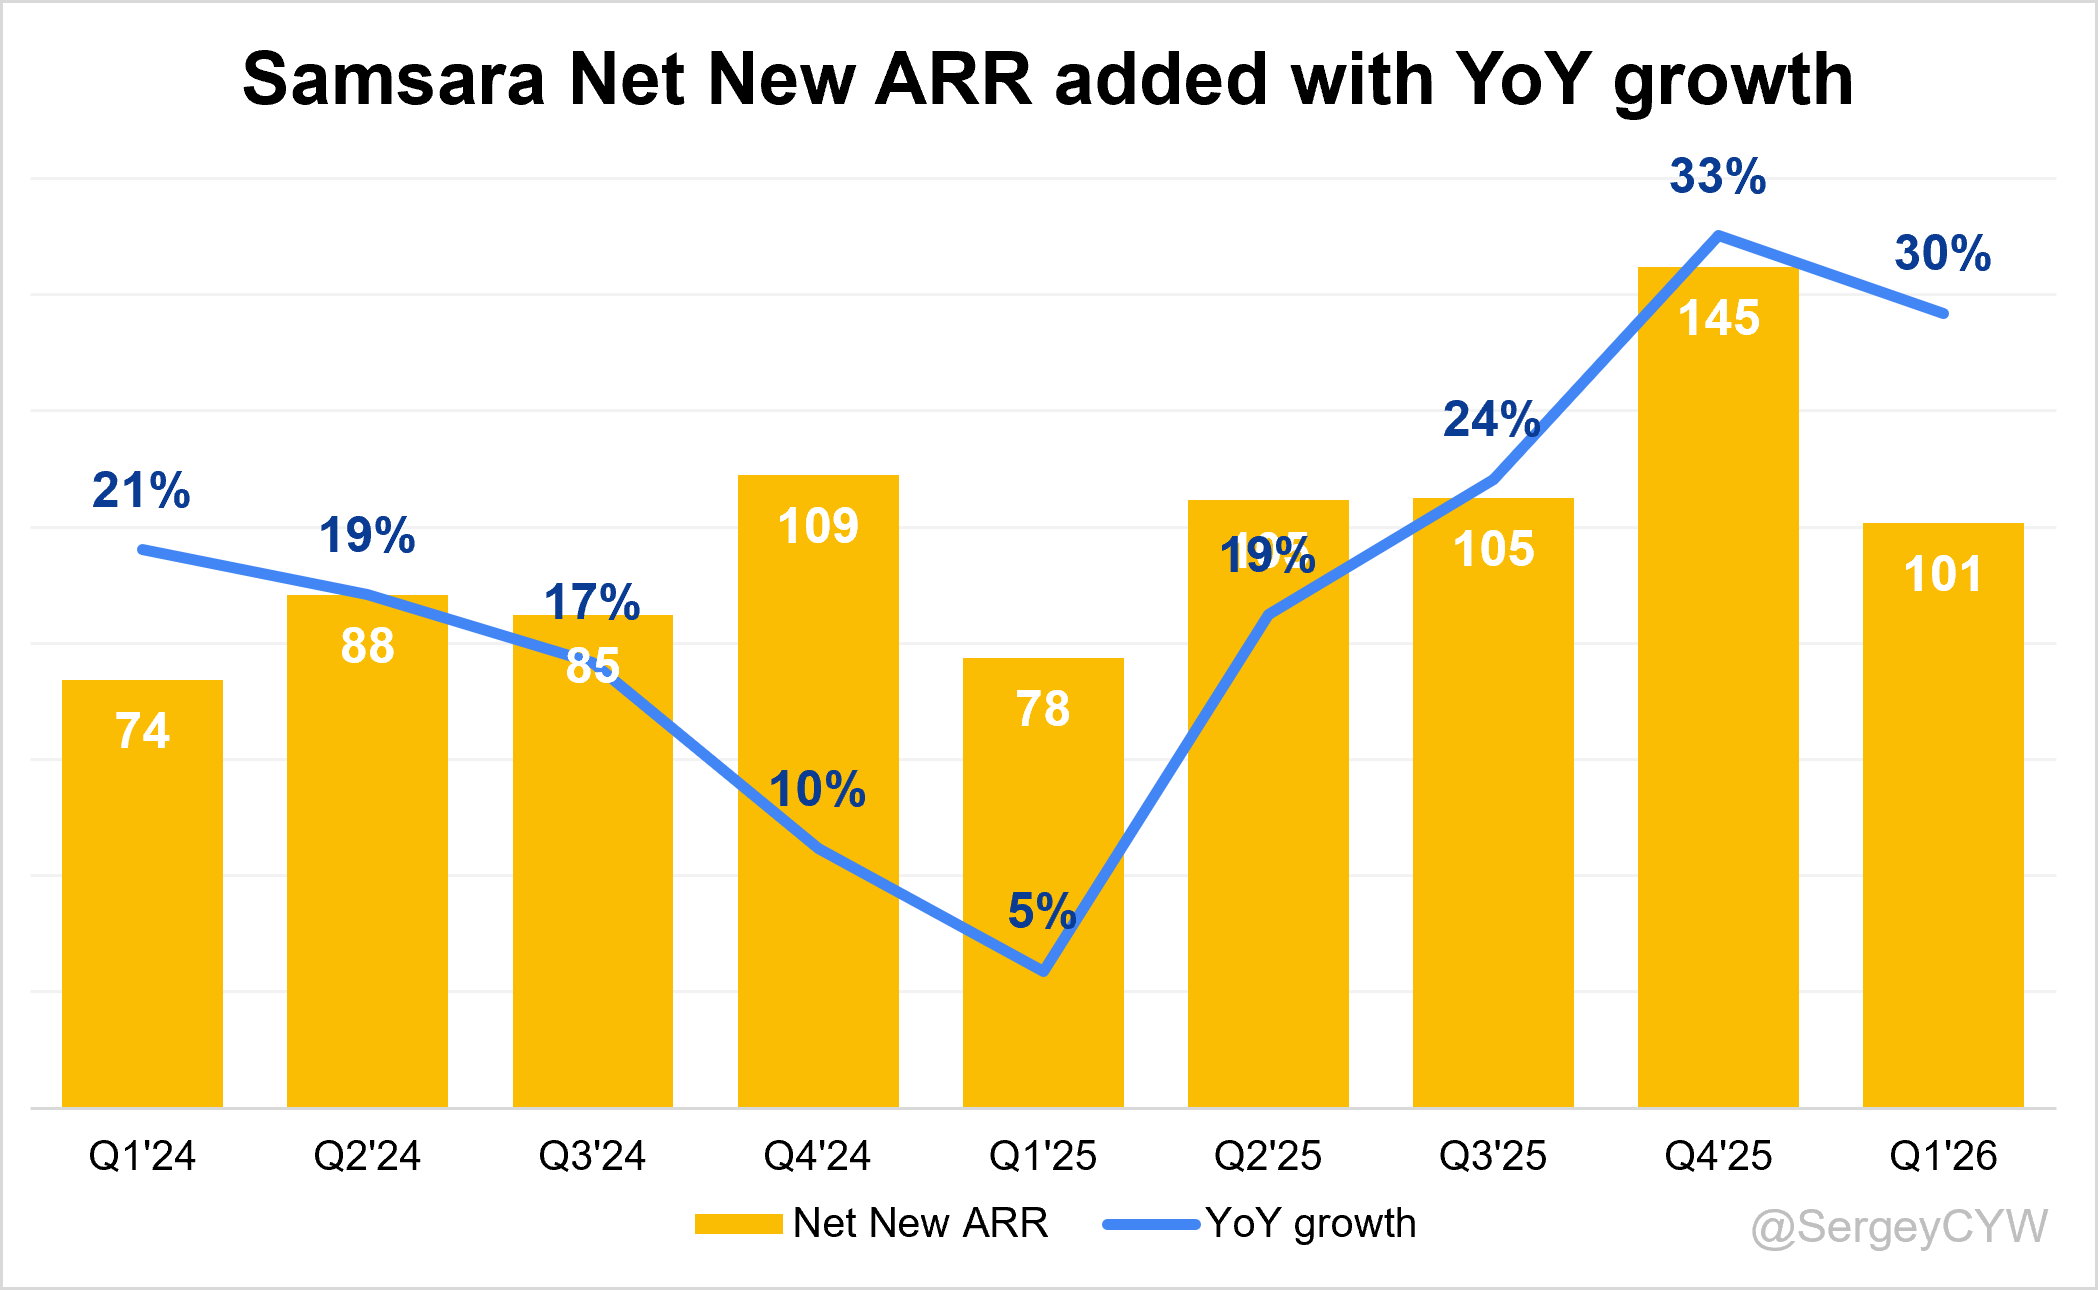
IOT Samsara added $101 million in net new ARR for Q1 2026, which is 30% higher than the previous year. Net new ARR addition at record level for Q1.
CAC Payback Period and RDI Score
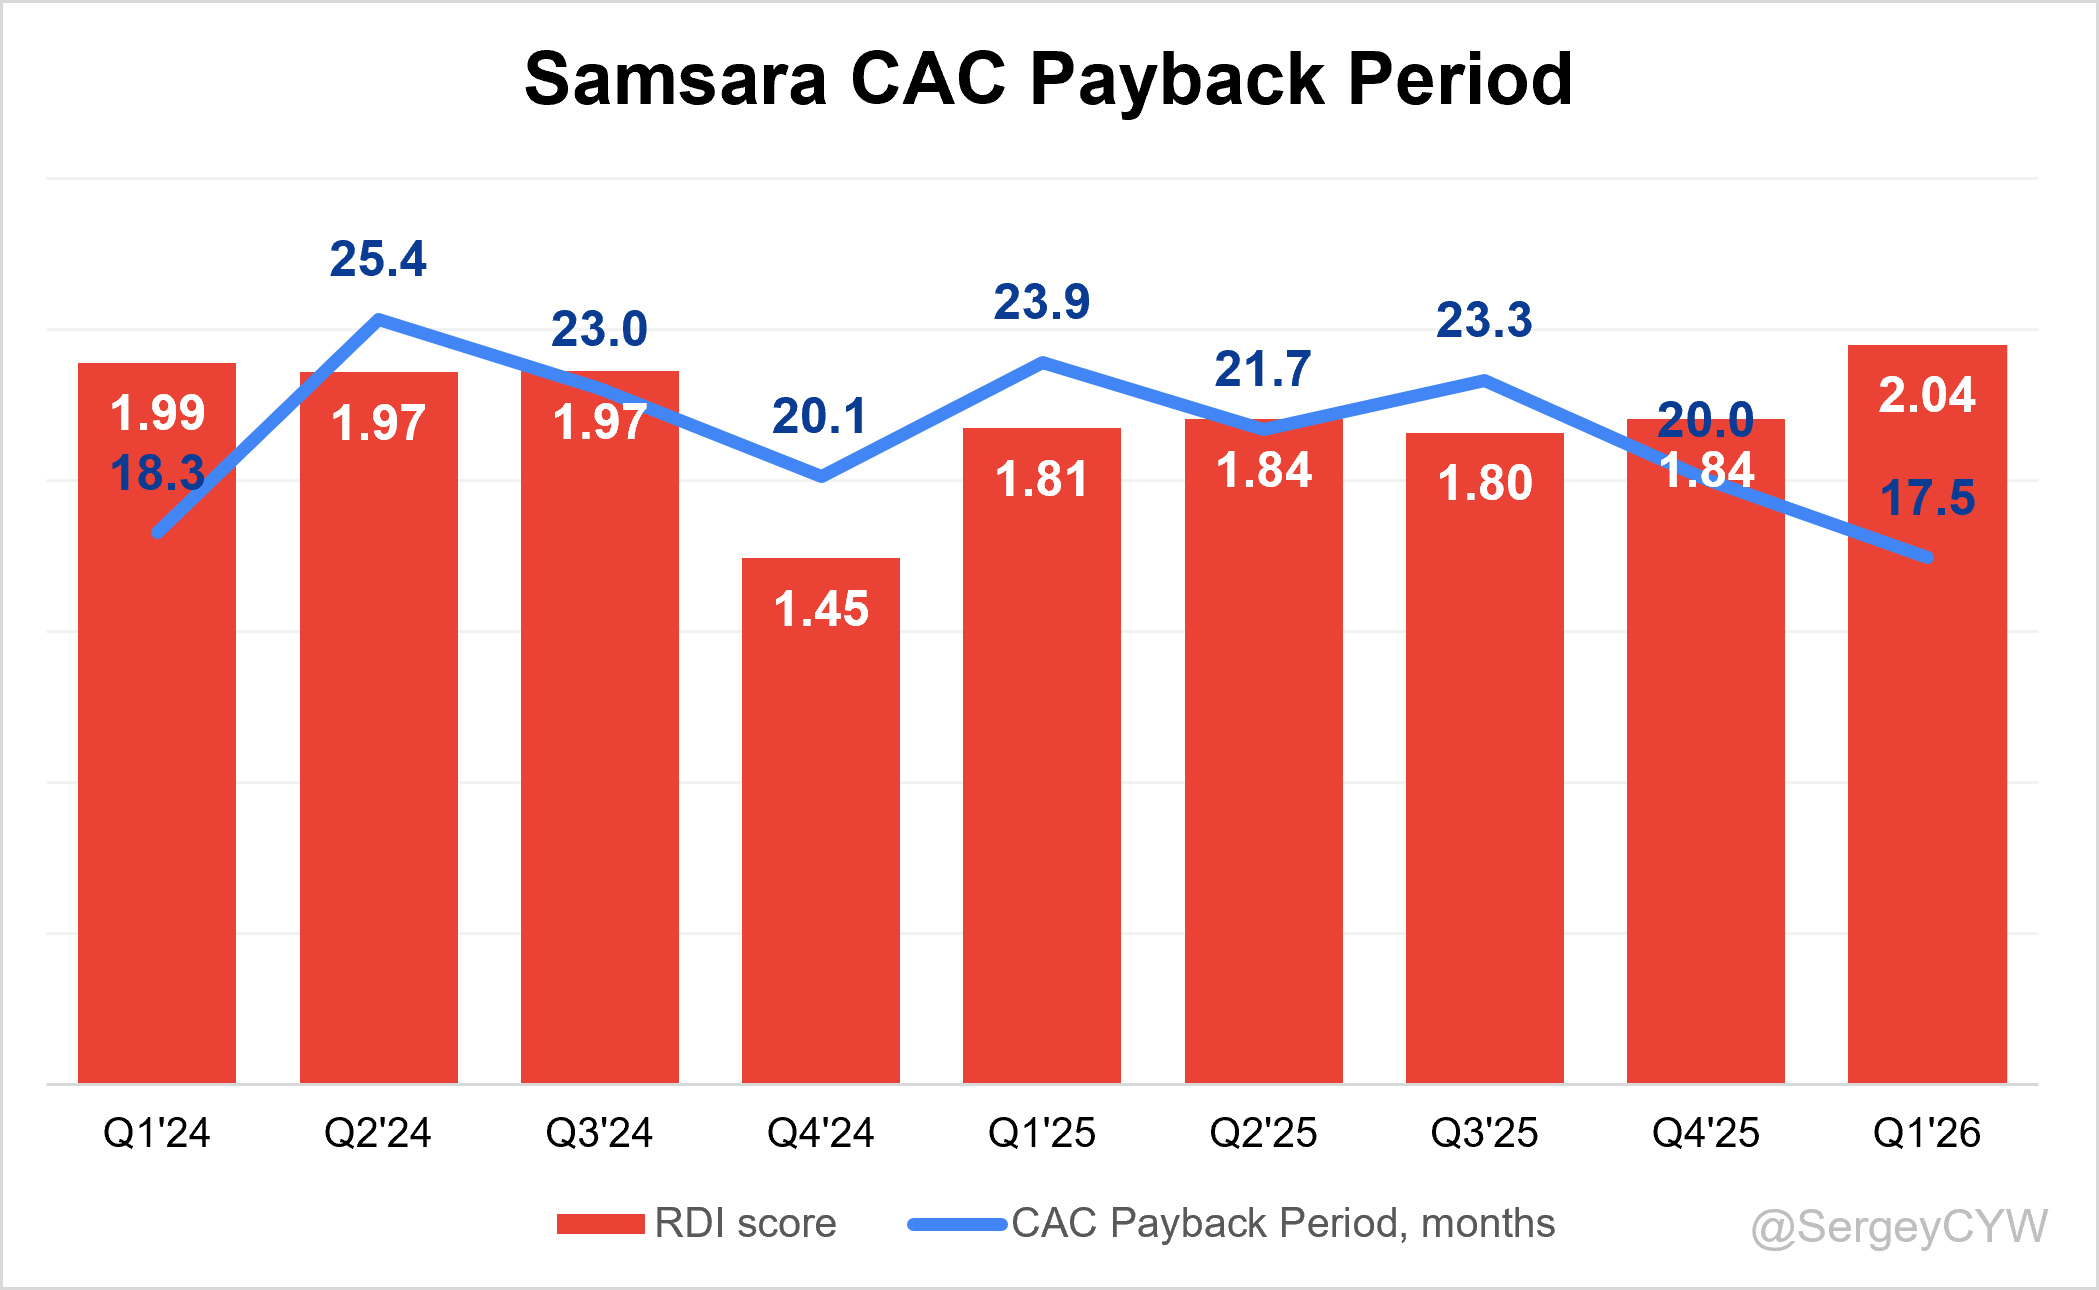
IOT Samsara’s return on S&M spending improved to 17.5 months, compared with a median CAC Payback Period of 22.9 months for the SaaS companies I track, indicating a healthy level of sales efficiency.
The R&D Index (RDI Score) increased to 2.04 in Q1, up from 1.84 in Q4 2025. This is well above the SaaS median of 1.4 and significantly higher than the industry median of 0.7, reflecting strong and consistent investment in innovation.
An RDI Score above 1.4 is considered indicative of best-in-class performance. The industry median of 0.7 highlights the importance of efficient R&D investment.
Profitability
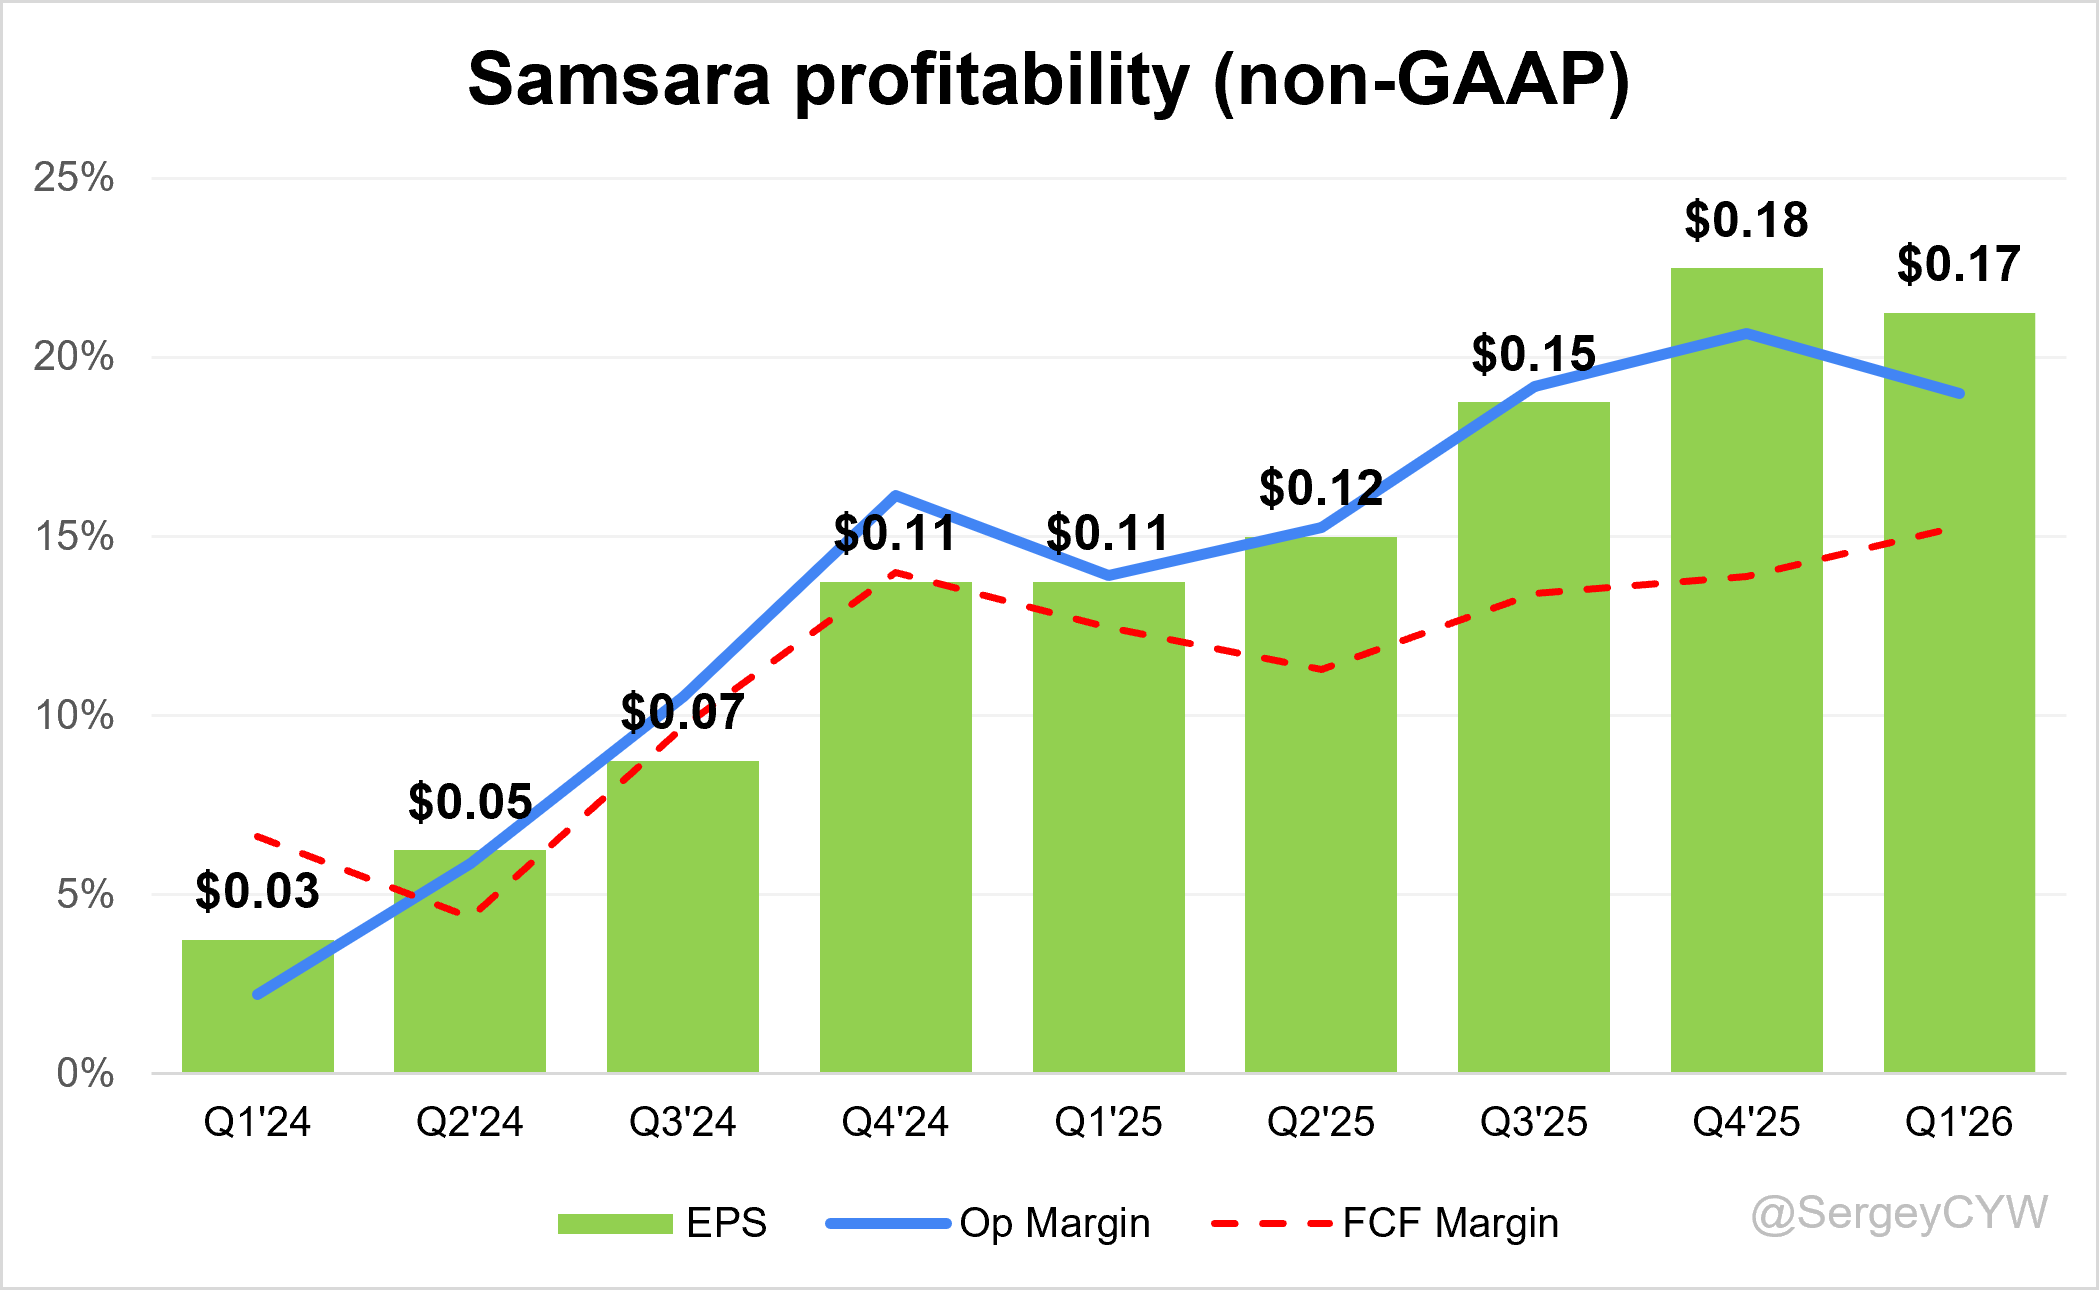
Over the past year, IOT Samsara margins has changed:
Gross Margin decreased from 78.5% to 76.5%.
Operating Margin increased from 13.9% to 19.0%.
FCF margin increased from 12.4% to 15.3%.
Operating expenses
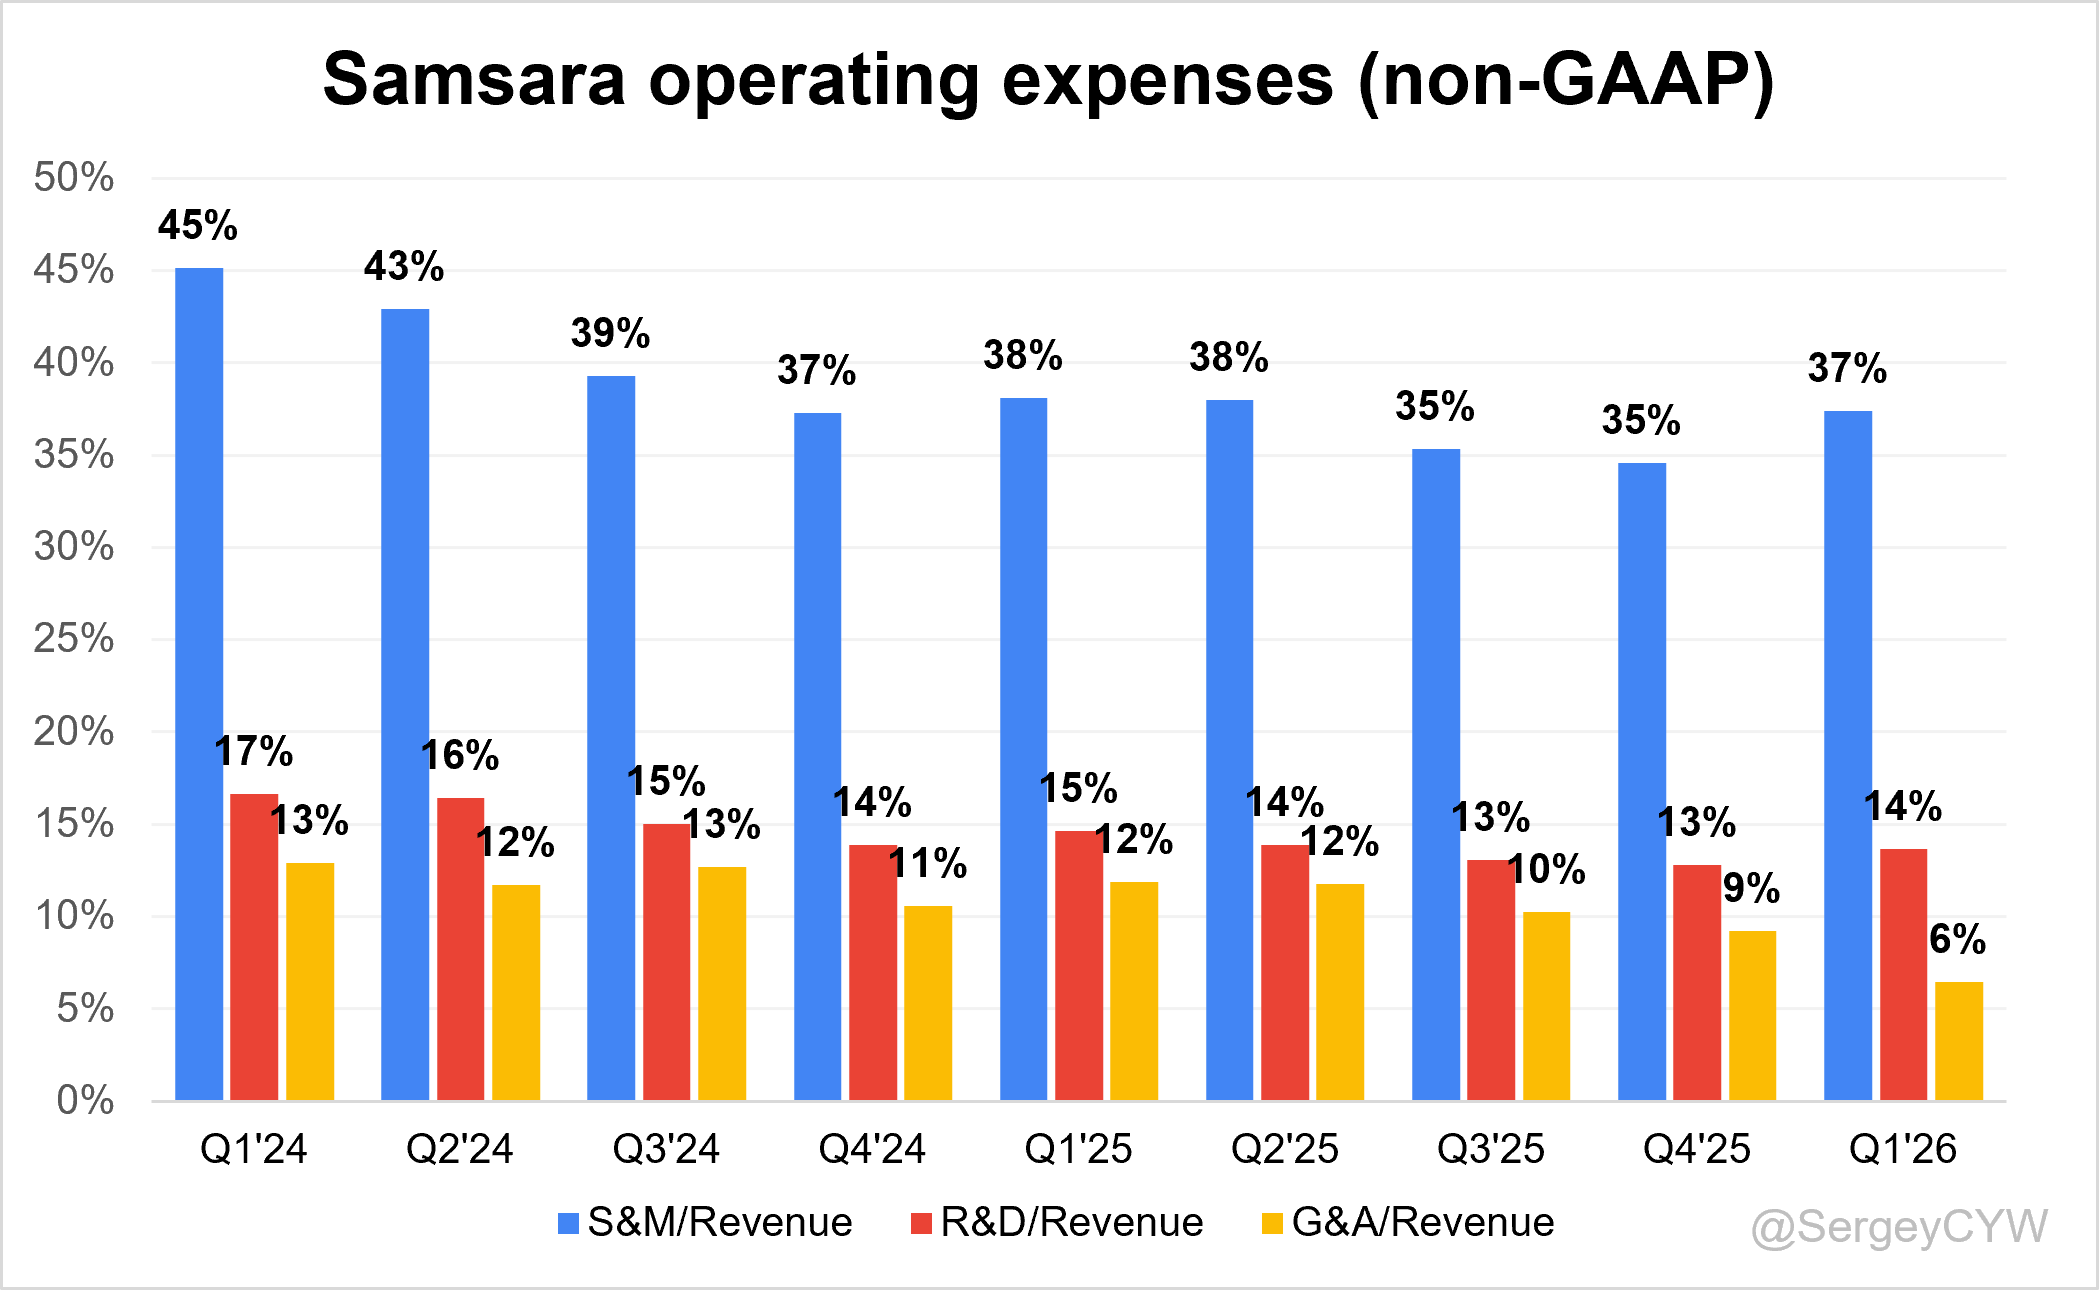
IOT Samsara has seen a gradual decline in non-GAAP operating expenses, primarily driven by a reduction in Sales & Marketing (S&M) spend.
S&M expenses dropped from 45% to 37% over the past two years, showing improved efficiency.
R&D remains elevated at 14%, though down from 17%, reflecting Samsara’s continued investment in innovation and long-term product development.
General & Administrative (G&A) expenses also declined to 6%, down from 13%, contributing to overall margin improvement.
Balance Sheet
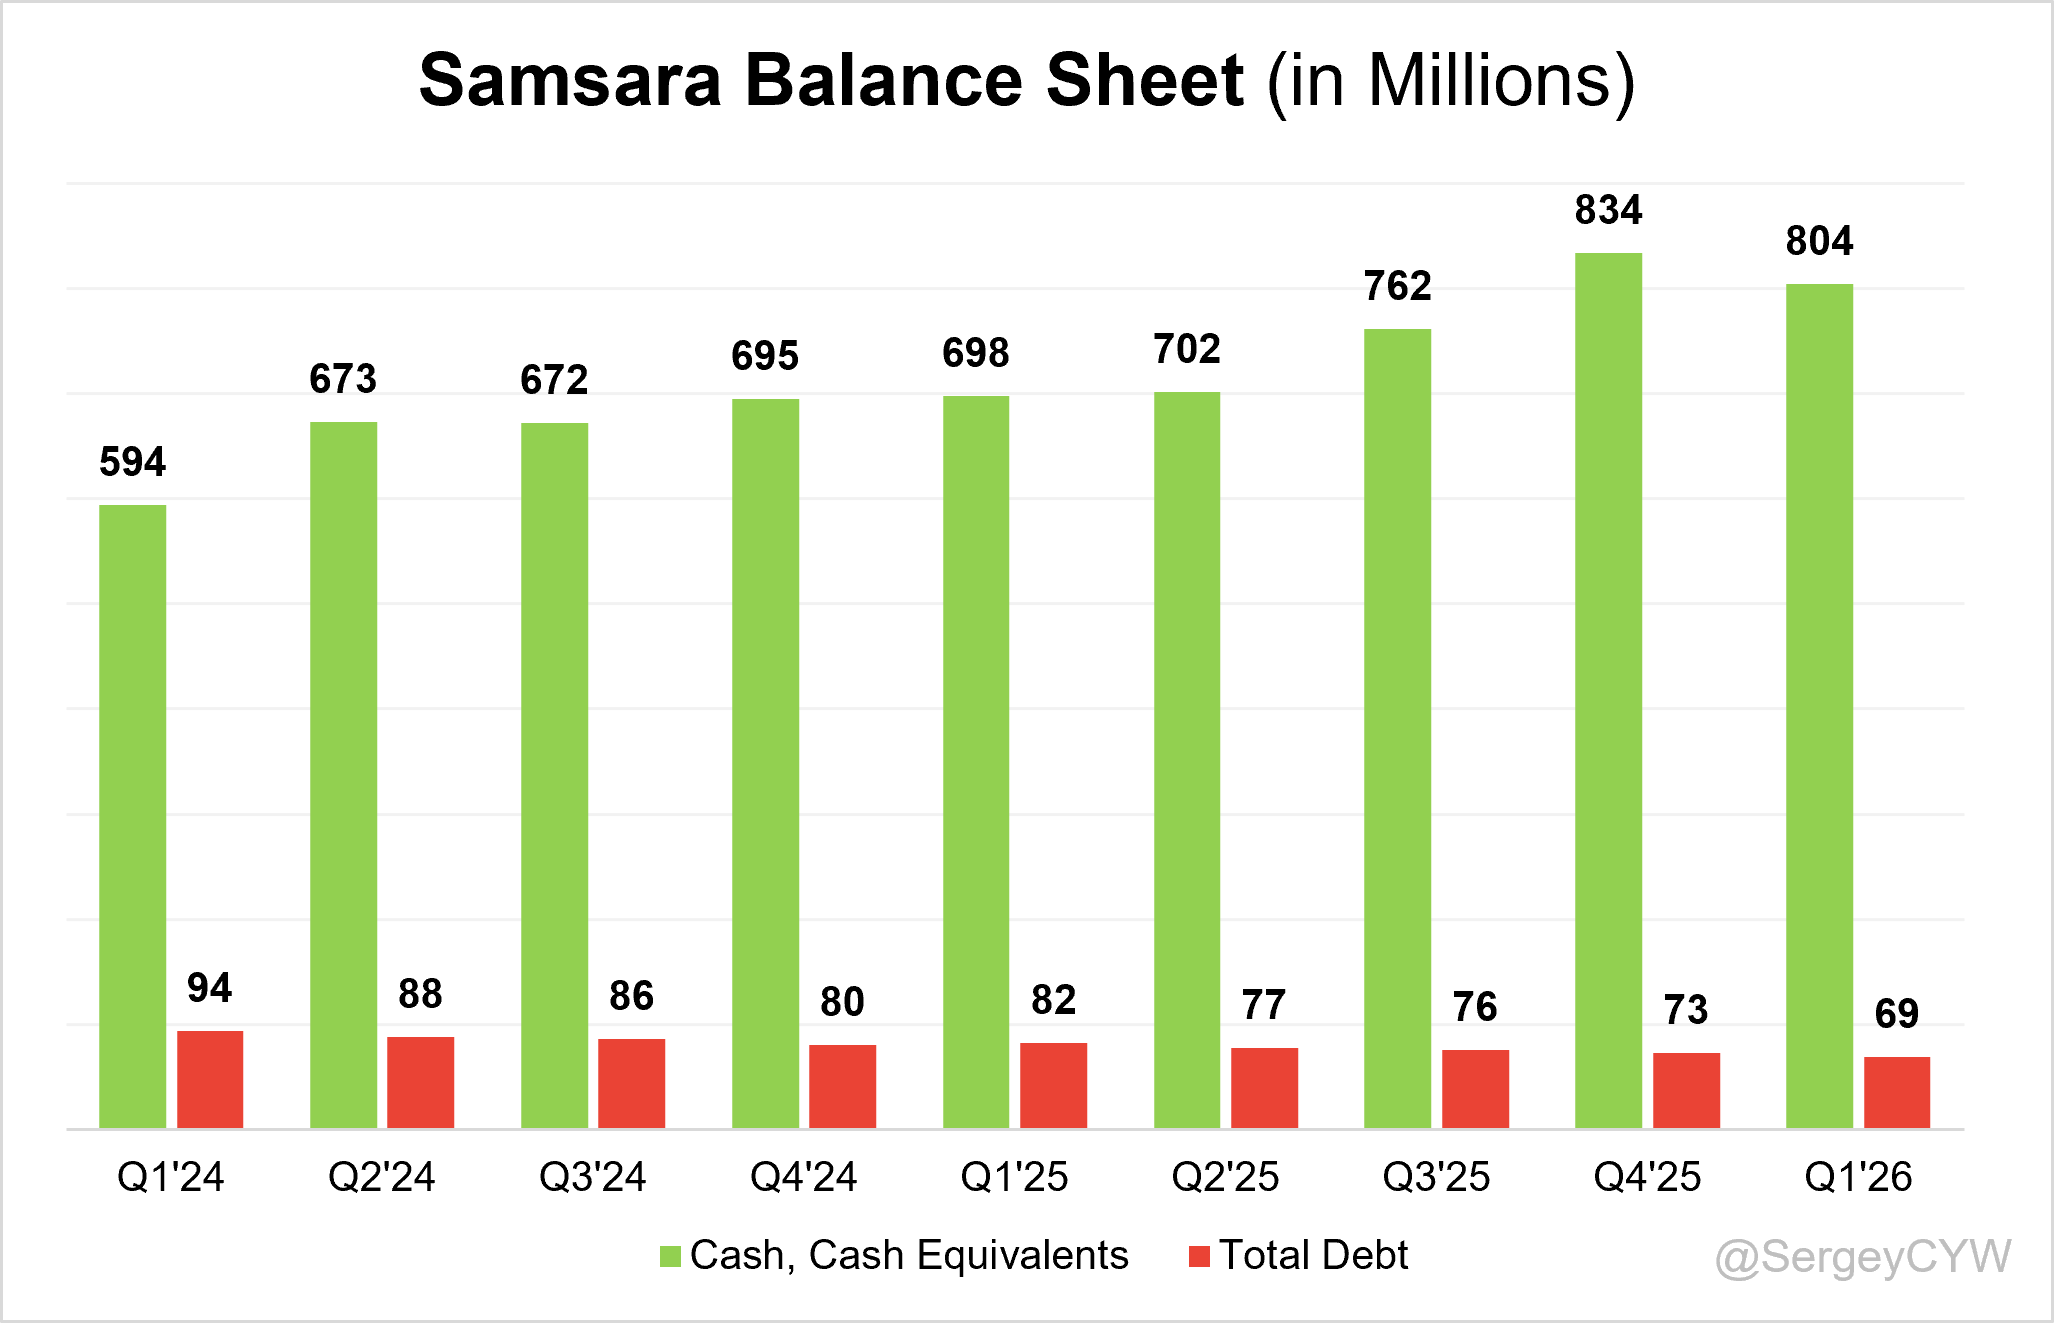
IOT Balance Sheet: Total debt stands at $69M, while Samsara holds $804M in cash and cash equivalents, exceeding its total debt and ensuring a healthy balance sheet reflects a virtually debt-free balance sheet.
Dilution
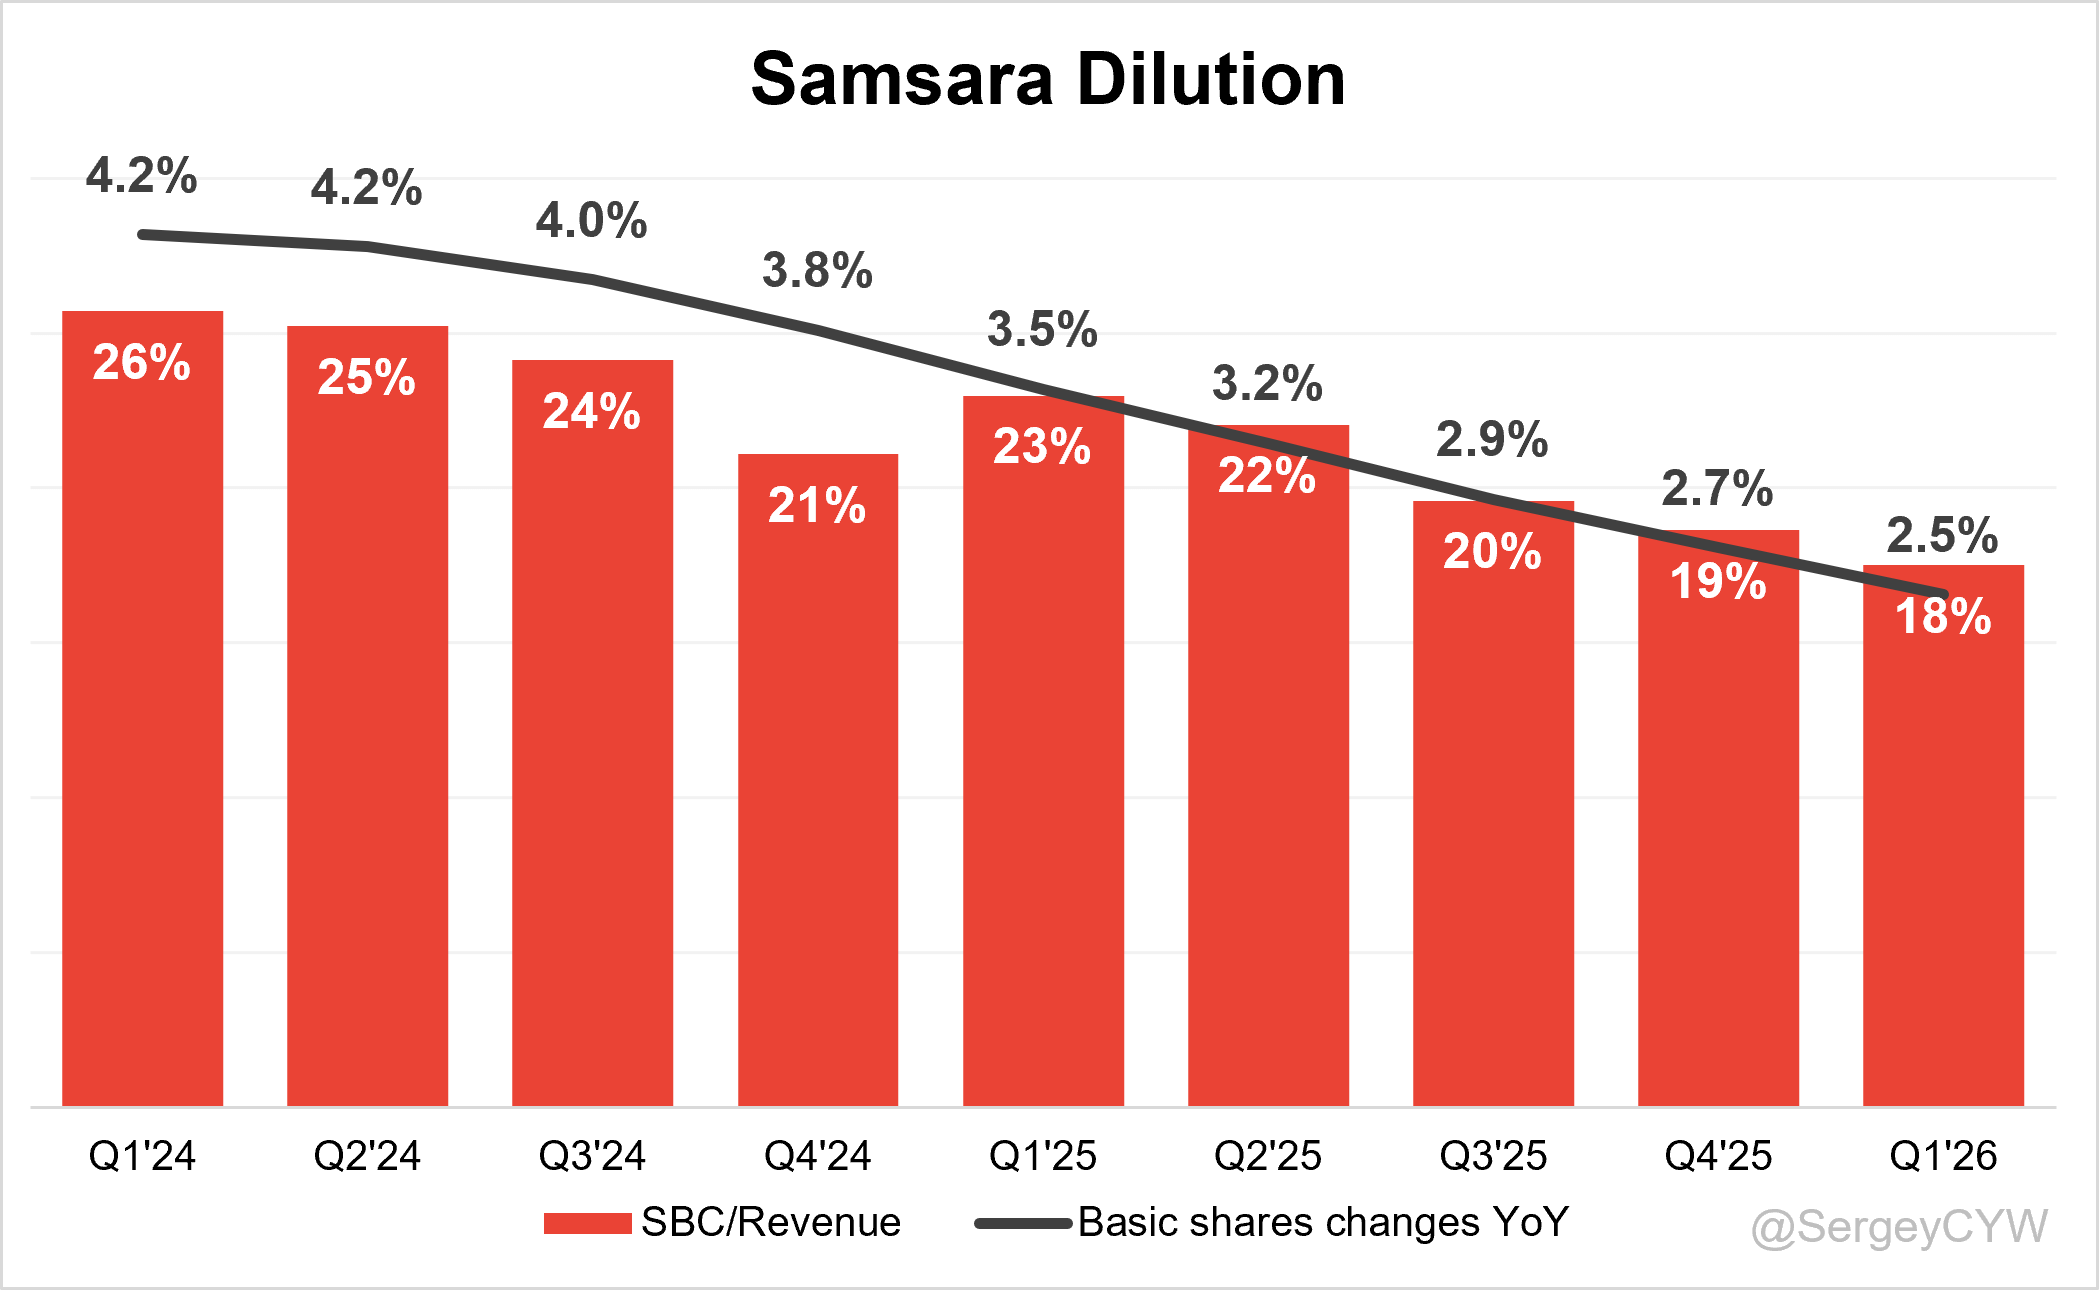
IOT Samsara Shareholder Dilution: Stock-based compensation expenses have been gradually declining over the past two years and reached 18% of revenue, which looks acceptable given the company’s high revenue growth.
Shareholder dilution remains relatively elevated, although it has declined significantly over the past two years. The weighted-average basic shares outstanding increased by 2.5% YoY in Q1.
9. Conclusion
Samsara IOT continues to strengthen its position and delivered a strong Q1 FY2026, showing an acceleration in revenue growth.
Leading Indicators
· RPO growth of +44.7%, which is above revenue growth
· Billings growth of +28.5%, slightly below revenue growth
· ARR growth at +29.6% YoY, roughly in line with revenue
· Net new ARR additions at record level for Q1, up +30% YoY
· Customer additions with $100K+ ARR, and $1M+ ARR additions at record level for Q1
Key Metrics
· Net Dollar Retention (NDR) held steady at 115%
· The CAC Payback Period improved to 17.45 months and better than average for SaaS companies
· RDI Score increased to 2.04, which is above the median of the SaaS companies I track
Q2 outlook points to revenue growth stabilizing at a high level, supported by strong leading indicators. RPO growth accelerated sharply, significantly outpacing revenue growth, while ARR growth remains roughly in line with revenue.
At the same time, $100K+ ARR customers and $1M+ ARR customer additions reached a first-quarter record, showing that as Samsara’s platform expands, it is increasingly targeting larger enterprise customers.
It is also worth noting that revenue beat guidance by 5.0% in Q1, one of the company’s strongest beats over the past two years. Full-year revenue guidance was raised meaningfully by 1.9%, signaling management’s confidence in sustained growth.
Dominic Phillips, CFO “Looking ahead, we believe we’re well-positioned to sustain durable and efficient growth because we instrument physical assets with IoT hardware to generate a unique defensible data asset.”
Samsara continues to strengthen its competitive position through key product innovation. Key innovation areas include Connected Asset Maintenance, Asset Tags, AI Multicam, Waste Intelligence, Ground Intelligence, Ridership Management, Connected Workflows, Commercial Navigation, and agent-based automation.
Emerging products are now becoming a meaningful growth driver, contributing more than 20% of net new ACV for the second consecutive quarter. Management also expects that future AI agents may use consumption-based pricing.
Margins have improved significantly over the past year, although gross margin declined slightly compared to Q1 of last year. This was mainly due to higher AI and cloud investments, as well as the significant increase in DRAM and NAND costs.
Despite strong fundamentals, valuation has compressed and now sits below median levels, still near historical lows. Analysts forecast NTM revenue growth of +21.4%. Based on this forecast, Samsara appears slightly undervalued among SaaS peers, although I believe the company is likely to meaningfully exceed this expected growth rate.
Following the recent valuation reset, I slightly increased my position in May 2026. Currently, IOT represents 5.0% of my portfolio.
Thank you for reading!
Follow me for more frequent updates on X/Twitter and Threads, and on LinkedIn. For visual infographics, check out Instagram, and for portfolio changes, follow me on SavvyTrader.
Disclaimer: This earnings review is for informational purposes only and does not constitute financial, investment, or trading advice.